

Short Sale Bank Statements: Is a Screenshot Enough?
The seller opens their banking app, takes a screenshot, and sends it to the agent. It shows the balance and a few recent transactions. That should cover the bank statement request, right?
Not necessarily. A transaction screen and a monthly bank statement are different documents. Before submitting the screenshot, confirm what the mortgage servicer actually requested.
Fast Answer
Do not assume a banking app screenshot replaces a requested monthly statement in a short sale package. Follow the servicer's instructions for the accounts, statement periods, pages, and submission method. If the requested statement is unavailable, ask which alternative it will accept and document the answer before relying on a screenshot or activity printout.
A Balance Screen Does Not Tell the Whole Story
A phone screen may show today's balance, a selected date range, or only the transactions that fit on the display. Depending on the view, it may not show the account holder, statement period, beginning and ending balances, or the complete activity for the requested month.
A monthly statement is a document issued for a defined statement cycle. It may contain several pages, even when the account has little activity.
The issue is not whether the screenshot is genuine. It is whether it supplies the document and information the servicer asked for. Changing the filename to "bank statement" does not change what is inside it.
Read the Request Before Downloading Anything
Ask the short sale processor or servicer to clarify:
Which accounts are required for this file?
Which statement periods are required?
Are complete statements required, including every page?
What file format and secure submission channel should be used?
If a statement is unavailable, what substitute is acceptable?
Do not choose the number of months based on a generic internet checklist. Use the current request for the specific file. Our short sale package preparation guide covers how this document fits into the larger submission.
Look for Statements, Not Just Activity
In the banking website or app, look for a section called Statements, Documents, or something similar. Download the bank issued statement for the requested cycle if available.
Check the document against the request before forwarding it. Confirm that the period is correct, the account is the one requested, the pages are readable, and the download is complete. If it says "page 1 of 4," do not send only the first page.
Do not crop away information or remove pages because they seem unimportant. Ask about any required privacy masking before making changes, and preserve the original. Never alter balances, dates, ownership information, or transaction history.
What If the Latest Statement Has Not Been Issued?
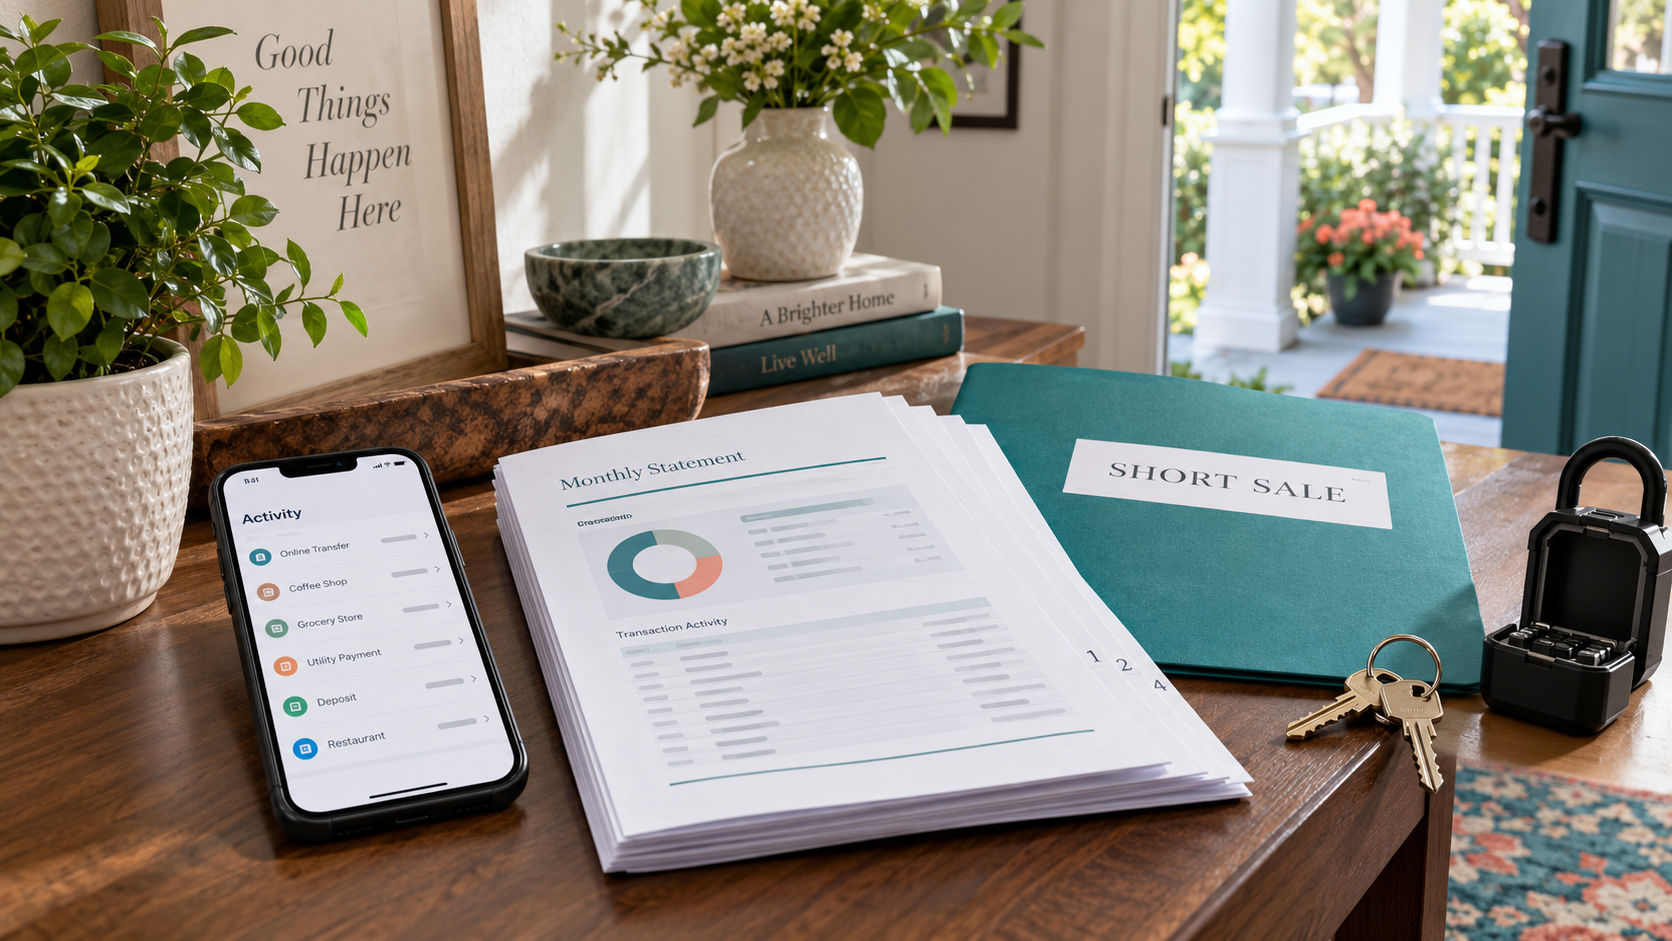
There may be recent activity after the latest completed statement cycle. An activity printout might help explain that period, but it should not automatically replace the monthly statement that was requested.
Ask whether the servicer wants the last issued statement, supplemental activity through a certain date, or another document. If the account is new, closed, or has no downloadable statement, explain that situation and request an acceptable alternative.
Do not create a homemade statement or edit an old one to cover a new period. Keep the explanation separate from the bank's original records.
Uploaded Is Not the Same as Accepted
A successful upload proves that a file reached the submission system. It does not prove that the reviewer accepted it as satisfying the bank statement condition.
Keep the upload confirmation and ask whether the document cleared the request. If the condition remains open, ask what is missing: the wrong period, an incomplete statement, the wrong account, or an unacceptable substitute.
This is one reason short sale approval can take longer than expected. Fixing a document issue can remove one obstacle, but it does not guarantee approval or a particular review timeline.
Keep Financial Records Out of Public Channels
Bank statements contain sensitive financial information. Use the servicer's approved portal or the secure channel your authorized short sale team specifies. Verify an unexpected upload request through a trusted contact before sending anything.
An agent or processor should never ask for the seller's banking password, verification code, or access to their online banking session. The seller can obtain the requested documents directly from their bank.
If the agent needs to describe the issue to someone outside the authorized file team, describe the document problem without attaching the seller's financial records.
A Simple Example
Suppose a servicer requests complete statements for specified months. The seller sends a phone screenshot showing today's balance and ten recent transactions.
The next step is not to upload the same screenshot again. The coordinator should compare it with the actual request, help the seller locate the issued statements, and ask the servicer to clarify any unavailable period or acceptable substitute.
This is an illustrative example, not a Crisp client case or a claim that every servicer uses the same requirements.
Bottom Line
A screenshot can show account activity without satisfying a bank statement request. Start with the specific instructions, obtain the original document when available, and confirm that the submitted material clears the condition.
Crisp Short Sales helps coordinate document requests and short sale processing so agents and sellers know what needs attention instead of guessing at another upload.
For homeowners exploring mortgage assistance, the Consumer Financial Protection Bureau recommends contacting the mortgage servicer and explains that a housing counselor can help with options and paperwork.
This article provides general educational information, not legal or financial advice. Documentation requirements and assistance options must be verified for the specific file. Sending documents does not itself guarantee that a foreclosure sale is postponed.