

Short Sale Relocation Assistance: Who Qualifies?
Could you qualify for short sale relocation help? Learn eligibility rules, common disqualifiers, and what to ask before moving.
Short sale relocation assistance can help a homeowner pay for moving expenses after an approved short sale. But assistance is not automatic. The rules can differ based on the mortgage investor, servicer, property type, occupancy, and program involved.
The safest approach is to ask the servicer for the exact eligibility rules before signing a move-out agreement or making plans based on expected funds.
What Is Short Sale Relocation Assistance?
Relocation assistance is money offered to help an eligible homeowner leave the property after a short sale. Some programs call this a relocation incentive. Private arrangements may also be described as cash for keys.
The Consumer Financial Protection Bureau advises homeowners pursuing a short sale to ask the lender or servicer whether help with relocation expenses is available through a private program. Rules vary, so a general promise from an agent, buyer, or third party is not a substitute for written confirmation from the servicer or investor.
Who May Qualify?
1. The home may need to be your principal residence
Some investor programs focus on homeowners who occupy the property as their principal residence. For example, Fannie Mae guidance describes a relocation incentive for an eligible borrower whose property is the borrower’s principal residence at the time of the evaluation notice.
That does not mean every owner-occupied short sale automatically qualifies. The servicer still has to confirm the loan’s program rules, required documentation, and closing conditions.
2. The short sale must be approved and successfully completed
Relocation assistance is generally connected to the successful completion of the short sale. An initial offer, verbal indication, or pending review does not guarantee payment.
Ask:
Is the relocation amount included in the approval letter?
Is payment conditioned on closing?
Who disburses the funds?
Is the payment made through the closing agent?
What happens if the closing is delayed or cancelled?
3. You may need to document occupancy and hardship
The servicer may request documents showing that the homeowner lives in the property or has a qualifying hardship. Requirements can include an occupancy certification, hardship letter, financial documents, or other evidence requested by the servicer.
Do not assume that a job transfer, financial hardship, or pending foreclosure automatically qualifies you. Ask the servicer which facts matter under the specific loan program.
Common Reasons Assistance May Be Denied or Delayed
The property is not your primary residence
An investment property, second home, or vacant property may be handled under different rules. Vacancy can also create questions about occupancy, property condition, and who is responsible for securing the home.
You are required to contribute money
Some programs may limit or deny relocation assistance if the borrower is required to contribute cash toward the short sale. Fannie Mae guidance identifies borrower contribution requirements as an exception that may affect the incentive. The servicer may need additional investor approval in some situations.
You are receiving another relocation benefit
Government relocation benefits, military relocation benefits, or other assistance may affect eligibility. Fannie Mae identifies certain relocation assistance connected with PCS orders as a potential exception. Confirm how any other benefit affects the short sale before relying on both payments.
The approval letter does not include the payment
If relocation assistance is not clearly addressed in writing, ask for clarification before moving. The final approval may contain conditions that were not included in earlier conversations.
The move-out timing is unclear
Moving too early, leaving personal property behind, or failing to follow the approved surrender terms can create closing problems. Ask for the required move-out date, property condition, key-transfer process, and inspection requirements in writing.
What Documents Should You Gather?
Depending on the servicer and investor, you may be asked for:
Proof of occupancy
A hardship letter
Mortgage statements
Income and expense information
Identification
A signed purchase contract
The short sale approval letter
A proposed move-out date
Evidence of other relocation benefits
Property-condition or vacancy information
The exact list varies. Ask the servicer or short sale processor for the current checklist before submitting documents.
Questions to Ask Before You Move
1. Do I qualify for relocation assistance under this loan program?
2. Is the payment included in the written approval?
3. What conditions must be satisfied before payment is released?
4. Is the amount paid at closing or afterward?
5. Who sends the funds?
6. Could a borrower contribution reduce or eliminate the payment?
7. Could another relocation benefit affect eligibility?
8. What date must I vacate the property?
9. What condition must the property be in at move-out?
10. What happens if the buyer delays or the closing is cancelled?
FHA and Other Program Rules May Differ
FHA loss-mitigation guidance says eligible borrowers in a pre-foreclosure sale may receive relocation expenses if they meet applicable conditions. That is different from saying every FHA short sale includes a guaranteed payment.
Because investor and servicer rules change, homeowners should confirm the current requirements for their loan rather than relying on a general dollar amount found online.
Bottom Line
Short sale relocation assistance may be available, but eligibility depends on the loan program, occupancy, hardship, investor rules, documentation, and closing conditions.
Before you move, get written answers about whether you qualify, how much assistance is approved, what could disqualify you, when payment will be released, and what move-out conditions apply.
A short sale processor or negotiator can help organize the documentation and identify missing conditions, but the servicer or investor controls final approval.
Need short sale help? Crisp Short Sales helps agents and homeowners organize short sale processing, lender follow-up, valuation issues, liens, approvals, and foreclosure timelines.
Short Sale Status Update: What to Ask When the Bank Goes Quiet
Bank silence can hide a specific bottleneck. Use these five questions to identify the review stage, set the next follow-up date, and keep the short sale moving.
When a short-sale file goes quiet, the silence usually has a reason. The lender may be waiting on a valuation, a missing document, a title item, a review queue, or a new approval condition. The fastest way to regain control is to ask focused questions that identify the exact bottleneck.
What “quiet” usually means
A silent servicer portal does not automatically mean the file was denied. It often means the file is waiting for a specific review step. Before promising a new closing date, confirm the last completed milestone, the current review stage, and the next required action.
The five questions to ask next
1. What is the exact active review stage?
Ask whether the file is in document review, valuation review, title review, investor review, or final approval. “Still under review” is not specific enough to plan around.
2. Is anything missing or expired?
Request a written list of missing items and check expiration dates on pay stubs, bank statements, hardship documents, authorization forms, and the purchase contract. One expired document can restart a review clock.
3. Has the value review been completed?
If a BPO or appraisal is pending, ask when it was ordered, whether the report is complete, and whether the lender needs repair notes or comparable sales. A value dispute can hold up the entire file.
4. Did the lender issue conditions or a counter?
Ask for every condition in one message. Keep the seller, buyer, title company, and lender working from the same list so the file does not receive partial answers on different days.
5. What date should trigger escalation?
Set a written follow-up date. If the lender misses that date, ask for the supervisor, short-sale negotiator, or escalation path instead of sending another generic status email.
How agents can keep the file moving
Create a one-page status log with the last lender contact, active review stage, missing items, valuation status, and next follow-up date. Send a short weekly update even when there is no news. Buyers are less likely to walk when they understand what the lender is waiting on.
For a deeper look at delay causes, see Crisp’s guide to why banks take so long to approve short sales: https://www.crispshortsales.com/the-short-sale-blog/buyer-ready-bank-silent-why-short-sales-take-so-long
If the file involves relocation money, verify the approval terms before promising payment: https://www.crispshortsales.com/the-short-sale-blog/2025/8/20/how-relocation-incentives-work-in-a-short-sale
If value is the bottleneck, review the FHA partial-claim and valuation issues agents should prepare for: https://www.crispshortsales.com/the-short-sale-blog/fha-short-sale-partial-claim-payoff
If HOA dues or a payoff letter is holding up closing, confirm who pays and what the lender must approve: https://www.crispshortsales.com/the-short-sale-blog/hoa-dues-short-sale-who-pays-before-closing
When to ask for short-sale help
Escalate when the lender misses a promised review date, repeats a request that was already satisfied, or gives no clear next step after a complete package was delivered. A short sale coordinator or negotiator can organize the file, track conditions, and keep every party aligned.
The bottom line
A quiet bank is a signal to get more specific, not a reason to guess. Identify the active review stage, confirm what is missing, set the next date in writing, and escalate through the correct channel when the lender misses it. That simple rhythm protects the seller’s options and gives the buyer a reason to stay engaged.
Backup Buyer in a Short Sale: What Goes to the Bank?
A short-sale buyer walked away. The seller is still under pressure, the foreclosure timeline is still moving, and now a backup buyer is ready.
The next question is not simply whether the new buyer can sign a contract. The real question is: What must go back to the lender before the short sale can keep moving?
A replacement buyer may help save the transaction, but the lender may need to review the new contract, buyer qualifications, financing, closing timeline, settlement numbers, and valuation before relying on the new offer.
Fast Answer
When a backup buyer replaces the original buyer in a short sale, the agent or short sale negotiator should promptly provide the lender with the replacement contract, buyer proof of funds or financing, updated disclosures and addenda, the revised settlement statement or net sheet, and an explanation for the buyer change.
Do not assume the original approval automatically transfers to the new buyer. The lender may require a new review, updated valuation, revised approval letter, or additional investor approval.
When a Backup Buyer Becomes Important
A backup buyer can become necessary when:
The original buyer cannot obtain financing.
The buyer's rate lock or loan approval expires.
The buyer becomes unwilling to wait.
Inspection reveals an issue the buyer cannot accept.
The buyer cannot close before the lender's approval deadline.
The buyer changes entities or assigns the contract.
The buyer decides to withdraw.
Can a Buyer Back Out of a Short Sale? explains the broader reasons buyers leave. This article focuses on the next stage: keeping the file alive after that happens.
Does the Original Short Sale Approval Transfer?
Usually, the team should not assume it does.
A short-sale approval is often tied to specific terms, including the approved buyer, purchase price, lender net, closing deadline, financing structure, approved credits, settlement statement, and investor conditions.
If the buyer changes, the lender may need to confirm that the new buyer is acceptable under the same short-sale terms. Some lenders may review a replacement buyer quickly. Others may require a more complete resubmission.
The file may also need a new valuation if the prior BPO or appraisal is outdated, if market conditions changed, or if the new contract changes the numbers. The safest assumption is that the buyer change needs to be disclosed and reviewed in writing.
What to Send the Lender
The replacement-buyer package should be organized and easy to review.
The signed replacement purchase contract.
Any required short-sale addenda.
Proof of funds or current loan-preapproval documentation.
The buyer's proposed closing date.
Updated buyer information and contact details.
An explanation of why the original buyer is no longer proceeding.
A revised net sheet or settlement statement.
Updated payoff, title, HOA, tax, or lien information if the delay changed those figures.
A request for written confirmation that the lender will review the replacement buyer.
A request for an extension if the original approval deadline is approaching.
The goal is to avoid sending the new contract alone and waiting for the lender to discover the rest of the changes.
What If the Original Buyer Was Already Approved?
If the bank already issued an approval letter for the original buyer, the approval may identify that buyer by name or entity. Replacing the buyer can affect arm's-length requirements, financing terms, proof of funds, closing timing, buyer credits, investor conditions, and resale or assignment concerns.
The short sale coordinator or processor should compare the old approval letter with the new contract and identify every term that changed.
If the lender requires a revised approval letter, the parties should not close under the old letter and hope the difference is ignored.
Could the Lender Order a New BPO?
It may. A lender may rely on an existing valuation if the offer and terms remain substantially consistent. But a new buyer can still trigger questions about price, financing, credits, marketability, or the time that has passed since the original BPO.
If the lender orders a new BPO or appraisal, the agent should prepare current comparable sales, property-condition photos, repair information, listing history, buyer feedback, evidence of market exposure, and any facts explaining why the replacement buyer's offer is reasonable.
For valuation context, see BPO vs. Appraisal: What Moves the Number?
How to Keep the Replacement Buyer Engaged
A backup buyer may understand that short sales take time, but that does not mean the buyer will wait without clear communication.
The buyer's agent should understand whether lender review has restarted, which documents were sent, whether the prior approval remains usable, whether a new valuation is required, whether the approval deadline needs an extension, what milestone comes next, and who owns the next update.
Avoid promising a specific approval date unless the lender has provided one. A better update is: “The original buyer withdrew, and the replacement contract has been submitted for lender review. We are confirming whether the lender needs a new valuation or approval letter and will update you when that review is answered.”
What the Seller Should Know
The seller should understand that a replacement buyer may save the opportunity, but it may also add another review cycle.
Has the lender been notified?
Was the new contract submitted?
Does the lender need updated financial or title documents?
Is the approval deadline still active?
Could relocation assistance or seller-contribution terms change?
Does the new buyer's financing affect the lender's net?
If the short sale is already waiting on the bank, use Why Is the Short Sale Still Waiting on the Bank? for the status-review framework.
Bottom Line
A backup buyer can keep a short sale alive after the original buyer leaves, but the replacement should be treated as a lender-review event.
Send the new contract, buyer qualifications, financing information, updated settlement numbers, and a clear explanation of the change. Then confirm in writing whether the lender needs a new valuation, revised approval letter, or deadline extension.
The fastest path is an organized replacement-buyer package that lets the short sale processor or negotiator answer the lender's next questions before the file loses more time.
For help organizing the replacement submission, agents can start a short sale with Crisp.
This article is general information, not legal, tax, lending, or contract advice. Requirements vary by lender, investor, servicer, loan type, contract, and state.
Investor Approved the Short Sale. Where Is the Letter?
The investor reportedly approved the short sale, but the written letter has not arrived. Here are five questions agents can ask before promising a closing date.
Fast Answer
An investor's reported approval is good news, but it is not the same as a final short sale approval letter the closing team can use. Before telling the buyer the deal is clear to close, ask the servicer to confirm exactly what was approved, whether any conditions remain, who is issuing the written letter, and when title can expect it. Keep the buyer's timeline realistic until the written terms match the actual contract and closing figures.
What To Do Next
Ask whether the investor decision is final, conditional, or only a recommendation.
Confirm whether mortgage insurance or another lienholder still has a separate decision to make.
Find out which servicer team owns the final letter and what item it is waiting on.
Check the current contract and estimated settlement statement against the terms the servicer says were accepted.
Give the buyer a factual status update, not a closing date based on a verbal promise.
The Update Sounds Final. The File Is Not.
An agent hears, "The investor approved it." The buyer asks when to schedule movers. Title asks for the short sale approval letter. The letter is not there.
This is a particularly frustrating delay because the hardest decision may be over. But the word approved can describe different stages. A representative may mean the investor accepted the proposed loss, accepted it subject to conditions, or returned a decision that the servicer still has to translate into final transaction instructions. On some loans, the servicer has delegated approval authority, so there may not be a separate investor decision at all. The process depends on the loan and the servicer's authority. Fannie Mae's non-delegated short sale guidance describes a decision letter with terms and conditions; Freddie Mac's guide shows why approval authority varies.
The practical rule is simpler: do not turn an encouraging status update into a promised closing date until the written approval for this buyer and these terms is in hand.
Five Questions That Find the Missing Step
1. What exactly did the investor approve?
Ask for the decision date, the approved offer amount or required net proceeds, and whether the decision included conditions. If the servicer cannot confirm these details, "investor approved" may be a shorthand status rather than a final answer. Ask whether the decision has been recorded in the file and whether the assigned negotiator can see it.
2. Is anyone else still reviewing the deal?
Mortgage insurance, junior liens, and title issues may still affect the transaction even after one party agrees. Do not assume the investor's decision cleared every other approval path. If the file is still waiting for investor review, Crisp's guide to the hidden second approval addresses that earlier stage.
3. Who owns the final letter now?
Ask which servicer team will issue the approval letter, whether it has the investor decision, and whether the letter is being drafted, reviewed, or held for a missing item. A short sale negotiator should document the owner and next action, not settle for "it is in process."
4. What must match before the letter can go out?
The written terms may need to match the current buyer, contract price, closing costs, payoff figures, seller contribution, and net proceeds. If a revised settlement statement or updated payoff is required, get that request in writing and send one complete correction. This is a different problem from a general bank delay; our short sale delays guide maps the other possible bottlenecks.
5. When can title expect a usable copy?
Request the servicer's next documented action date and delivery method. Ask whether the approval window will leave enough time for buyer financing, title clearance, signing, funding, and any required closing review. There is no universal number of days from investor sign-off to letter issuance, so treat a verbal target as a follow-up date, not a guaranteed closing date.
A Follow-Up Message Agents Can Send
We understand the investor decision was received on [date]. Please confirm whether it is final or conditional, whether any other approval remains open, the exact item holding the written short sale approval letter, and which team is responsible for issuing it. Our buyer's current deadline is [date]. Please also confirm the next action date and where the final letter will be delivered.
Keep the message tied to facts already in the file. If the servicer identifies a missing document or number, respond to that request directly and retain proof of submission. A short sale processor or coordinator can then follow the item through to the actual letter, rather than repeating the same broad status question.
What To Tell the Buyer and Title
Try: "The servicer reports a positive investor decision, but we do not yet have the written short sale approval terms. We are confirming the remaining conditions and the letter's delivery date. We will share a closing timeline once title has reviewed the letter."
That update is honest without sounding defeated. It also protects the buyer from spending money or making moving commitments based on a date that the approval letter may not support.
When the letter arrives, have title and the short sale team compare it with the contract and closing statement. Our approval-letter clause checklist covers the deadline, net proceeds, allowed costs, seller obligations, junior liens, and other terms that can stop a closing even after approval. If the letter addresses a deficiency, the seller should review the exact language with a qualified attorney or tax adviser as appropriate. The CFPB recommends obtaining any deficiency waiver in writing.
Bottom Line
"Investor approved" is a milestone, not a document title can close from. Confirm the decision's scope, clear remaining conditions, identify the team issuing the letter, and keep the buyer informed with facts. Then review the written terms before treating the deal as ready to close.
If your agent team needs help tracking that handoff, start a short sale with Crisp and share the current approval status and deadlines.
Why Short Sale Offers Get Rejected Even When the Buyer Is Ready
A buyer can be qualified and ready, but a short sale offer can still be rejected if the lender does not like the value, net proceeds, liens, closing terms, or file risk.
Fast Answer
A short sale offer can be rejected even when the buyer is qualified, the seller accepted the contract, and everyone wants to close.
That is because the lender is not just approving the buyer. The lender is reviewing the entire short sale file: property value, net proceeds, closing costs, lien payoffs, title issues, buyer terms, hardship documents, investor rules, and the risk that the deal will not close inside the approval window.
If the offer does not support the lender's required recovery, the bank may reject it, counter it, request more documents, or send the file back for another review.
What To Do Next
Ask for the specific reason the short sale offer was rejected.
Review the lender's value, BPO, or appraisal issue before changing price.
Check the estimated settlement statement and net proceeds.
Confirm whether liens, HOA dues, taxes, or closing costs are reducing the lender's recovery.
Make sure the buyer's financing, credits, and closing timeline match short sale approval rules.
Submit repair photos, condition notes, or better comps if the value is wrong.
Use short sale help if the file needs a structured counter, value dispute, or escalation.
Seller Acceptance Is Not Lender Approval
This is the part that surprises buyers the most.
In a normal sale, a seller can accept an offer and the deal moves toward closing. In a short sale, seller acceptance is only one step.
The lender still has to decide whether it will accept less than the full mortgage payoff. That means the lender is looking at the deal from a different angle than the buyer, seller, or agents.
The buyer may be ready.
The seller may be cooperative.
The contract may be signed.
But the lender may still say no if the file does not make financial sense under the investor's rules.
That is why agents should not treat a signed short sale contract as a final approval. It is a starting point for lender review.
If you are trying to understand the broader reasons a deal can fail, Crisp's related guide on why short sale offers get rejected is the main support page. This article goes deeper on the specific situation where the buyer is ready but the bank still rejects the offer.
If the lender has not rejected the offer but the file has gone quiet, the next issue may be different. Crisp's guide on short sale offers getting ignored explains what the bank may still be waiting for before it responds.
Reason 1: The Bank's Value Is Higher Than the Offer
One of the most common reasons a short sale offer gets rejected is value.
The lender usually needs a property valuation before approving the short sale. Depending on the loan, servicer, and investor, that review may involve a BPO, appraisal, desktop valuation, internal value model, or updated market review.
If the bank's value comes in higher than the offer, the lender may believe the property should sell for more.
That does not always mean the bank is right.
The property may need repairs. The BPO agent may have used stronger comps. The valuation may not reflect access problems, deferred maintenance, neighborhood differences, tenant issues, or a tight foreclosure timeline.
But until the file shows better evidence, the lender may reject the offer or counter higher.
This is where agents should slow down and diagnose the value problem before assuming the buyer is the problem. Review the short sale BPO vs appraisal issue and gather the proof needed to challenge the number.
Reason 2: The Net Proceeds Are Too Low
A lender does not only look at the contract price.
It looks at what the lender will actually receive after closing costs, commissions, tax prorations, title fees, HOA balances, junior liens, buyer credits, repairs, and other approved expenses.
That final number is the net.
Two offers with the same purchase price can produce very different net proceeds. One offer may include heavy seller-paid costs. Another may have clean financing and fewer deductions. One file may have an HOA payoff, tax lien, or second mortgage that eats into the settlement.
If the lender's required net is not met, the buyer can be ready and the file can still be rejected.
This is why agents should not negotiate only from the purchase price. They should review the estimated settlement statement and ask:
What is the lender's expected net?
Which closing costs are being charged to the seller side?
Are any buyer credits reducing the lender's recovery?
Are junior liens, HOA dues, taxes, or judgments lowering the net?
Does the approval path require a minimum payoff or investor threshold?
If the numbers do not work, the solution may not be "find a new buyer." The solution may be a cleaner net sheet, a revised counter, a lien negotiation, or a better explanation of the property's true value.
Reason 3: The Buyer Terms Create Closing Risk
A ready buyer is not always a lender-ready buyer.
The buyer may be approved for financing, but the lender may still dislike the terms of the contract.
Common problems include:
Closing date is too far out.
Buyer financing has too many conditions.
Inspection period creates uncertainty.
Buyer requests seller-paid repairs or large credits.
Contract terms do not match the lender's approval requirements.
Buyer entity, assignment language, or investor terms trigger more review.
Settlement statement does not line up with the offer.
Short sale approvals are often specific. They may approve a certain buyer, price, closing date, net amount, and cost structure. If the buyer's terms create too much uncertainty, the lender may reject, counter, or ask for a cleaner structure.
That does not mean the buyer is bad. It means the offer needs to be reviewed through the lender's approval lens, not just the normal contract lens.
Reason 4: The File Is Not Complete Enough for Approval
Sometimes the offer gets blamed when the real issue is the file.
The lender may still need hardship documents, financial forms, bank statements, pay stubs, tax returns, authorization forms, title information, payoff statements, buyer proof of funds, updated settlement numbers, or investor-specific forms.
If the short sale package is incomplete, stale, inconsistent, or missing a required item, the servicer may not be ready to approve the offer.
This can feel like a rejection from the buyer's side because the file is not moving. But the fix may be documentation, not price.
Before assuming the lender rejected the buyer, confirm:
Has the servicer marked the short sale package complete?
Are seller documents current?
Has title been reviewed?
Are payoff statements updated?
Has the buyer proof been accepted?
Is the settlement statement consistent with the contract?
If those items are not clean, the buyer may be ready but the file may not be.
Reason 5: Liens or HOA Balances Change the Math
Short sales often involve more than one payoff.
A second mortgage, HOA balance, tax lien, judgment, code lien, old title issue, or collection account can create a problem even when the first mortgage is willing to review the sale.
The first lienholder may only allow a limited amount to go to junior liens. A junior lienholder may demand more. The HOA may have legal fees or collection costs. Taxes may need to be paid. Title may need a release before closing.
When these items reduce the amount available to the first mortgage, the offer may no longer meet the lender's required net.
That is why title and payoff work should not wait until the approval letter arrives. If the file has hidden liens, the offer can look acceptable at first and still fail once the full settlement picture is known.
Reason 6: The Offer Came Too Late
Timing can also cause a rejection.
If the foreclosure sale date is close, the servicer may not have enough time to review the full package, order value, clear conditions, obtain investor approval, and issue short sale approval before the deadline.
Some files can still be escalated. Some cannot.
The closer the file gets to a foreclosure date, the more important it becomes to know what the lender still needs and whether the servicer will review the short sale in time.
An offer that would have worked 45 or 60 days earlier may be much harder to approve if the file is already inside a tight deadline.
What Agents Should Ask After an Offer Is Rejected
Do not stop at "the bank rejected it."
Ask what the bank rejected.
The next move depends on the answer.
If the value is too high, the agent may need repair photos, better comps, a BPO dispute, or a revised pricing argument.
If the net is too low, the file may need a corrected settlement statement, cost review, buyer counter, lien negotiation, or revised payoff strategy.
If the file is incomplete, the seller side may need updated documents, title work, hardship support, or missing servicer forms.
If the buyer terms are the issue, the buyer may need cleaner financing terms, fewer credits, a stronger closing timeline, or a revised contract.
If timing is the problem, the file may need escalation and a realistic conversation about whether the review can be completed before the deadline.
This is also where experienced short sale negotiation matters. The response should match the reason for rejection. If the problem is value, negotiate value. If the problem is net, negotiate net. If the problem is missing documents, fix the package.
For value-specific files, Crisp's guide on how to negotiate a short sale after a high BPO is a good next read.
When Short Sale Help Makes the Difference
Short sale help matters when the file needs more than a quick price change.
A short sale specialist or processor can help organize the package, track servicer requests, check the net sheet, coordinate with title, prepare value evidence, respond to counters, and keep the review moving before deadlines get tight.
That is especially important when the buyer is ready but the lender is not approving the deal.
The goal is not to argue emotionally that the buyer is serious. The goal is to show the lender why the offer is the best available recovery under the facts of the file.
That usually means clean documents, clear value support, realistic net proceeds, and a closing path that matches lender requirements.
Bottom Line
A ready buyer does not automatically mean an approved short sale.
The lender still has to approve the value, net proceeds, liens, settlement terms, buyer structure, seller package, and timing.
If a short sale offer gets rejected, agents should find the real reason before starting over. The right fix may be a value dispute, cleaner settlement statement, lien negotiation, stronger buyer terms, updated documents, or an escalation.
Do not treat "buyer ready" as the finish line. In a short sale, the lender is approving the whole file.
FAQ
Can a bank reject a short sale offer after the seller accepts it?
Yes. In a short sale, seller acceptance does not equal lender approval. The lender can still reject or counter the offer if the value, net proceeds, buyer terms, documents, liens, or timing do not meet approval requirements.
Why would a short sale offer be rejected if the buyer is qualified?
The buyer may be qualified, but the lender may still believe the offer is too low, the net proceeds are too weak, the file is incomplete, the buyer terms create risk, or liens and costs make the deal unacceptable.
Can you negotiate after a short sale offer is rejected?
Often, yes. The next step depends on why the offer was rejected. Agents may need to challenge value, revise the settlement statement, improve buyer terms, resolve liens, submit updated documents, or respond to a lender counter.
Is a short sale rejection always about price?
No. Price matters, but many short sale rejections are really about net proceeds, property value support, liens, title issues, missing documents, buyer terms, or timing.
Risks of Buying a Short Sale Home: What Can Still Change Before Closing
Buying a short sale home can be a good opportunity, but approval, title, liens, credits, deadlines, and closing terms can still change before closing.
Fast Answer
Buying a short sale home can be a good opportunity, but it is not the same as buying a regular listing. The biggest risks are lender approval delays, a bank counteroffer, title or lien problems, inspection issues, financing delays, closing-date pressure, buyer-credit limits, and approval-letter conditions that do not match the final deal.
The safest move is to treat the short sale as conditional until the written approval letter is reviewed, the title and payoff numbers match, and the closing team confirms the deal can close under the bank's terms.
Why Short Sale Buyers Need a Different Checklist
A short sale can look simple from the buyer's side.
The buyer finds the home, makes an offer, negotiates price, signs the contract, and waits for the seller's lender to approve the sale.
But that lender approval changes the transaction.
In a regular sale, the seller can usually accept an offer and move toward closing. In a short sale, the seller's mortgage lender is being asked to accept less than the full amount owed. That means the bank, servicer, investor, mortgage insurer, or junior lienholder may need to approve the price, buyer, closing costs, payoff numbers, timeline, and final settlement statement.
That is why buyers should understand the risks before they lock in emotionally, spend money on inspections, or assume the home is theirs.
This does not mean buyers should avoid short sales.
It means they should know what can still change.
Risk 1: The Bank Can Take Longer Than Expected
Short sales often move slower than buyers want.
Even after the seller accepts the offer, the lender may still need a complete short sale package, hardship review, property valuation, investor review, mortgage insurance review, title review, payoff review, and final approval-letter review.
That process can take time.
The buyer should ask whether the short sale package has been submitted, whether the file is complete, whether the bank has ordered or reviewed the value, and whether any investor or mortgage insurance approval is still open.
If the buyer has a lease ending, loan-rate lock expiring, moving deadline, or another home they need to sell, the delay risk needs to be managed early.
Risk 2: The Bank May Counter the Price
A short sale offer is not final just because the seller accepted it.
The lender may review the property value and decide the buyer's offer is too low. That can lead to a counteroffer, a request for stronger buyer proof, a request for updated comps, or a demand for better net proceeds.
This is where short sale buyers can get frustrated. They may feel like the seller already agreed, so the deal should be done.
But the bank is reviewing the loss.
If the bank's value comes in higher than the contract price, the buyer may need to decide whether to raise the offer, support the original price with condition evidence, or walk away if the numbers no longer make sense.
For agents dealing with a price dispute, Crisp's guide to changed short sale terms after approval is also useful because changed price or closing terms may need bank review.
Risk 3: Title, Liens, or Payoffs Can Change the Deal
Short sale closing risk is not always about the first mortgage.
There may be junior liens, HOA balances, tax liens, judgments, municipal charges, utility liens, code issues, payoff changes, or title defects that must be resolved before closing.
Those issues can affect whether the short sale lender approves the final net, whether the seller can deliver clear title, and whether the buyer can close on time.
The buyer should make sure the title company is involved early and that payoff or lien issues are being checked before the approval deadline is tight.
If title finds a problem late, the buyer may be ready but the file may still not be able to close.
Risk 4: The Approval Letter May Limit Credits and Costs
Short sale approval letters often include specific terms.
Those terms may limit buyer credits, repair credits, seller concessions, commissions, closing costs, junior lien payments, relocation funds, or other settlement items.
That matters because a buyer may negotiate something in the contract that the bank later refuses to allow.
For example, a buyer credit, repair request, seller-paid cost, or changed closing number might be normal in another transaction. In a short sale, it may reduce the bank's approved net or conflict with the written approval terms.
Before closing, the buyer's agent and closing team should compare the final settlement statement against the approval letter.
For a deeper checklist, review Crisp's article on short sale approval letter clauses that can delay closing.
Risk 5: Inspection Issues Can Be Harder to Negotiate
Inspection issues can be more complicated in a short sale.
The seller may not have money for repairs. The lender may not approve a price reduction or credit without review. The buyer's loan may require certain repairs before funding. And the approval timeline may not leave much room for renegotiation.
That does not mean inspection problems cannot be solved.
It means buyers should understand the order:
Identify the issue.
Decide whether the buyer still wants the property.
Confirm whether the repair affects financing.
Determine whether the contract price, credit, or closing terms need to change.
Send any required change through the short sale negotiator before assuming the bank will accept it.
If the issue is major, the buyer needs a clear yes-or-no path quickly.
Risk 6: Closing Dates Can Get Tight
Short sale approvals usually come with deadlines.
The approval letter may require closing, funding, or settlement by a specific date. If the buyer's loan is not ready, title is still clearing, payoffs are stale, or final numbers are not approved, the file may need an extension.
The risk is waiting too long to ask.
Buyers should watch their financing timeline, appraisal timing, inspection deadlines, document requests, and closing conditions closely. Agents should avoid letting the deal drift until the approval letter is about to expire.
Once the approval clock is running, every delay matters.
Risk 7: A Buyer Can Still Walk, But Timing Matters
Buyers sometimes ask whether they can back out of a short sale.
The answer depends on the contract, deadlines, contingencies, state rules, and the exact situation. That is a legal and contract question, so the buyer should speak with their agent, broker, or attorney before making that decision.
From a practical short sale standpoint, though, the buyer should not wait until the file is near approval to raise issues that were visible weeks earlier.
If the buyer is losing patience, needs a deadline, or wants clearer answers, the team should ask direct questions before the deal reaches a breaking point.
For more on that issue, see Crisp's guide on whether a buyer can back out of a short sale.
What Buyers Should Confirm Before Closing
Before closing on a short sale home, buyers and their agents should confirm:
Has the lender issued written short sale approval?
Does the approval letter name the correct buyer, price, property, and closing deadline?
Do the final closing numbers match the approval terms?
Are all liens, HOA balances, taxes, payoffs, and title issues resolved?
Are any repair credits, buyer credits, or concessions allowed?
Is the buyer's loan ready within the approval deadline?
Does the title company have everything needed to close and fund on time?
Has any changed term been sent back to the lender if required?
That checklist helps separate a normal short sale delay from a real closing risk.
When Short Sale Help Makes the Difference
A buyer does not need panic.
A buyer needs clarity.
That is where experienced short sale help can protect the deal. A short sale processor, negotiator, or coordinator should keep the lender review moving, track the active condition, flag approval-letter problems, coordinate with title, and make sure changed terms are handled before closing day.
The goal is not to promise that every short sale will close.
The goal is to find the real risk early enough to fix it.
Final Takeaway
Buying a short sale home can be worth it, but buyers should not treat the deal like a regular closing.
The lender still controls approval. Title and lien issues can still change the numbers. Inspection and financing issues can still affect the contract. The approval letter can still limit what is allowed at closing.
The best buyer is patient, prepared, and clear on what needs to be confirmed before the moving truck is scheduled.
Short Sale File Complete? Why Approval Still Waits
Short sale package complete but still no approval? See what agents should ask before the buyer, deadline, or review clock slips.
The short sale package is complete.
That should feel like progress, and it is. But it does not always mean approval is close.
This is where a lot of agents get frustrated. The seller sent documents. The buyer is waiting. The lender or servicer may even say the file is "complete." Then another week goes by with no approval letter, no clear decision, and no real answer.
The problem is that "complete" is not the same as "approved."
In short sale processing, a complete package usually means the file has enough documents to move into review. It does not mean every review lane is finished, every investor condition is cleared, or the written approval letter is ready.
That distinction matters because this is the stage where buyers start asking whether they should walk.
Fast Answer
If a short sale package is complete but approval is still waiting, the file may still be in property review, investor review, mortgage insurance review, title review, payoff review, closing-cost review, or approval-letter drafting. Agents should ask which review lane is active, whether any condition is open, whether the review clock reset, and what exact item is needed next.
The safest next step is a specific status request, not another general "any update?" email.
What "Complete Package" Usually Means
When the lender says the short sale package is complete, it usually means the required submission items have been received.
That may include the hardship letter, financial worksheet, bank statements, pay stubs, tax documents, authorization, purchase contract, listing agreement, buyer proof, and estimated settlement statement.
That is important. An incomplete file can sit still for avoidable reasons.
But a complete file is only the starting line for review. The lender still has to decide whether the offer, property value, title, seller hardship, investor rules, and closing numbers all support approval.
That is why a file can be complete and still not be ready for a yes.
The First Question: Is the File Actually Assigned?
A file can be marked complete but not fully assigned to the person who can move it.
That sounds small, but it can cost time. The file may be sitting in intake. It may be waiting for a short sale negotiator. It may be in a queue for valuation. It may be pending an internal review task before anyone can issue a decision.
The agent should ask:
Has the file been assigned for short sale review, and who owns the next action?
If the answer is vague, ask for the department or review lane. "In review" is not enough when a buyer deadline is getting closer.
The Second Question: Did the Review Clock Reset?
Short sale files often reset when updated documents are requested.
This is one reason a file can feel like it is moving backward. A lender may ask for updated bank statements, a newer payoff, a corrected authorization, revised buyer proof, a missing addendum, or a new settlement statement. Once that item is added, the file may go back into a review queue.
Agents should ask:
Was the file returned to review after the latest document was added, and what is the expected review time from that date?
That question helps separate a real delay from a clock reset.
The Third Question: Is Valuation Holding the File?
Even with a complete package, the lender still needs a value opinion.
That may be a BPO, appraisal, automated value check, review of comparable sales, repair evidence, or investor value screen. If the bank value is not accepted, the lender may not approve the short sale even if the buyer is ready.
Ask:
Has the BPO or appraisal been ordered, completed, received, reviewed, and accepted?
Those are different steps. A file can be delayed at any one of them.
If value is the issue, the next move may be better comps, condition photos, repair proof, or a value dispute. For that deeper issue, agents should also review short sale BPO vs appraisal guidance.
The Fourth Question: Is Investor Review Still Open?
The servicer may not be the final decision-maker.
Many short sale files need investor approval before the servicer can issue written terms. Investor rules can affect the acceptable payoff, closing timeline, relocation money, deficiency language, contribution requirements, and allowed closing costs.
Ask:
Has the file been submitted to the investor, or is it still inside servicer review?
This is one of the cleanest ways to understand whether the delay is local to the servicer or waiting on a higher approval layer.
The Fifth Question: Is Mortgage Insurance Involved?
Mortgage insurance can add a separate approval step.
If mortgage insurance is involved, the servicer may need that company to approve the loss before final short sale approval can be released. That may create additional document requests or contribution conditions.
Ask:
Is mortgage insurance involved, and has that review been submitted or approved?
Do not assume the bank is simply ignoring the file. Sometimes the delay is a separate approval that has not been explained clearly.
The Sixth Question: Do Title, Liens, HOA, or Payoffs Match?
A short sale approval depends on the net number.
That means the lender cares about more than the contract price. It also cares about payoff amounts, junior liens, HOA balances, tax liens, judgments, closing costs, commission, repairs, seller credits, and any fee that changes the expected recovery.
If those numbers do not line up, approval can stall late.
Ask:
Are any title, lien, payoff, HOA, or settlement statement conditions holding approval?
This question is especially important when everyone thinks the file is waiting only on the bank, but the real issue is closing math.
The Seventh Question: Is the Approval Letter Being Drafted?
Sometimes the file is close.
The lender may have verbal approval, internal approval, investor approval, or accepted terms, but the written approval letter has not been released yet.
That stage still matters. The buyer, seller, agent, and title company should not treat the short sale as fully approved until the written approval letter is issued and the closing terms are reviewed.
Ask:
Has final approval been issued in writing, or is the approval letter still being drafted?
If it is being drafted, ask whether any condition must be cleared before release.
What Agents Should Send Instead of "Any Update?"
When the file is complete but approval is still missing, send a status request that forces clarity.
A better message asks:
Is the file marked complete?
What date did the current review clock start?
Which review lane is active right now?
Is valuation complete and accepted?
Has investor review been submitted?
Is mortgage insurance involved?
Are any title, lien, payoff, HOA, or settlement conditions open?
Is the approval letter pending or already drafted?
What exact item or action is needed next?
That is stronger than asking for a general update because it gives the servicer fewer places to hide behind vague language.
When a Short Sale Processor Helps
This is where short sale assistance can be most useful.
A short sale processor or short sale negotiator should keep the documents organized, track the active review lane, log follow-ups, manage buyer urgency, and push the next correct action without burying the servicer in duplicate requests.
The goal is not to make noise.
The goal is to find the bottleneck and move it.
If the buyer is losing patience, the file needs specific answers quickly. If the foreclosure clock is active, the file needs even tighter follow-up. If approval is close, the written approval letter still needs to match the closing numbers before anyone celebrates.
Final Takeaway
A complete short sale package is good news, but it is not the finish line.
If approval is still waiting, find out whether the hold is assignment, review-clock reset, valuation, investor review, mortgage insurance, title, payoff, HOA, settlement statement, or approval-letter drafting.
Then ask for the exact next action.
That is how agents turn "the file is complete" into a real path toward approval.
Short Sale Relocation Assistance at Closing: When Is the Money Actually Paid?
Short sale relocation assistance is usually paid at closing, but only if the approval letter, settlement statement, conditions, and funding timing all match.
Short sale relocation assistance can make a difficult move feel possible.
For a seller leaving a home under financial pressure, that money may help with a rental deposit, moving truck, storage unit, utility setup, or just the basic cost of getting settled somewhere else. For the agent, it can also help keep the seller engaged through closing instead of letting the file fall apart at the last step.
But there is one question that gets misunderstood all the time:
When is the relocation money actually paid?
The short answer is that short sale relocation assistance is usually paid at closing, not before. It must be approved in writing, shown correctly on the settlement statement, allowed by the servicer or investor, and released through the closing process under the exact terms of the approval.
If one of those pieces is missing, the money can be delayed, reduced, or denied even when everyone thought it was handled.
Fast Answer
Short sale relocation assistance is typically paid at closing through the settlement agent, title company, or closing attorney, as long as the payment is clearly allowed in the short sale approval letter and shown correctly on the final settlement statement.
The seller should not expect relocation money before closing unless the servicer gives clear written instructions saying otherwise. The safest move is to confirm the approval letter, payee, amount, closing deadline, occupancy or move-out conditions, and final settlement statement before the seller relies on the funds.
This is process guidance for agents and sellers, not legal, tax, credit, or financial advice. The final answer depends on the loan, investor, servicer, approval letter, closing documents, state process, and title or attorney requirements.
What To Do Next
- Confirm that the approval letter clearly allows relocation assistance.
- Check the exact amount, payee, and conditions.
- Make sure the payment appears correctly on the settlement statement.
- Ask title or the closing attorney how the seller will receive the funds.
- Reconfirm the payment if the closing date, buyer, payoff, net sheet, or occupancy status changes.
- Get short sale help before the seller plans a move around money that is not fully confirmed.
Relocation Assistance Is Usually Not Paid Upfront
Many sellers hear "relocation assistance" and picture money arriving before they move.
That is usually not how it works.
In most short sales, relocation assistance is tied to the approved closing. The lender or investor is agreeing to let the seller receive a specific payment if the sale closes under approved terms. The money is usually reflected on the final settlement statement and disbursed through the closing process.
That means the seller may not have the money in hand for deposits, movers, storage, or rent before closing day.
This is important because it affects planning. If a seller needs relocation funds to move before closing, the agent should not assume the payment will arrive early. The seller may need a realistic plan for the gap between packing, moving, and final disbursement.
For the broader program overview, see Crisp's guide to short sale relocation incentives (https://www.crispshortsales.com/the-short-sale-blog/relocation-incentives-short-sales).
The Approval Letter Controls the Payment
The approval letter is the first document to check.
It should answer several practical questions:
- Is relocation assistance approved?
- What amount is approved?
- Who receives the payment?
- Does the seller need to occupy the property through a certain date?
- Does the seller need to vacate by closing?
- Does the property need to be left in a certain condition?
- Is the payment allowed only if the sale closes by a specific deadline?
- Does the seller need to sign extra forms?
- Is the payment shown as an approved line item on the settlement statement?
If the approval letter is silent, vague, or says the seller cannot receive funds from closing, do not assume title can add relocation money at the end.
The safer move is to ask the servicer, investor contact, or short sale negotiator for written clarification before the file gets close to closing.
For a deeper checklist, see Crisp's guide on what the short sale relocation assistance approval letter (https://www.crispshortsales.com/the-short-sale-blog/short-sale-relocation-assistance-approval-letter) must say.
The Settlement Statement Has to Match
Even when the approval letter allows relocation assistance, the closing documents still need to match.
The settlement statement should show the approved payment in the right amount, to the right person, and in a way that does not violate the lender's written terms. If the settlement statement is missing the payment, lists the wrong amount, or shows a different payee, someone needs to stop and get it corrected before closing.
This is not just paperwork neatness.
The lender approved a deal based on specific numbers. If the final settlement statement changes the lender's net proceeds, adds unapproved seller funds, or shifts costs in a way the approval does not allow, the servicer may need to review the file again.
That can matter when the approval deadline is already tight.
Who Actually Pays the Seller?
In many short sales, the relocation payment is handled through the closing agent, title company, escrow company, or closing attorney after the file closes and funds.
The exact method may vary. The seller may receive a check, wire, or other approved disbursement method depending on local practice and closing instructions.
Agents should ask title or the closing attorney:
- How will the seller receive the relocation funds?
- Will the funds be available at signing, after funding, or after recording?
- Does the seller need to bring identification or complete extra forms?
- Can the seller receive a wire, or will a check be issued?
- Are there state or escrow rules that affect timing?
- Will the payment be delayed if closing funds arrive late?
The seller should know the practical answer before they schedule movers around money they do not yet have.
Closing Day Is Not Always the Same as Payment Day
Some sellers assume that if they sign closing papers in the morning, relocation money is available immediately.
Sometimes it is. Sometimes it is not.
Depending on the state, closing process, buyer funding, lender instructions, recording process, wire timing, and title procedures, there may be a gap between signing documents and receiving funds.
That gap may be short, but it still matters when a seller is trying to pay movers, pick up keys for a rental, or leave the home by a deadline.
The best question is not just, "Is the money approved?"
The better question is:
"When can the seller actually access the funds?"
That is the answer the seller needs for real-world moving plans.
What Can Delay the Relocation Payment?
Relocation assistance can be delayed or put at risk when the closing file changes.
Common problems include:
- The approval letter does not clearly approve relocation assistance.
- The settlement statement does not show the payment correctly.
- The buyer cannot close before the approval deadline.
- The closing date changes without written lender approval.
- The seller moved out too early when occupancy was required.
- The seller did not vacate by the required date.
- The property condition changed before closing.
- HOA, tax, lien, or payoff numbers changed the lender's net.
- Title needs a revised settlement statement.
- The servicer asks for updated documents before funding.
- The payment conflicts with a seller contribution or no-proceeds condition.
None of these issues automatically means the seller will lose the money. But each one should be handled in writing before the closing team assumes the payment is safe.
If the buyer delay is the issue, see Crisp's guide on how a buyer delay can put short sale relocation assistance at risk (https://www.crispshortsales.com/the-short-sale-blog/short-sale-relocation-assistance-buyer-delay).
Watch the Net Sheet Before Closing
The relocation payment is part of the closing math.
That means changes to payoff numbers, HOA balances, junior lien demands, taxes, transfer fees, title charges, buyer credits, repair credits, or closing costs can affect whether the final settlement statement still matches the short sale approval.
If the lender's net drops below what was approved, the servicer may ask for a revised statement, updated approval, or explanation.
That is why agents should not wait until signing to compare the final numbers. If the relocation payment is important, the final settlement statement should be checked before closing day.
For related guidance, see Crisp's article on why a short sale net sheet change can trigger bank re-review (https://www.crispshortsales.com/the-short-sale-blog/short-sale-net-sheet-changed-bank-re-review).
What Agents Should Confirm Before the Seller Counts on the Money
Before telling the seller the relocation payment is ready, agents should confirm:
- The approval letter allows the payment.
- The amount matches the settlement statement.
- The seller is the approved payee.
- The seller still meets occupancy and move-out conditions.
- The closing date is inside the approval deadline.
- Title has no unresolved payoff or lien issue that changes the numbers.
- The buyer is funded and ready to close.
- The seller knows when the funds will actually be available.
- Any extension or changed term has written servicer approval.
These checks protect the seller from planning around money that is still conditional.
They also protect the agent from giving the seller a promise the closing documents cannot support.
What If the Payment Is Missing From the Settlement Statement?
If relocation assistance is expected but missing from the settlement statement, do not brush it off.
Ask:
- Is the payment approved in writing?
- Did title receive the approval letter and closing instructions?
- Did the closing team know the payment needed to appear?
- Is the payment disallowed by the approval terms?
- Does the servicer need to approve a revised settlement statement?
- Will adding the payment reduce the lender's approved net?
If the payment is missing because of a clerical issue, it may be fixable. If it is missing because the lender never approved it, that is a much bigger problem.
Either way, the answer should be cleaned up before the seller signs final documents or gives possession based on an assumed payment.
How Crisp Helps Protect the Payment
Crisp Short Sales helps agents and sellers keep relocation assistance from becoming a last-minute surprise.
That can include reviewing the approval letter, checking whether the settlement statement matches the approved terms, watching closing deadlines, coordinating with title, flagging payment-condition issues, and helping the agent ask the right questions before the file is too close to closing.
The goal is not to casually promise relocation money.
The goal is to make sure the seller, agent, title company, and servicer are working from the same written terms before the closing window gets tight.
When a seller is relying on relocation assistance, clarity is kindness. It lets everyone plan the move around what the file can actually deliver.
Bottom Line
Short sale relocation assistance is usually paid at closing, through the closing process, only if the written approval terms and final settlement statement allow it.
The seller should not assume the money will arrive before closing, and the agent should not promise payment until the approval letter, closing statement, payee, amount, conditions, and funding timing are confirmed.
If relocation assistance is important to the seller's move, Crisp Short Sales can help (https://www.crispshortsales.com/how-we-help) review the file before a missing line item, changed closing date, or unresolved condition puts the payment at risk.
VA Short Sale Guidelines: Occupancy and Move-Out Timing
VA short sale seller moving soon? Check occupancy, move-out timing, approval terms, and vacant-property risks before the file stalls.
Moving out during a VA short sale can seem like the practical next step, especially when a seller already knows they cannot keep the home.
But timing matters.
If the seller moves too early, the property may become harder to show, inspect, value, secure, maintain, and close. If the seller waits too long, the buyer may worry about possession, the closing date may get tight, or a foreclosure deadline may keep moving. And if the approval letter includes move-out, occupancy, relocation, or closing conditions, the wrong timing can create a problem after the file already looks close.
Fast Answer
In a VA-backed short sale, agents should not assume the seller can move out whenever they want. The safer approach is to confirm the current occupancy status, keep the property accessible and protected, ask the servicer how a move may affect review, and match the seller's move-out plan to the written approval terms and closing deadline.
The seller should also understand that a VA short sale may affect future VA home loan benefit use, so the move-out decision should be coordinated with the servicer, VA, title, and the short sale negotiator before the file is too close to closing.
What To Do Next
- Confirm whether the property is owner-occupied, vacant, tenant-occupied, or partly occupied.
- Ask the servicer whether moving out changes any short sale review, inspection, access, insurance, or property-preservation requirements.
- Keep utilities, access, lockbox, showings, BPO/appraisal access, and maintenance under control.
- Review the approval letter before promising a move-out date, possession date, or relocation payment.
- Get short sale help before a move-out issue turns into a closing issue.
Why Move-Out Timing Matters In A VA Short Sale
VA's public guidance says that a short sale can be an alternative to foreclosure when the borrower owes more than the house is worth and the servicer agrees to accept the sale proceeds as payment of the debt owed.
That is the simple version.
The working version is more detailed.
A VA-backed short sale usually involves the servicer, the seller, the buyer, title, the listing agent, the buyer's lender, and sometimes VA guidance or VA loan technician involvement. The file may also have a foreclosure timeline, property value review, title problems, HOA balances, junior liens, buyer deadlines, and approval-letter conditions.
Occupancy sits in the middle of all of that.
If the seller is still living in the home, the file may be easier to access, maintain, and explain. If the seller has already moved out, the property may become a vacant-property file with different practical risks. If the seller needs to move before closing, the timing needs to be handled deliberately.
The mistake is treating move-out as a personal scheduling decision only. In a VA short sale, it can become a lender review, closing, possession, insurance, and property-condition issue.
First, Confirm The Current Occupancy Status
Before anyone talks about moving dates, confirm the property's current status.
Ask:
- Is the seller living in the home now?
- Has the seller already moved out?
- Is the property vacant?
- Is a tenant, family member, or other occupant living there?
- Are utilities still on?
- Is the property secured?
- Is there a lockbox or reliable access for showings and valuation?
- Has the servicer been told the correct occupancy status?
This sounds basic, but it matters. A file that is listed as owner-occupied but is actually vacant can create confusion. A file that appears vacant but still has personal property inside can create access and possession issues. A file with a tenant or family occupant can require a different move-out plan.
Agents should document the status in plain English and keep the short sale processor updated when it changes.
For a broader first-step checklist, see Crisp's guide on what agents must submit first in a VA short sale.
Do Not Move Out Just Because The Home Is Listed
Some sellers assume that once the home is listed as a short sale, they should leave.
That may be wrong.
Moving out too early can create problems such as:
- Missed BPO or appraisal access.
- Property-condition issues that develop unnoticed.
- Utility shutoff problems.
- Insurance questions.
- Vandalism or security concerns.
- Buyer inspection delays.
- Confusion about whether the property is abandoned.
- A harder time gathering final signatures or documents.
The seller may have a valid reason to leave early. Military relocation, job transfer, divorce, family safety, medical issues, or financial pressure can make staying impossible.
The key is not to hide that from the file. The key is to coordinate it.
If the seller needs to move, the agent or short sale negotiator should ask the servicer what must be maintained after move-out, how access should be handled, and whether the move changes any review condition.
Keep The Property Easy To Review
A VA-backed short sale still needs value review.
The servicer may need a BPO, appraisal, inspection, updated photos, repair evidence, or market support. If the property is hard to access, the value review can slow down or come back wrong.
That creates real risk.
If a BPO agent cannot get inside, they may rely on limited information. If the home is vacant and utilities are off, the buyer may raise repair or financing concerns. If the property condition changes after the value review, the servicer may need new information.
Agents should protect the review process by making sure:
- The lockbox works.
- Showing instructions are accurate.
- Utilities are addressed.
- The property is secure.
- Interior access is available when appropriate.
- Repair or condition issues are documented.
- The buyer and buyer's agent know how access will work.
This is not busywork. It helps protect the value, the buyer, and the timeline.
Match Move-Out Timing To The Approval Letter
The approval letter controls the short sale.
Before the seller commits to a move-out date, agents should review the approval terms carefully. The letter may include a closing deadline, seller contribution language, allowed closing costs, deficiency language, relocation or incentive language, possession expectations, or other conditions that affect the seller's next step.
Ask:
- Does the approval letter require closing by a specific date?
- Does it say anything about occupancy or possession?
- Does it mention relocation assistance, incentive funds, or seller proceeds?
- Does the settlement statement match the approved terms?
- Does the buyer expect possession at closing?
- Does title need anything from the seller before or after move-out?
- If the seller has already moved, does the servicer need updated information?
For a deeper approval-stage checklist, see Crisp's guide to VA short sale approval terms agents must check.
Be Careful With Relocation Or Move-Out Money
Move-out money should never be promised casually.
Some short sale files may involve relocation assistance or incentive language. Others will not. The answer can depend on the loan type, investor, servicer, approval terms, occupancy, closing documents, and whether the short sale actually closes.
In a VA-backed short sale, this should be handled with extra care. The seller should not move out because someone vaguely said there might be money available. The payment, payee, amount, timing, and conditions need to be in writing and need to match the settlement statement.
If the approval letter does not clearly allow the payment, do not assume it will be paid at closing.
If the seller is relying on money to move, raise the question early, not after the truck is scheduled.
What If The Seller Has Already Moved Out?
If the seller has already left, the file is not automatically lost.
But the agent should tighten control around the property.
Confirm:
- Who has keys?
- Is the home secure?
- Are utilities on or safely managed?
- Is the insurance situation understood by the seller?
- Can the BPO, appraisal, inspector, buyer, and contractors access the home?
- Is lawn care, snow removal, pool care, or exterior maintenance being handled?
- Is there personal property left behind?
- Is the buyer expecting the home empty before closing?
Vacant homes can become harder to close when nobody owns these details. A small maintenance problem can become a buyer issue. A missed access appointment can become a value delay. A property-condition change can become a revised review.
The seller may be gone, but the short sale still needs active management.
Sellers Should Also Understand The Future VA Benefit Question
VA's public guidance says a short sale may result in a loss or reduction in future VA home loan benefit use. VA also explains that if a VA-backed loan ends through foreclosure, short sale, or deed in lieu, the borrower may need to repay the amount VA lost on the loan to restore the future benefit.
Agents should not give legal, tax, credit, or VA-benefit advice.
But they should make sure the seller knows the question exists.
Before closing, the seller should ask the servicer, VA, and any appropriate adviser:
- Could this short sale affect future VA home loan benefit use?
- Is VA expected to pay a claim because of this short sale?
- What would restoration of entitlement require later?
- Does the approval letter say anything about debt, claim, deficiency, or future obligation?
For seller-first guidance, see Crisp's VA loan short sale seller checklist.
What Agents Should Say To Buyers
The buyer usually wants certainty.
They want to know when the seller will leave, when inspections can happen, whether utilities will be on, whether the property will be empty, and whether the deal can close by the approval deadline.
The agent should avoid promising more than the file can support.
A safe answer is:
"We are coordinating move-out timing with the seller, title, and short sale approval terms. We will confirm possession expectations once the approval letter and closing schedule are aligned."
That keeps the buyer informed without creating a promise that later conflicts with the servicer's conditions.
When The Timeline Is Already Tight
Move-out timing becomes more urgent when any of these are true:
- A foreclosure sale date is scheduled.
- The approval letter expires soon.
- The buyer's rate lock is expiring.
- The seller has military relocation or job-transfer pressure.
- The property is vacant.
- The buyer needs possession immediately at closing.
- A tenant or family member still occupies the property.
- Relocation assistance has been discussed but not approved in writing.
In those situations, someone needs to own the timeline.
That usually means the agent, short sale processor, title company, and negotiator should work from the same closing calendar. The seller's move-out date, buyer possession, approval expiration, title clearance, settlement statement, and servicer review cannot be treated as separate tracks.
If the file is close to a deadline, the safest move is to organize the facts and ask the servicer for direction early.
Bottom Line
A VA short sale is not only about getting the lender to accept less than the full payoff. It is also about keeping the property, seller, buyer, title, and approval terms aligned until closing.
Occupancy and move-out timing can affect access, valuation, condition, insurance, buyer confidence, possession, relocation money, and approval-letter compliance.
If the seller needs to move, coordinate it. If the property is vacant, manage it. If the approval letter has conditions, follow them. If future VA benefit questions exist, point the seller to the right official contacts and advisers.
The goal is simple: do not let a poorly timed move create a closing problem after the short sale finally gets close.
If a VA-backed short sale is already under pressure, start the short sale process with Crisp Short Sales before a move-out, access, or approval-deadline issue stalls the file.
Can an HOA Still Block a Short Sale After Bank Approval?
Bank approval is a major step in a short sale, but it is not always the final obstacle.
If the property is in a homeowners association or condo association, the HOA can still delay or block closing after the short sale lender approves the deal. The most common problems are unpaid dues, collection costs, expired estoppel letters, lien-release delays, transfer requirements, or payoff numbers that no longer match the lender's approved closing statement.
That does not mean every HOA file is in trouble. It means agents and sellers should not assume the deal is clear just because the bank approval letter arrived.
Fast Answer
Yes, an HOA can still create a closing problem after short sale approval if the HOA balance, payoff letter, lien release, estoppel, transfer approval, or collection attorney fees are not resolved before closing.
The safest move is to confirm the current HOA payoff, verify whether the HOA has recorded a lien, compare the final settlement statement against the short sale approval letter, and ask whether the servicer must re-review any changed numbers.
This is process guidance for agents and sellers, not legal advice. HOA rights, lien priority, foreclosure timing, collection fees, and release requirements can vary by state, association documents, and title findings. When legal rights or foreclosure deadlines are involved, sellers should speak with a qualified attorney.
Bank Approval Does Not Clear Every Closing Condition
Short sale approval usually means the mortgage servicer or investor has accepted less than the full loan payoff under specific terms.
Those terms may include:
- The approved sale price.
- The approved closing deadline.
- Allowed closing costs.
- Approved junior lien payments.
- Seller contribution terms, if any.
- Deficiency language.
- Relocation assistance terms, if any.
- The lender's expected net proceeds.
The approval letter does not automatically clear every non-mortgage issue attached to the property. Title still has to confirm whether there are taxes, judgments, municipal liens, second mortgages, HOA balances, or other claims that must be paid or released before closing.
That is why HOA issues can still matter even after the bank says yes.
How The HOA Can Still Stop Or Delay The File
An HOA usually does not approve the short sale in the same way the mortgage lender does. But the HOA can still affect whether title can insure the transfer and whether the buyer can close cleanly.
Here are the common problem points.
The HOA Payoff Changed
Short sales take time. During that time, monthly dues, late fees, interest, transfer fees, special assessments, and legal costs can continue to accrue.
If the HOA payoff used in the estimated settlement statement is outdated, the final numbers may be higher than expected. That can create a shortage at closing or reduce the mortgage lender's net proceeds.
For background on why this matters, see Crisp's guide to HOA dues in short sales: https://www.crispshortsales.com/the-short-sale-blog/2025/9/18/the-role-of-hoa-dues-in-short-sales-what-realtors-need-to-know.
The HOA Lien Has Not Been Released
If the HOA recorded a lien, title usually needs a payoff and release path before closing.
The lender may have approved the short sale, the buyer may be ready, and the seller may be packed. But if title cannot confirm how the HOA lien will be paid and released, the closing can stall.
This becomes especially risky when the approval letter has a short expiration window.
The Estoppel Letter Is Missing, Wrong, Or Expired
In many HOA and condo files, title relies on an estoppel letter or association payoff statement to confirm what is owed. If that statement is missing, incomplete, expired, or different from the prior numbers, the closing team may need an updated figure.
Agents should not treat the estoppel as a small administrative item. It can control the final amount owed and the timing of the release.
For a deeper breakdown, see Crisp's guide to the HOA estoppel letter in a short sale: https://www.crispshortsales.com/the-short-sale-blog/hoa-estoppel-letter-short-sale-closing.
Collection Fees Were Added Late
Some HOA balances are handled by a collection company or attorney. That can add legal fees, recording fees, payoff charges, and release fees.
The issue is not just whether those fees are fair. The practical issue is whether the short sale lender approved enough room for them on the settlement statement.
If the final settlement statement changes because HOA collection costs were added, the lender may need to review the numbers again. Crisp has a related guide on what to do when a short sale net sheet changes before closing: https://www.crispshortsales.com/the-short-sale-blog/short-sale-net-sheet-changed-bank-re-review.
The Association Has Transfer Or Resale Requirements
Some associations require transfer documents, resale packages, buyer applications, move-in rules, transfer fees, or association approval steps before closing.
These requirements may not be negotiable at the last minute. If nobody orders the documents early, the file can lose days when it has no days to spare.
This is one reason agents should involve title early and ask about HOA requirements before treating the bank approval letter as the finish line.
Why The Short Sale Lender May Care
The short sale lender approved the deal based on a set of numbers.
If HOA payoff, lien, fee, or transfer charges change those numbers, the lender may ask for a revised settlement statement. In some cases, the lender may approve the update quickly. In others, the file may go back into review, especially if the lender's net proceeds drop or an unapproved payoff appears.
The key question is simple:
Does the final settlement statement still match the written approval terms?
If the answer is no, the agent, title company, and short sale negotiator should slow down long enough to get the right written answer before closing.
For related closing checks, see Crisp's guide on what title must confirm in a short sale approval letter before closing: https://www.crispshortsales.com/the-short-sale-blog/short-sale-approval-letter-before-closing-title-confirm.
What Agents Should Check Before Assuming The File Can Close
Before telling the seller, buyer, and buyer's agent that the file is clear, ask these questions:
- Has title ordered the current HOA payoff or estoppel?
- Does the payoff include dues, late fees, legal fees, special assessments, transfer fees, and release fees?
- Has the HOA recorded a lien?
- If there is a lien, who is preparing and recording the release?
- Does the payoff expire before the scheduled closing date?
- Are any transfer, resale, buyer-application, or association-approval steps required?
- Does the final settlement statement match the lender's approval letter?
- If the numbers changed, does the servicer need written re-approval?
- Is the closing still inside the short sale approval deadline?
These questions are basic, but they catch the issues that often surface too late.
When This Becomes Urgent
HOA problems are most dangerous when another deadline is already running.
That may include:
- A short sale approval letter that expires soon.
- A buyer rate-lock deadline.
- A scheduled foreclosure sale date.
- A move-out or relocation-assistance deadline.
- A buyer who is already frustrated with the delay.
- An HOA collection or lien issue that is still growing.
In those situations, the file needs a clear owner. Someone has to confirm the HOA payoff, title requirement, lender approval terms, and closing deadline instead of assuming another party has handled it.
How Crisp Helps With HOA Problems In Short Sales
Crisp Short Sales helps agents and sellers organize short sale assistance when HOA, title, payoff, and lender approval issues overlap.
That can include reviewing approval-letter conditions, coordinating with title, checking whether the settlement statement still matches the servicer's terms, helping identify the right lender review lane, and keeping the file moving when late payoff or release issues threaten closing.
The goal is not just to get the bank approval letter. The goal is to get the file closed under terms the lender, title company, buyer, seller, and association can actually complete.
Bottom Line
An HOA does not need to be the short sale lender to create a serious closing problem.
If the HOA payoff, lien release, estoppel, collection fees, or transfer requirements are unresolved, the short sale can still stall after bank approval. Agents should verify those items before closing, compare the final settlement statement to the approval letter, and get written lender direction if anything material changes.
If an HOA issue is threatening an approved short sale, Crisp Short Sales can help: https://www.crispshortsales.com/how-we-help agents and sellers get the file organized before the closing window slips away.

Buyer Won't Raise? How to Negotiate a Short Sale
The bank countered. The buyer will not raise the offer. The seller cannot bring money to closing. Now the agent has to figure out whether the short sale can still be saved.
This is one of the most frustrating moments in a short sale because everyone may be acting rationally. The buyer may already be at their limit. The seller may truly have a hardship. The lender may be reacting to value, investor rules, net proceeds, mortgage insurance, or closing-cost limits.
The next move should not be another vague status request.
It should be a clean short sale negotiation response that explains why the current offer still makes sense, what changed, what evidence supports the number, and whether there is another way to improve the bank's net without forcing the buyer above their ceiling.
This guide is practical short sale process guidance for agents and sellers. It is not legal advice. Short sale approval terms, foreclosure timing, deficiency language, and seller contribution questions can vary by loan, investor, servicer, and state. Sellers should speak with a qualified attorney, tax professional, or housing counselor when legal, tax, or foreclosure rights are involved.
Why The Buyer Refusal Changes The Strategy
When a buyer can raise the offer, the negotiation is simpler. The agent can compare the counter to the buyer's limit, ask for a revised offer, and see whether the new number still works.
When the buyer refuses to raise, the strategy changes.
Now the file has to prove one of three things:
- The lender's value expectation is too high.
- The lender's required net can be improved without raising the price.
- The current offer is the best real offer the property is likely to produce.
That requires evidence. It also requires a clean explanation. Short sale negotiators lose time when they send emotional arguments, scattered attachments, or general statements like "the buyer will walk."
The bank needs to know why the counter does not work and what should happen instead.
First Confirm The Buyer's Real Ceiling
Before pushing back on the bank, confirm the buyer's position clearly.
The agent should know:
- Is the buyer refusing because they cannot qualify for more?
- Is the buyer refusing because the property condition does not justify more?
- Is the buyer refusing because repair costs are too high?
- Is the buyer refusing because the appraisal came in low?
- Is the buyer refusing because another property is available?
- Is the buyer willing to adjust terms even if they will not raise price?
Those answers matter.
A buyer who cannot qualify for more may still be strong if financing is clean and closing can happen quickly. A buyer who simply does not want to raise may need more market support. A buyer who is near walking away may require a faster, sharper negotiation response.
The short sale coordinator should not guess. Get the buyer's position in writing through the proper contract or addendum process before sending a lender response.
Check What The Bank Is Really Countering
A bank counter does not always mean the lender wants a higher purchase price just because it prefers more money.
The counter may be driven by:
- A BPO or appraisal value.
- Investor minimum net proceeds.
- Mortgage insurance requirements.
- Approved closing-cost limits.
- Commission or fee limits.
- Junior lien payoff demands.
- Tax, HOA, or municipal balances.
- Seller contribution expectations.
- Buyer credit or repair credit issues.
- A settlement statement that no longer matches the offer.
If the team does not know what caused the counter, it may argue the wrong issue.
For example, if the problem is a high BPO, the file needs value evidence. If the problem is net proceeds, the file may need a revised settlement statement. If the problem is mortgage insurance, the response may need to address seller contribution or deficiency language. If the problem is a junior lien, the first lender may need to approve how proceeds are allocated.
The right first question is:
What specific review item caused the counteroffer?
Build The Response Around Evidence
When the buyer will not raise, the response should make the current offer look like the most credible path to closing.
Strong support may include:
- Comparable sales that support the buyer's offer.
- Active listings that show market competition.
- Pending sales, if available and reliable.
- Days on market.
- Prior price reductions.
- Showing feedback.
- Inspection findings.
- Repair estimates.
- Property-condition photos.
- Appraisal issues, if the buyer's lender has a value problem.
- Contractor bids for major defects.
- Local market notes from the listing agent.
- Proof that the buyer is ready and qualified at the current number.
The response should not bury the reviewer in noise. It should lead with the core reason the counter is too high, then attach the few documents that prove it.
For files where value is the problem, Crisp's BPO rebuttal package guide is the better supporting resource.
Improve The Net Without Hiding The Problem
Sometimes the buyer will not raise price, but the net sheet can still be improved.
That does not mean hiding costs or pressuring the seller into an unsafe promise. It means reviewing the numbers honestly to see whether the settlement statement is clean.
The short sale processor should check:
- Are taxes, HOA dues, and payoffs current?
- Are duplicate fees showing?
- Are stale payoff numbers overstating costs?
- Are buyer credits clearly allowed and necessary?
- Are title fees accurate?
- Are commission numbers correct?
- Is the junior lien demand realistic and documented?
- Is the closing date creating avoidable per-diem interest?
- Is every cost shown in the correct place?
If the net sheet has errors, fix the errors. If costs increased, explain why. If a credit is necessary to keep the buyer, show how it affects the lender's recovery.
For related closing-number issues, see Crisp's guide on what to do when the short sale net sheet changed and the bank may re-review.
Consider Terms Other Than Price
If the buyer will not raise, they may still be able to strengthen the deal.
Depending on the transaction, the buyer may be able to:
- Shorten the inspection period.
- Confirm financing milestones.
- Increase earnest money if appropriate.
- Remove unclear contingencies.
- Provide updated proof of funds.
- Confirm they will accept the property condition.
- Sign a clean extension.
- Move faster once approval is issued.
Those terms do not replace the lender's need for acceptable net proceeds, but they can reduce closing risk.
That matters because a lower offer from a buyer who will actually close may be more valuable than chasing a higher number that is not real.
Watch For Buyer Walk-Away Risk
When a bank counters and the buyer refuses, the file can become fragile quickly.
The buyer may start looking at other homes. Their rate lock may expire. Their lender may need updated documents. Their patience may run out. If the property needs repairs, the buyer may decide the counter confirms the deal is no longer worth it.
The listing agent should keep the buyer side informed without overpromising.
Useful updates include:
- What the bank countered.
- What evidence is being sent back.
- What response date is expected.
- Whether the buyer needs to sign an extension.
- Whether title or financing deadlines need attention.
For buyer-side risk, link this article to Crisp's guide on whether a buyer can back out of a short sale.
What A Short Sale Negotiator Should Send
A strong short sale negotiation response should be organized enough for the servicer to review quickly.
The response should include:
- The lender's counter amount.
- The buyer's current offer amount.
- A clear statement that the buyer will not increase.
- The reason the buyer will not increase.
- Evidence supporting the current offer.
- Updated settlement statement or net sheet.
- Repair or condition support, if relevant.
- Buyer proof showing the current offer can close.
- Any deadline that affects the file.
- The exact request: accept the current offer, revise the counter, or allow a value dispute.
The best short sale help is specific. It does not ask the lender to "please reconsider" without showing why.
When To Hold, Counter, Or Replace The Buyer
Not every buyer refusal should be treated the same.
The team may decide to hold the buyer's number if the evidence strongly supports the offer and the buyer is still committed.
The team may try a smaller counter if the buyer has some flexibility, the lender's number is close, and the deal can still close safely.
The team may need to replace the buyer if the lender's value is defensible, the buyer is too low, or the buyer will not wait long enough for the review.
That decision should be made with the seller's interests in mind. The seller may also need legal or housing-counselor guidance if foreclosure timing, deficiency exposure, or contribution demands are involved.
What Agents Should Not Say
Agents should avoid statements that create risk or weaken the file.
Do not say:
- "The bank has to take this offer."
- "The buyer will definitely walk."
- "The seller can just pay the difference."
- "The approval is guaranteed if we send comps."
- "The foreclosure will stop because we are negotiating."
- "The buyer credit does not matter."
- "The seller will get relocation money no matter what."
Short sale negotiation works best when the file is factual, organized, and documented.
The Bottom Line
When the bank counters and the buyer will not raise, the short sale is not automatically dead.
But the next response has to be precise.
Find out what caused the counter. Confirm the buyer's real ceiling. Clean up the net sheet. Support the current offer with comparable sales, condition evidence, repair proof, buyer strength, and market context. Then ask the servicer for a specific answer.
A short sale negotiator cannot force the bank to approve a low offer. But a good negotiator can make the lender review the right evidence, understand the real closing risk, and see why the current buyer may still be the best path.
If the buyer will not raise and the file needs a cleaner lender response, Crisp can help agents organize the short sale package, explain the counteroffer problem, and keep the negotiation moving.
Changed Terms After Short Sale Approval: What Must Go Back to the Bank
Short sale terms changed after approval? See which buyer, price, date, credit, lien, or settlement changes need bank re-review.
Why Changed Terms Matter After Approval
A short sale approval letter can feel like the hard part is over.
The seller finally has an answer. The buyer is ready. The agents want to close. Title is pushing for final numbers. Everyone has waited long enough.
But short sale approval is not a blank approval for any version of the deal.
It is approval of a specific transaction under specific terms. The approval letter may name the buyer, sale price, required net proceeds, closing deadline, allowed closing costs, commission, relocation assistance, seller contribution, junior lien payments, and final settlement-statement conditions.
If those terms change, the bank may need to review the file again before closing.
That does not always mean the short sale is in trouble. Many changes can be handled. The problem is when the team treats a changed deal like it is still the same approved deal.
For a deeper look at approval-letter conditions, see Crisp's guide to short sale approval letter clauses that can delay closing.
Changes That Usually Need Bank Review
Some changes are too important to handle casually.
The short sale team should assume the bank may need to review the file again when any of these items change:
- Purchase price.
- Buyer name or buyer entity.
- Closing date or approval expiration date.
- Seller credit, buyer credit, repair credit, or concession.
- Commission or transaction fee.
- First-lien payoff figures.
- Junior lien payoff or settlement terms.
- HOA, tax, municipal, judgment, or title payoff numbers.
- Relocation assistance or incentive payment.
- Seller contribution or promissory-note requirement.
- Occupancy or move-out condition.
- Final settlement statement or closing disclosure.
- Arm's-length affidavit, resale restriction, or investor-specific condition.
The practical question is not whether the change seems small.
The practical question is whether the change affects the terms the bank approved.
Buyer Changes Are Not Just Paperwork
A buyer change can be a major short sale issue.
The bank may have approved a specific buyer, proof of funds, financing type, closing timeline, and contract structure. If the original buyer assigns the contract, changes entities, adds or removes a buyer, switches financing, or is replaced by a new buyer, the servicer may need to approve the changed buyer before closing.
Agents should be especially careful when the buyer is an investor, trust, LLC, related party, employer-relocation program, or any structure that could raise arm's-length or resale concerns.
The file may still be approvable. But the buyer change should be disclosed and handled in writing.
Price Changes Can Restart the Math
If the purchase price changes after approval, the short sale math changes.
A higher price may improve the bank's net, but the file still needs to match the written approval and settlement statement. A lower price is more sensitive because it can reduce the bank's expected recovery and may require investor, mortgage insurer, or servicer approval.
Price changes should be supported by the correct addendum and a revised settlement statement. If the price changed because of inspection issues, repair conditions, appraisal problems, or buyer financing, the short sale negotiator should explain the reason clearly instead of sending a vague update.
For related closing-number issues, review Crisp's article on what happens when a short sale net sheet changed and the bank may re-review.
Closing Date Changes Can Create Approval Problems
Short sale approval letters usually include a closing deadline.
If the buyer's loan is delayed, title is not clear, payoff figures are stale, HOA documents are late, or signatures are not ready, the team may need an extension before the approval expires.
Do not wait until the final day.
The approval letter may require closing, funding, recording, or settlement by a specific date. Moving the closing date can also change payoff interest, taxes, HOA dues, prorations, and final net proceeds.
That means a date change can become a number change.
If the closing date moves, the short sale coordinator should check both the approval deadline and the updated settlement statement before telling everyone the file is still clear to close.
Credits and Concessions Need Careful Review
Buyer credits, seller credits, inspection credits, repair credits, and closing-cost concessions can be normal in regular real estate transactions.
In a short sale, they can be approval issues.
The seller usually cannot agree to give away money that changes the lender's recovery unless the short sale lender accepts that structure. A credit that looks harmless to the buyer and seller may reduce the bank's net or violate the approval terms.
Before adding or changing a credit, ask:
- Is the credit allowed in the approval letter?
- Does it reduce the lender's net?
- Is it shown correctly on the settlement statement?
- Does it require a revised addendum?
- Does the buyer's lender also approve it?
- Does the servicer need written approval before closing?
If the answer is unclear, slow down and get written direction.
Lien and Title Changes Can Stop the Closing
Title issues often appear late because short sales take time.
A second mortgage payoff can change. A judgment can appear. HOA fees can grow. Taxes can update. Municipal balances can surface. A prior mortgage release can be missing. Probate, divorce, bankruptcy, or ownership issues can complicate signing authority.
Those items can affect whether the approval still works.
If a junior lienholder demands more money than the approval allows, the first lender may need to approve the revised allocation. If an HOA or municipal lien must be paid from closing proceeds, the settlement statement may need to change. If the title company cannot insure the transaction under the approved terms, the file is not truly ready.
This is why title review should happen early and then again before closing. Crisp has a related guide on what title must confirm before short sale closing.
How to Send the Change Back Correctly
When changed terms need bank review, the update should be specific.
Do not send a bundle of revised documents with no explanation.
A clean update should include:
- What changed.
- Why it changed.
- Whether the purchase price changed.
- Whether the buyer changed.
- Whether the closing date changed.
- Whether the bank's expected net changed.
- Which settlement-statement lines changed.
- Which approval-letter condition is affected.
- What written approval, extension, or clarification is being requested.
The goal is to make the reviewer answer the right question quickly.
If the bank only needs to approve an extension, ask for the extension. If the bank needs to approve a lower net, explain the lower net. If a lien payoff changed, show the prior number, new number, and reason.
Specific changes get cleaner answers.
What Agents Should Not Do
The biggest mistake is assuming the bank will accept the final closing package because the short sale was already approved.
Agents should avoid:
- Letting title close with numbers that do not match the approval letter.
- Promising a buyer credit before lender approval.
- Changing the buyer entity without disclosure.
- Waiting until the approval expires to ask for an extension.
- Treating a new lien payoff as a title-only issue.
- Assuming relocation assistance is safe if the approval language changed.
- Sending revised terms without explaining the impact on the bank's net.
Short sales need momentum, but momentum without written approval can create a closing failure.
The Bottom Line
After short sale approval, every meaningful change should be checked against the approval letter.
If the changed term affects the buyer, price, closing date, settlement statement, payoff, lien release, credit, seller money, relocation assistance, or approval condition, get the short sale processor or negotiator involved before closing.
The file may not need a full restart. It may only need a corrected approval, extension, revised settlement statement, or written clarification.
But that answer needs to come from the right place.
If the transaction changed after approval, the safest question is:
Does the written short sale approval still match the deal we are about to close?
If not, Crisp can help agents organize the changed terms, explain the issue to the servicer, and keep the file moving toward a closing that actually matches the approval.
Frequently Asked Questions
What changes after short sale approval need bank review?
Buyer, price, closing date, seller credit, lien payoff, relocation, seller contribution, and settlement-statement changes may need written bank review before closing.
Can a short sale close if the terms changed after approval?
It can sometimes close, but the team should confirm in writing that the lender accepts the changed terms before signing or funding.
Does a changed closing date need a new short sale approval letter?
It may require a written extension or revised approval if the original approval letter has a deadline that the new closing date will miss.
This article is general information, not legal advice. Short sale approval terms, foreclosure timelines, deficiency language, and closing requirements can vary by loan, investor, servicer, and state. Sellers should speak with a qualified attorney or housing counselor when legal rights or foreclosure deadlines are involved.

Short Sale Net Sheet Changed? Why the Bank May Re-Review
Short sale net sheet changed before closing? See why taxes, HOA, liens, credits, or payoff updates can trigger bank re-review.
In a normal sale, a changed closing number may be a quick update between the agents, lender, and title company.
In a short sale, it can be a bigger deal.
The short sale lender is not only reviewing the sales price. The lender is reviewing what it expects to receive after approved closing costs, taxes, HOA balances, junior liens, commissions, concessions, payoff changes, and title expenses. If those numbers change, the lender may need to re-check the file before issuing approval or allowing closing to move forward.
That is why a short sale can feel ready and then suddenly get quiet again.
This guide is practical short sale process guidance for agents and sellers. It is not legal advice. If foreclosure notices, deficiency language, seller liability, or legal deadlines are involved, the seller should speak with a qualified attorney or housing counselor.
Why The Net Sheet Matters In A Short Sale
The net sheet, sometimes called an estimated settlement statement, shows how the sale money is expected to move at closing.
For the short sale lender, the key question is simple:
After allowed costs and payoffs, how much money does the lender receive?
That expected amount can affect whether the servicer, investor, mortgage insurer, or junior lienholder accepts the short payoff. A buyer can offer the same purchase price, but the lender's expected recovery can still change if the settlement statement changes.
That is why agents should treat the net sheet as part of the short sale approval package, not as a harmless closing worksheet.
For a broader view of file delays, see Crisp's guide on why short sale approval can take longer.
What Changes Can Trigger A Bank Re-Review
A short sale can go back to review when the new numbers change what the lender expected to receive or what the lender previously approved.
Common triggers include:
- Property taxes updating before closing.
- HOA dues, estoppel fees, collection costs, or transfer fees changing.
- A junior lien payoff coming in higher than expected.
- A municipal lien, utility balance, judgment, or title issue appearing late.
- Buyer credits or repair credits reducing the lender's net.
- Closing costs increasing.
- Commission, transaction, or administrative fees changing.
- Payoff interest increasing because the closing date moved.
- The buyer, loan type, closing date, or purchase price changing.
- The final settlement statement not matching the approval letter.
Not every change kills a short sale. But the team should not assume the lender will accept a lower net without written confirmation.
Taxes, HOA Balances, And Municipal Charges Can Move Late
Property taxes and HOA amounts often change because the file takes time.
A tax prorate may update. An HOA estoppel may show new dues, late fees, legal fees, transfer fees, or collection costs. A city or utility balance may appear after title review. Even if each item seems small by itself, together they can reduce the lender's net proceeds.
That matters because the lender may have approved one version of the math and then receive a different version before closing.
If HOA numbers are involved, agents should also review Crisp's guide on the HOA estoppel letter in a short sale. HOA balances can be especially sensitive because the association, title company, buyer, seller, and lender may all be looking at the same charge from different angles.
Junior Liens And Payoff Changes Can Break The Math
Junior liens create another common net-sheet problem.
A second mortgage, judgment lien, tax lien, HOA lien, or other payoff may demand more than the first lender expected to allow. If the first lender approved only a limited payment to a junior lienholder, a higher demand can create a gap.
The agent should not try to smooth over that gap verbally.
The short sale processor or negotiator should confirm:
- What each lienholder is demanding.
- What the first lender previously approved.
- Whether the junior lienholder will accept the approved amount.
- Whether the settlement statement matches the written approval terms.
- Whether the first lender must approve a revised payoff allocation.
This is where short sale assistance can prevent late-stage confusion. The issue is not only whether the lien exists. The issue is whether every payoff can close inside the lender's approved numbers.
Buyer Credits And Repair Credits Can Lower The Lender's Net
Buyer credits can be normal in real estate, but they are not automatically harmless in a short sale.
If the buyer asks for a closing cost credit, repair credit, inspection credit, seller concession, or price adjustment, the lender may treat that as a change to the deal. Even if the seller agrees, the seller may not have authority to give away money that affects the lender's recovery.
The right question is not only:
Will the buyer accept this?
The better short sale question is:
Will the lender approve this and still receive the required net?
If a credit appears after short sale approval, title and the agents should compare the new settlement statement against the approval letter before closing. Crisp has a related guide on what title must confirm before short sale closing.
Closing Date Changes Can Create Payoff Problems
Short sale files often run close to deadlines.
When the closing date moves, several numbers can change at once. Payoff interest may increase. Tax prorations may shift. HOA dues may roll into a new month. Buyer financing costs may change. The approval letter may also have a closing deadline that cannot be ignored.
A small extension can therefore become more than a calendar issue.
Before assuming the short sale is still approved, the team should check:
- Does the approval letter allow the new closing date?
- Do payoff figures remain valid?
- Did taxes, HOA, or other prorations change?
- Does the lender need an updated settlement statement?
- Does the buyer still qualify and remain ready to close?
If the answer is unclear, the short sale coordinator should ask for written confirmation before the file reaches signing.
How To Explain The Change To The Lender
When a net sheet changes, the update should be organized and specific.
Do not send a vague note that says, "See revised settlement statement."
A better note explains what changed and why it matters:
- The prior estimated net.
- The revised estimated net.
- The exact line items that changed.
- The reason for each change.
- Whether the purchase price changed.
- Whether buyer credits or seller concessions changed.
- Whether any lien, tax, HOA, payoff, or title item caused the change.
- Whether the file still meets the lender's required net.
- Whether closing is inside the approval deadline.
This helps the negotiator, servicer, investor, or mortgage insurer review the actual issue instead of reopening the entire file blindly.
What A Short Sale Processor Should Check Before Resubmitting
Before resubmitting a changed net sheet, a short sale processor should make sure the file is clean.
The checklist should include:
- Current purchase contract and addenda.
- Updated estimated settlement statement.
- Current first-lien payoff.
- Junior lien payoff demands.
- HOA estoppel or payoff.
- Tax, utility, municipal, or title charges.
- Buyer proof or loan approval if the buyer timeline changed.
- Approval-letter conditions if approval was already issued.
- Foreclosure, auction, or sale-date deadline if one exists.
The goal is not to send more documents than necessary. The goal is to send the right documents so the lender can approve the changed math without creating another delay.
When The Change Is Probably Small
Some changes are easier to handle.
A minor tax prorate update, a small recording-fee adjustment, or a closing-cost correction may be acceptable if the lender's net remains the same or improves. Even then, title should document the change and confirm whether lender approval is needed.
If the lender receives more than expected, the issue may be simple.
If the lender receives less than expected, the issue deserves more caution.
When The Change Is A Bigger Risk
A changed net sheet becomes more serious when it reduces the lender's net, changes the buyer's credit, adds an unapproved payoff, alters commission or fees, changes the buyer or price, or moves closing beyond the approval deadline.
Those are the moments where the file can go back to:
- Servicer review.
- Investor review.
- Mortgage insurance review.
- Junior lien review.
- Title or closing review.
That re-review can be frustrating, but ignoring it is worse. If the final settlement statement does not match the written approval, the closing package may be rejected or the closing may need to be paused.
Where Crisp Short Sales Helps
Crisp Short Sales helps agents organize short sale processing, lender follow-up, settlement-statement review, approval-letter conditions, payoff issues, HOA balances, lien questions, and closing deadlines.
The changed-net-sheet stage is where details matter.
The buyer may still be ready. The seller may still want the sale. The contract may still be intact. But if the bank's expected net proceeds changed, the file needs a clear explanation and written lender direction before closing.
If the short sale net sheet changed, start with one practical question:
Did the lender's expected net go down, and if so, has that change been approved in writing?
Crisp can help agents get that answer, organize the revised numbers, and keep the file moving toward a clean approval.
Frequently Asked Questions
Why would a bank re-review a short sale net sheet?
A bank may re-review the net sheet if taxes, HOA balances, junior liens, buyer credits, closing costs, payoffs, or closing dates change the lender's expected net proceeds.
Does the short sale price matter more than the net sheet?
No. The price matters, but the lender also reviews the net amount it expects to receive after approved costs, liens, and payoffs.
Can a buyer credit delay short sale approval?
Yes. A buyer credit can reduce the lender's net and may need written lender approval before closing.
What should an agent do when the settlement statement changes?
Compare the new statement to the prior net sheet and approval terms, identify the exact changes, and ask the short sale lender whether written re-approval is required.
Short Sale Slow After BPO? What Comes Next
BPO done but short sale approval still pending? See what review steps can delay the bank and what agents should ask next.
The BPO is done. The buyer is still waiting. The seller is asking for updates. And the bank still has not issued the short sale approval letter.
That is a common short sale pressure point.
A completed BPO can feel like the finish line because everyone knows the lender needed a value. But in most short sales, the BPO is only one checkpoint. The file may still need value review, investor approval, mortgage insurance review, updated seller documents, title clearance, payoff review, or final approval-letter conditions.
That is why a short sale can still take longer after the BPO, even when the file looks active.
This guide is practical short sale process guidance for agents and sellers. It is not legal advice. If foreclosure notices, deficiency language, or legal rights are involved, the seller should speak with a qualified attorney or housing counselor.
The BPO Is A Value Check, Not Final Approval
A BPO, or broker price opinion, helps the lender estimate the property's market value. The lender may use it to decide whether the buyer's offer is reasonable, whether the investor's expected net proceeds are being met, and whether the file needs a counteroffer or value dispute.
But the BPO does not clear every other review lane.
The lender may still need to answer several questions:
- Does the BPO support the offer?
- Does the investor accept the loss?
- Does mortgage insurance have to approve the terms?
- Are seller documents still current?
- Does title show liens, HOA balances, judgments, or payoff issues?
- Does the buyer still qualify and agree to wait?
- Does the estimated settlement statement match what the lender will approve?
If one of those items is unresolved, the file can stay pending even after the BPO is complete.
For a broader look at delay points, see Crisp's guide on why short sale approval can take longer.
What Should Happen After The BPO
After the BPO is complete, the agent or short sale processor should not simply ask, "Any update?"
The better question is:
Was the BPO reviewed and accepted, and what review stage owns the file now?
That one question separates several different problems.
If the BPO has not been reviewed, the file may still be waiting in valuation. If the BPO was reviewed but came in high, the lender may be preparing a counteroffer. If the value was accepted, the file may have moved to investor, mortgage insurance, title, or closing review.
Each answer requires a different next move.
Delay 1: The Bank Value Is Higher Than The Offer
The most obvious post-BPO delay happens when the bank value comes in higher than the buyer's offer.
That does not always mean the short sale is dead. But it does mean the lender may pause the file, counter the buyer, or ask for more support before approving a lower payoff.
Agents should ask:
- Did the lender receive the BPO?
- Has the BPO been reviewed?
- Was the value accepted?
- Is the lender preparing a counteroffer?
- Can the agent submit a value dispute or rebuttal?
If the value appears wrong, the response should be organized. A good rebuttal usually includes comparable sales, property condition evidence, repair estimates, listing history, buyer feedback, and photos that explain why the offer is realistic.
For more on value disputes, see Crisp's BPO rebuttal package guide.
Delay 2: The Investor Still Has To Approve The Loss
The servicer is not always the final decision-maker.
In many short sales, the servicer collects documents and communicates with the agent, but the loan investor still has to approve the loss. That investor may have separate rules for net proceeds, seller contributions, closing costs, deficiency language, buyer terms, relocation assistance, or approval timing.
This creates a common misunderstanding.
The agent hears that the file passed valuation and assumes approval should be next. The servicer may be done with one part of the review, but the investor decision may still be pending.
The agent should ask:
- Has the file been submitted to the investor?
- What date was it submitted?
- What investor condition is open?
- Is the investor waiting on value, documents, title, or net sheet changes?
- When is the next investor review date?
This is where short sale negotiation becomes more than checking a portal. The team needs to know who owns the next decision.
Delay 3: Mortgage Insurance Adds Another Review Layer
Some loans have mortgage insurance. When they do, the mortgage insurer may need to approve the short sale terms before the file can move forward.
That can make the process feel slow after the BPO because the value question may be mostly resolved, but the insurer still has to review the loss.
Mortgage insurance review can affect:
- Seller contribution requests.
- Promissory note requests.
- Deficiency waiver language.
- Closing cost approvals.
- Relocation assistance.
- Final approval timing.
If mortgage insurance is involved, the agent should ask whether the file has been sent to the insurer, what condition is open, and whether the insurer is requesting any seller or buyer-side change.
Delay 4: The Net Sheet No Longer Works
A short sale approval is not based only on the sales price.
The lender also reviews what it expects to receive after closing costs, taxes, HOA balances, junior liens, commissions, concessions, and other approved expenses. If those numbers change after the BPO, the file may need another review.
This can happen when:
- Property taxes update.
- HOA balances increase.
- A junior lien demands more money.
- Closing costs are higher than expected.
- Buyer credits or repair credits appear.
- Payoff figures expire.
- The closing date moves.
The agent should confirm whether the current settlement statement still matches the lender's expected net. If the numbers changed, the file may not be delayed by the BPO at all. It may be delayed because the deal no longer fits the approval math.
Delay 5: Seller Documents Aged While The File Was Waiting
Short sale documents can expire while everyone waits for value review.
Bank statements, pay stubs, profit and loss statements, hardship letters, financial worksheets, buyer proof, and estimated settlement statements may need updates before the file can move from valuation to final approval.
This is frustrating because the agent may feel like the package was already complete.
Both things can be true:
The file was complete when submitted, and some documents are now stale.
A short sale processor should track document age before the lender asks again. If the post-BPO review gets delayed, the team should check whether the lender will need updated financials, buyer proof, or closing figures before final approval.
Delay 6: Title Or Lien Issues Surface Late
Some post-BPO delays have nothing to do with the property value.
The file may be stuck because title found a second mortgage, HOA payoff, tax lien, judgment lien, probate issue, name issue, release problem, or payoff mismatch.
That matters because the lender may not issue final approval if the settlement statement cannot close cleanly.
Agents should keep title moving while valuation is underway. Waiting until after the BPO to check liens can waste the exact time the file needs most.
What Agents Should Ask After The BPO
After the BPO is complete, the follow-up should be specific.
Use questions like these:
- Was the BPO received?
- Has the lender reviewed and accepted the BPO value?
- Is the file in valuation review, investor review, mortgage insurance review, title review, or closing review?
- Is the lender preparing a counteroffer?
- Is a value dispute allowed?
- Are any seller documents now outdated?
- Does the current settlement statement meet the lender's required net?
- Are title, lien, payoff, or HOA items holding the file?
- What is the next review date?
- Who owns the next decision?
Those questions are stronger than another general status request because they force the file into a review lane.
For the role-by-role escalation path, see Crisp's guide on who agents should contact when a short sale is stuck.
When To Push For A BPO Rebuttal
A BPO rebuttal makes sense when the lender's value appears materially higher than market reality and the buyer's offer is still the best credible path.
The rebuttal should not be emotional. It should be evidence-based.
Helpful support may include:
- Lower comparable sales.
- Active competition.
- Days on market.
- Price reductions.
- Repair estimates.
- Property condition photos.
- Inspection issues.
- Buyer feedback.
- Local market context.
The goal is not to argue that the agent wants approval. The goal is to show why the current offer better reflects the property and market than the bank's value.
Crisp also has a related guide on BPO vs appraisal in a short sale for files where different value opinions are creating confusion.
When To Escalate After The BPO
Escalation is reasonable when the BPO is complete, the file has passed the promised review date, and the servicer cannot identify the current review stage or open condition.
The escalation should be short and factual:
- File or loan reference.
- Property address.
- Date the BPO was completed.
- Date the last full package was submitted.
- Current buyer deadline.
- Any foreclosure or auction deadline.
- Specific question that needs an answer.
The strongest escalation question is:
The BPO appears complete. Which review stage owns the file now, what condition is still open, and what is the next decision date?
That gives the lender a clear issue to answer.
Where Crisp Short Sales Helps
Crisp Short Sales helps agents organize short sale processing, lender follow-up, BPO review, document updates, title issues, approval-letter conditions, and escalation when a file is stuck.
The post-BPO stage is where many files either get organized or start drifting.
The seller may think approval is close. The buyer may be losing patience. The lender may still be waiting on value acceptance, investor review, mortgage insurance, title, payoff numbers, or updated documents.
The safest move is to identify the active review lane, document the open condition, and keep the buyer, seller, lender, and title team aligned until the approval letter is actually issued.
If your short sale is slow after the BPO, start with one clean question:
What is still open, and who owns the next decision?
Crisp can help agents get that answer and keep the file moving.
Frequently Asked Questions
Does a completed BPO mean a short sale is approved?
No. A completed BPO only helps the lender review property value. The file may still need investor, mortgage insurance, title, document, or closing review.
Why is my short sale still pending after the BPO?
The lender may still be reviewing value, investor rules, mortgage insurance, updated documents, payoff numbers, title issues, or approval-letter conditions.
What should an agent ask after a short sale BPO?
Ask whether the BPO was accepted, what review stage owns the file now, what condition is open, and when the next decision is expected.
Can an agent dispute a short sale BPO?
Sometimes. If the value appears too high, the agent may be able to submit comparable sales, repair evidence, photos, listing history, and market data.
Utah Foreclosure and Short Sales: What Agents Should Check First
Utah foreclosure deadline active? See what agents should check first so a short sale file is complete before trustee-sale pressure tightens.
When a Utah homeowner is facing foreclosure, a short sale can still be worth checking. But the order of operations matters.
The question is not just, "Can this seller do a short sale?"
The better first question is:
"What deadline is already active, and is the file complete enough for the lender to review before that deadline controls the outcome?"
Utah foreclosure timing can create real pressure for agents, sellers, buyers, title companies, and short sale negotiators. If the file is missing authorization, hardship documents, buyer proof, title information, payoff numbers, or a clear update path with the servicer, the short sale can lose time before anyone even reaches a real decision.
This guide is practical short sale process guidance, not legal advice. If the seller has received foreclosure notices or has questions about legal rights, they should speak with a qualified Utah attorney or housing counselor.
Why Utah Foreclosure Timing Changes the Short Sale File
Utah Courts explains that most Utah foreclosures are handled without a court case through a nonjudicial foreclosure process, also called a trustee sale.
That process can move through several stages. A homeowner may first receive a delinquency notice or preforeclosure notice. Later, the trustee may record a Notice of Default at the county recorder's office. Utah Courts says the Notice of Default gives the homeowner three months to become current on the loan, including allowed fees and costs. If the default is not cured, the trustee can move toward a Notice of Trustee's Sale.
For short sale purposes, those details matter because the lender review process has its own clock.
The servicer may still need updated financials, a signed authorization, listing history, a buyer contract, proof of funds or financing, valuation review, investor approval, mortgage insurance review, title review, payoff updates, and final approval-letter conditions.
That can take time. The closer the file is to a trustee's sale date, the less room there is for missing documents or vague follow-up.
First Check: Which Notice Does the Seller Have?
Agents should not treat every foreclosure warning the same way.
Ask the seller what they actually received:
- A notice of delinquency?
- A preforeclosure notice?
- A Notice of Default?
- A Notice of Trustee's Sale?
- A letter from the loan servicer about loss mitigation or foreclosure relief?
- A communication from a trustee, attorney, or title-related party?
The specific notice matters because it tells the team how urgent the file is and who needs to be contacted first.
If there is a trustee's sale date, that date should be written down immediately and treated as a hard risk point. The seller should also confirm the trustee name, loan servicer, loan number, property address, and any contact information shown on the notice.
Second Check: Who Is Authorized to Talk to the Servicer?
A Utah short sale can stall quickly if the lender will not speak with the agent, processor, or negotiator.
Before the team debates price or buyer terms, confirm that the servicer has the correct third-party authorization. The authorization should match the lender's requirements, identify the right loan, and allow the short sale processor or negotiator to speak with the servicer about the file.
Without authorization, the agent may keep calling for updates while the lender refuses to discuss the account.
This is one reason short sale help should start early. The file needs a communication path before the deadline gets tight.
Third Check: Is the Short Sale Package Complete Enough to Review?
Submitting a partial short sale package is not the same as putting the file under real review.
Most files need some combination of:
- Signed purchase contract.
- Seller hardship explanation.
- Financial documents requested by the servicer.
- Third-party authorization.
- Listing agreement and listing history.
- Estimated settlement statement or net sheet.
- Buyer proof of funds or financing.
- Payoff information.
- HOA, tax, judgment, or junior lien information when applicable.
- Property condition evidence if repairs or value concerns matter.
The exact request can vary by lender, investor, and loan type. The practical point is simple: if the servicer says the package is incomplete, the Utah foreclosure clock may keep moving while the file sits in intake.
That is where short sale processing makes a difference. A processor should not only send documents. They should track what was submitted, what the lender marked complete, what is still missing, and when the next review should happen.
Fourth Check: Can the Buyer Wait Long Enough?
In a normal sale, the signed purchase contract usually sets the closing path.
In a short sale, the seller can accept the buyer's offer, but the lender still has to approve the short payoff. That means the buyer's deadline and the bank's review timeline are not always the same.
Agents should confirm:
- Whether the buyer understands this is a short sale.
- Whether the buyer has a financing, rate-lock, inspection, or lease deadline.
- Whether the buyer can wait for lender approval.
- Whether the contract dates need to be extended.
- Whether the buyer can close quickly if approval arrives with a short deadline.
If the buyer is weak, uncertain, or poorly informed, the file can fall apart even if the lender eventually approves the short sale.
Fifth Check: Could Title or Liens Block Closing?
A short sale is not only a lender negotiation. It is still a real estate closing.
Utah agents should check title early, especially if there may be:
- A second mortgage or home equity line.
- HOA dues or association collection fees.
- Tax liens.
- Judgments.
- Probate or inherited-property issues.
- Payoff disputes.
- Repair credits or closing costs the lender may not approve.
If title waits until the bank is close to approval, the team can lose valuable time. That is a problem when foreclosure pressure is already present.
The safest approach is to keep title, payoff, buyer documents, and lender review moving at the same time.
What a Short Sale Negotiator Should Do First
A short sale negotiator or coordinator should create a clean status picture before pushing the lender for a decision.
That means confirming:
- The foreclosure stage and any trustee's sale date.
- The current servicer and investor review path.
- Whether authorization is active.
- Whether the package is complete.
- Whether the buyer is still committed.
- Whether valuation has been ordered or completed.
- Whether title issues are known.
- Whether the lender has a single point of contact or assigned review channel.
- Whether a postponement, escalation, or updated package is needed.
Utah Code section 57-1-24.3 addresses foreclosure-relief communication in owner-occupied residential trust deed situations, including a single point of contact and the ability for a beneficiary or servicer to postpone a trustee's sale to allow more time for negotiations. It also makes clear that the law does not require the lender to approve a foreclosure relief application.
That distinction matters. The team should not promise that a short sale will stop a foreclosure sale. The job is to give the lender a complete, credible file early enough to review.
What Agents Should Not Promise
Agents should be careful with promises in a Utah short sale under foreclosure pressure.
Do not promise that:
- Listing the property automatically stops foreclosure.
- A submitted package guarantees a postponement.
- A buyer offer guarantees lender approval.
- The lender will waive every deficiency, lien, fee, or condition.
- The trustee's sale date will move just because the property is in short sale review.
What agents can do is control the file quality.
They can document the deadline, collect the package, verify authorization, keep the buyer informed, open title early, track lender review, and escalate when the facts support it.
That is the practical work that gives a Utah short sale its best chance.
Final Takeaway
Utah foreclosure and short sales are both timing-sensitive. If a homeowner has received a Notice of Default or Notice of Trustee's Sale, the file needs immediate triage.
Start with the foreclosure notice. Confirm the deadline. Get authorization in place. Build a complete package. Check buyer commitment. Open title. Then track lender review until there is a clear answer.
If the file has a chance, it needs to look complete, credible, and easy for the servicer to review.
Crisp Short Sales helps agents and homeowners organize short sale documents, communicate with servicers, track review stages, negotiate short sale terms, and protect closing deadlines before foreclosure pressure gets tighter.
Start here if you need short sale help before a Utah foreclosure deadline.
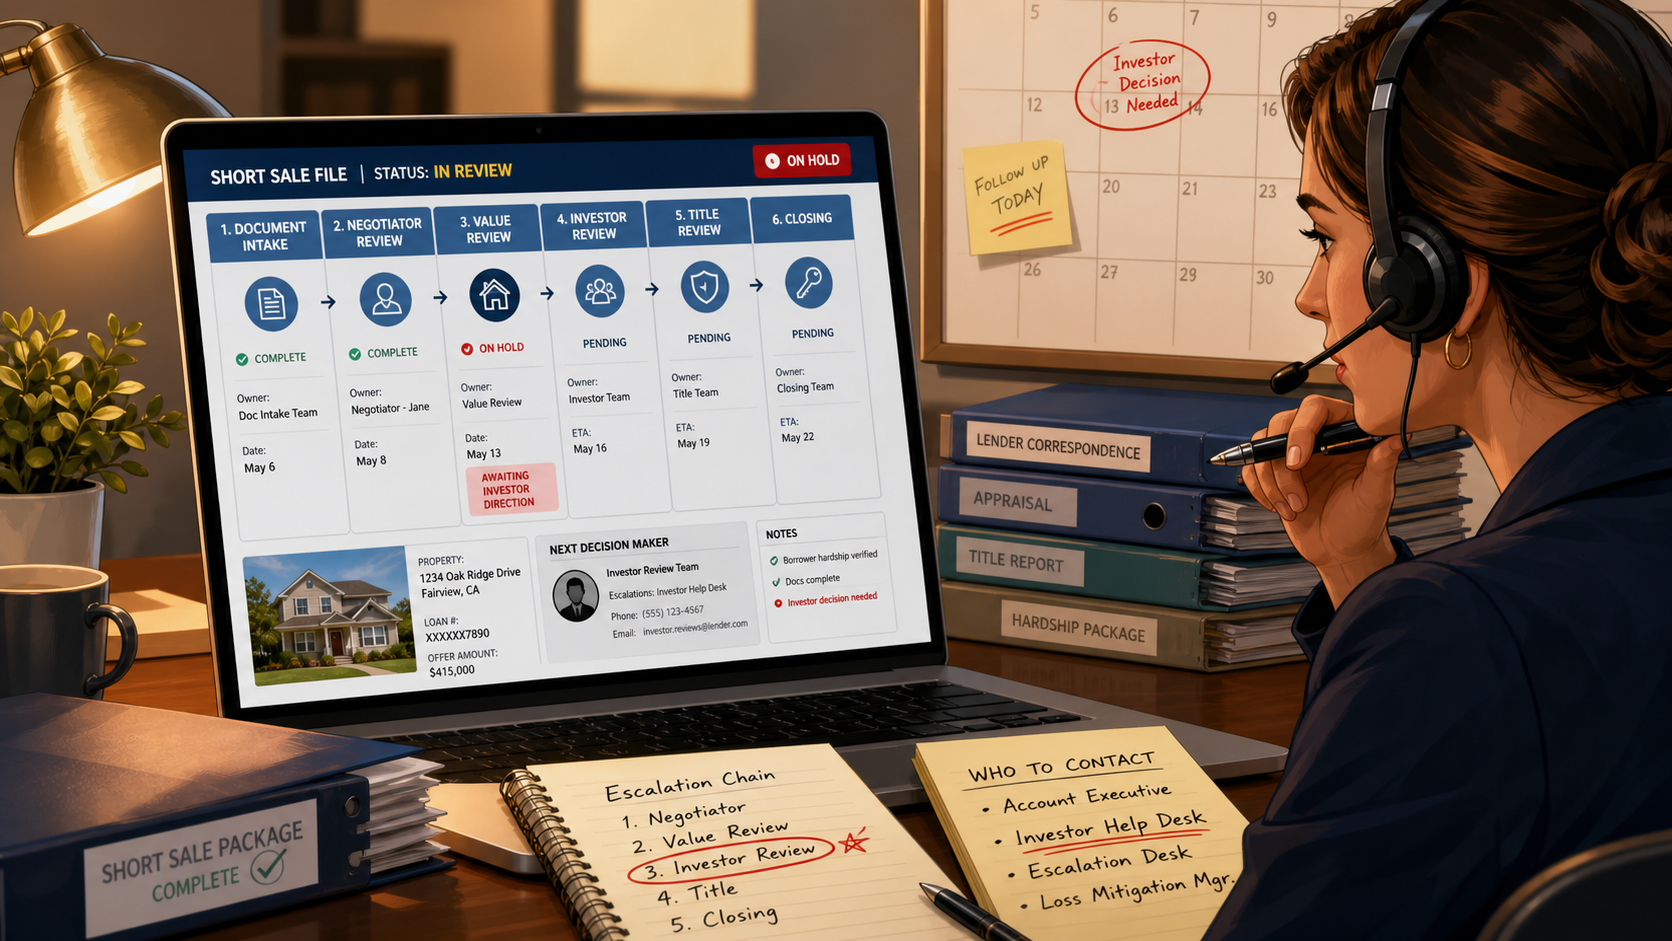
Short Sale Stuck? Who Agents Should Contact
Short sale file stuck? See whether the servicer, negotiator, investor, mortgage insurer, title, or closing desk is holding approval.
Fast Answer
If a short sale is stuck, the agent should first confirm whether the file is marked complete, then ask which review stage is active and who owns the next decision. The delay may sit with document intake, the short sale negotiator, valuation review, investor review, mortgage insurance, title, payoff review, or the closing desk.
Once the active bottleneck is clear, the agent can escalate with a focused request instead of sending another general status email.
Why "Any Update?" Does Not Work
A stuck short sale does not always mean the bank is ignoring the file. Sometimes the package is still in intake. Sometimes the short sale negotiator is waiting on a missing document. Sometimes the BPO is complete, but the investor has not approved the loss. Sometimes title, payoff numbers, mortgage insurance, or the closing desk is holding the file while everyone else thinks the deal is close.
That is why a vague "Any update?" email rarely fixes a stalled short sale. The better move is to identify who owns the delay right now, then ask that person or department the specific question that can move the file forward.
For broader timeline context, see our guide on why short sales take so long: https://www.crispshortsales.com/the-short-sale-blog/why-banks-take-so-long-to-approve-short-sales
Step 1: Confirm Whether the File Is Complete
Before escalating, ask one direct question:
Is the short sale file marked complete for review?
If the answer is no, the next job is not escalation. It is cleanup.
Common completeness problems include missing hardship documents, outdated bank statements, unsigned authorization forms, stale pay stubs, missing listing paperwork, or an incomplete offer package. A short sale processor or coordinator should confirm that the lender has the right version of each item and that the file is not being paused over a document already sent.
If the answer is yes, move to the next question:
Which review stage is active right now?
Step 2: Find the Active Review Lane
A stuck short sale usually belongs to one of these lanes.
Document Intake
This is where the lender checks whether the file can be reviewed at all. If the file is in intake, ask what document is missing, what version is unacceptable, and whether the file is marked complete after the correction is uploaded.
Do not assume that sending the document means the condition is cleared. Ask for confirmation.
Short Sale Negotiator
The short sale negotiator is often the main point of contact, but that does not mean the negotiator personally controls every answer. A negotiator may be waiting on value review, investor approval, mortgage insurance, or title.
Ask the negotiator:
- What stage is the file in today?
- What condition is preventing approval?
- Who owns the next action?
- What date should the agent follow up if nothing changes?
If the lender already gave a date and missed it, this companion guide explains what to ask after a missed bank review date: https://www.crispshortsales.com/the-short-sale-blog/short-sale-bank-missed-review-date-what-to-ask-next
The goal is to get the file out of vague status language and into a documented next step.
Valuation Review
If the lender ordered a BPO or appraisal, the file may pause while the bank reviews property value. This can happen even when the buyer is ready and the seller has provided everything.
Ask whether the value is complete, whether the lender accepted it, and whether there is a value dispute, counteroffer, or investor net issue.
If the bank value is clearly wrong, the agent may need a clean value rebuttal with comparable sales, repair evidence, property condition notes, and market data.
Investor Review
Many short sales require investor approval after the servicer finishes its own review. This is one of the most misunderstood delays because the servicer may have reviewed the file, but the final decision still belongs somewhere else.
Ask whether the file has been submitted to the investor, when it was submitted, what response is pending, and whether the investor requested any additional condition. If the answer is still vague, review the common reasons a file may be still waiting on the bank: https://www.crispshortsales.com/the-short-sale-blog/2026/8/25/why-is-the-short-sale-still-waiting-on-the-bank
Mortgage Insurance Review
Mortgage insurance can create a separate approval layer. The agent may hear that the short sale is "approved internally," but the file still cannot close until mortgage insurance signs off.
Ask whether mortgage insurance applies, whether that review is open, and whether the insurer is asking for a contribution, promissory note, updated hardship proof, or revised net sheet.
Title, Payoff, and Closing Desk
Some files stall after everyone thinks approval is close. That can happen when title issues, HOA balances, judgments, liens, payoff updates, or closing-statement numbers do not match the approval terms.
At this point, the right contact may not be the same person who reviewed the hardship package. The agent should confirm whether the file is with title review, payoff review, or the closing desk, then ask what exact item prevents the approval letter or closing clearance.
When to Escalate
Escalation makes sense when the file is complete, the review date passed, and no one can identify the next owner or condition.
The escalation should be factual and short. Include the loan or file reference, the date the package was completed, the last promised review date, the buyer's deadline, any foreclosure date, and the specific question that needs an answer.
The strongest escalation request is not "Please hurry." It is:
Which department owns the next decision, what condition is still open, and what is the next documented review date?
A Cleaner Follow-Up Structure
A good short sale follow-up should document four things:
- The current review stage.
- The open condition.
- The person or department responsible.
- The next date when action is expected.
That structure helps the agent protect the buyer, explain the delay to the seller, and decide whether the file needs a short sale specialist, processor, or negotiator to step in.
Where Crisp Short Sales Helps
Crisp Short Sales helps agents organize lender follow-up, document review, title issues, valuation disputes, and approval-letter conditions so the file does not sit in the wrong lane.
If you need short sale help on a stuck file, the fastest path is usually not more noise. It is a cleaner escalation chain, better documentation, and a clear next action for the person who actually controls the delay: https://www.crispshortsales.com/how-we-help

Texas Short Sale Contract Deadlines After Offer
Texas short sale approval can outlast contract dates. See what agents should track after the offer so bank delays do not cost the buyer.
When a Texas short sale offer is signed, the file can look like it is finally moving.
The buyer is in place. The seller wants the deal to work. The listing agent has a contract. The lender package can be submitted. Everyone wants to know one thing:
How long will the bank take to approve the short sale?
That question matters, but it is not the only clock in the deal. A Texas short sale can have several deadlines running at the same time: buyer deadlines, contract dates, lender review dates, foreclosure pressure, title requirements, payoff updates, and the final approval-letter closing window.
If those dates are not tracked together, the agent can end up with a buyer who is technically under contract but practically out of patience.
The Buyer Contract And Bank Review Are Different Clocks
The biggest mistake is assuming the contract timeline and bank timeline are the same thing.
They are not.
The buyer and seller may sign a purchase contract with a target closing date. The lender still has to review the seller's hardship, financial documents, purchase terms, buyer proof, property value, investor rules, title issues, payoffs, junior liens, allowed costs, and any foreclosure pressure.
That review can take longer than the original contract dates.
In a normal sale, the signed contract usually drives the closing path. In a short sale, the contract starts the lender approval process, but the lender's written approval is what makes the short payoff possible.
That is why Texas agents should not only ask, "When will the bank approve?"
They should also ask, "Which contract deadlines might expire before the bank answers?"
Start With The Buyer's Real Deadline
Not every buyer can wait the same amount of time.
Some buyers have financing timelines. Some have rate-lock concerns. Some have lease deadlines. Some have another property available. Some will wait if they understand the process. Others will walk if the lender goes quiet for too long.
The listing agent should identify the buyer's real pressure points early.
Ask:
- Does the buyer have a financing or rate-lock deadline?
- Is there an inspection, option, or due-diligence concern?
- Is the buyer flexible if bank approval takes longer than expected?
- Does the buyer understand that the seller's acceptance is not the same as lender approval?
- What update schedule will keep the buyer confident?
This is not about promising a bank approval date the agent cannot control. It is about knowing whether the buyer's patience will last long enough for the bank review to finish.
Make The Short Sale Approval Condition Clear
A short sale offer needs clear expectations around lender approval.
The seller may accept the buyer's offer, but the seller's lender still has to approve receiving less than the full payoff. If that condition is not understood, the buyer may think the deal is farther along than it is.
Agents should make sure the contract file, amendments, and communications make the short sale condition clear according to the forms and guidance they are required to use. If there is any uncertainty, the broker, title company, or attorney should be involved before the file gets messy.
The practical point is simple:
The buyer should know that the offer can be submitted to the lender, but the short sale is not truly approved until the lender issues written approval.
That written approval letter should then be checked against the contract, closing date, allowed costs, seller terms, lien treatment, payoff numbers, and title requirements.
Watch The Closing Date Before It Becomes Fiction
Many short sale contracts include a target closing date that was reasonable when the offer was written.
Then lender review takes longer.
The buyer still wants updates. The seller still needs relief. The title company may still be working. But the original closing date may no longer fit the approval timeline.
That is where files start to drift.
If the closing date passes without a clean extension or amendment, the parties may disagree about whether the buyer is still committed. If the bank later approves the short sale with a tight closing window, the team may have to rush because the contract side was not kept current.
Agents should track:
- Original closing date.
- Any amended closing date.
- Expected lender review date.
- Approval-letter expiration date once issued.
- Title and payoff readiness.
- Buyer financing status.
The goal is to avoid getting a lender approval letter only to discover that the buyer timeline, contract documents, or title work no longer support the closing.
Keep Title Moving While The Bank Reviews
Short sale approval time is not only about the lender.
Title can create its own deadline problems. Junior liens, HOA balances, judgments, tax issues, probate issues, payoff changes, and closing-cost disputes can all affect whether the lender will approve the final numbers.
If title work waits until the bank is close to approval, the file can lose days or weeks at the worst possible time.
That is why Texas agents should not wait for lender approval before checking whether the closing side is clean.
Ask early:
- Has title been opened?
- Are there junior liens or judgment issues?
- Are payoff figures current enough for review?
- Are HOA, tax, or municipal balances affecting the net?
- Will the settlement statement match the lender's approval conditions?
Short sale processing is not just sending documents to the bank. It is keeping the lender file, contract deadlines, and closing requirements aligned.
Foreclosure Pressure Changes The Risk
If a foreclosure sale date is active or approaching, every date in the file matters more.
A buyer deadline that might be manageable in a normal short sale can become a serious risk when foreclosure pressure is already present. The agent may need proof of package submission, proof the file is complete, proof of buyer commitment, title status, and a documented reason for the lender to keep reviewing the file.
That does not guarantee postponement or approval. But it gives the file a cleaner chance than vague updates and scattered documents.
When foreclosure pressure is involved, ask:
- Has the complete short sale package been submitted?
- Is the lender review active?
- Is there an assigned negotiator or review department?
- Is the buyer still committed in writing?
- Are any contract dates already expired or about to expire?
- Is title ready enough to support a fast closing if approval arrives?
This is where a short sale coordinator or negotiator can help keep the file from losing control.
What A Short Sale Coordinator Should Track After The Offer
Once the offer is accepted by the seller, the short sale coordinator should track more than the date of the last bank call.
A strong checklist includes:
- Date the seller accepted the offer.
- Date the package was submitted to the lender.
- Whether the lender marked the package complete.
- Active review stage.
- Buyer inspection, financing, and closing concerns.
- Contract amendments or extension needs.
- Title status.
- Payoff status.
- Junior lien or HOA issues.
- Foreclosure or sale-date pressure.
- Expected lender review date.
- Written approval-letter deadline once issued.
Without that tracking, the agent may only realize there is a problem when the buyer gets impatient or the approval letter arrives with a closing deadline that the team is not ready to meet.
How To Keep The Buyer From Walking
The buyer does not need a long explanation every day.
The buyer needs useful proof that the file is being managed.
Instead of saying, "The bank is still reviewing it," say something more specific when possible:
"The short sale package was submitted on Tuesday. The servicer has not marked it complete yet, so we are confirming the missing item. Title is already open, and we are watching the contract dates because the bank approval timeline may run past the original closing date."
That kind of update gives the buyer a reason to stay engaged. It shows that the file has an active plan, not just a waiting problem.
Final Takeaway
Texas short sale approval time matters, but it is only one part of the deal.
After the offer is accepted, the agent has to manage two clocks at once: the buyer's contract deadlines and the lender's short sale review timeline.
If the contract dates expire quietly, the buyer may walk. If title waits too long, approval can turn into a closing scramble. If foreclosure pressure is present, vague follow-up can cost valuable time.
The best move is to build the timeline before the file drifts:
Know the buyer's deadlines. Confirm the lender's review stage. Keep title moving. Track amendments and closing dates. Then check the written approval letter against the deal before anyone assumes the short sale is ready to close.
That is how short sale help protects a Texas file after the offer is signed.
Short Sale Authorization Missing? Why the Bank Won't Talk
The Bank May Not Be Ignoring You
When a short sale lender goes quiet, everyone feels the pressure.
The seller wants to know whether foreclosure can still be avoided. The buyer wants to know whether the deal is real. The agent wants a useful update. The title company may be waiting on payoff or lien information. The short sale processor may already have sent documents.
Then the bank says something like:
"We cannot discuss the account."
That answer is frustrating, but it is also a clue.
Sometimes the lender is not refusing to review the short sale. Sometimes the lender is saying it does not have permission to talk to the person asking for the update.
That is why authorization belongs near the top of any short sale processing checklist. Before anyone spends days chasing review status, make sure the right people are cleared to speak with the servicer.
What Authorization Does In a Short Sale
A short sale involves private mortgage information. The borrower owes more than the property can sell for, and the lender is being asked to approve a sale for less than the full payoff.
That means the servicer may need to discuss loan status, payoff figures, hardship documents, financial information, loss-mitigation options, foreclosure timing, title issues, valuation, investor review, and approval conditions.
The agent may need those details to move the file, but the agent is not automatically entitled to them. The borrower usually has to authorize communication first.
That authorization is often called a third-party authorization, borrower authorization, authorization to release information, or servicer authorization form. The exact format can vary by servicer.
The practical purpose is simple:
It tells the bank who is allowed to discuss the loan.
Without that permission, even a complete short sale package can hit a wall.
Common Authorization Problems
Authorization problems are easy to miss because they look small compared with the rest of the file.
But small mistakes can cause big delays.
Here are the common ones:
- The borrower did not sign the form.
- The form is signed but not dated.
- The date is too old for the servicer's requirements.
- The property address or loan number is missing or wrong.
- The agent is listed, but the short sale processor is not.
- The title company needs information but is not authorized.
- The authorization names a brokerage, but not the individual caller.
- The form was uploaded to the wrong portal section.
- The servicer received it but has not cleared it yet.
- The lender requires its own form instead of a generic authorization.
Any one of those issues can create the same symptom: no meaningful update.
That is why the first question should not be, "Why is the bank taking so long?"
The first question should be:
"Are we authorized to speak with the servicer on this loan?"
Do Not Let Access Problems Hide as Review Delays
There is a difference between a short sale file under review and a short sale file nobody can discuss.
If the authorization is not cleared, the agent may hear vague statements like:
- "We cannot provide that information."
- "The borrower needs to call."
- "We do not have you listed."
- "We need updated permission."
- "Please resubmit the authorization."
Those answers are not the same as lender review.
They mean the communication channel is not open yet.
This matters because the short sale clock keeps moving while everyone waits. Documents can expire. Buyer patience can fade. Foreclosure timelines can tighten. The file can lose days before anyone discovers that review never really started.
Good short sale help starts by separating access problems from review problems.
Who Should Be Listed
The authorization should match the way the file will actually be handled.
If the listing agent will call the bank, the agent should be listed. If the broker, assistant, short sale processor, or negotiator will communicate with the servicer, they may also need to be listed. If the title company needs payoff, lien, or closing information, it may need separate authorization depending on the servicer's process.
Do not assume one signature covers everyone.
Ask the servicer:
- Which names must be on the authorization?
- Does the company name need to be listed?
- Does each individual caller need to be listed?
- Is the title company allowed to request payoff information under this authorization?
- Does the authorization expire after a certain number of days?
- Does the servicer require a new authorization after servicing transfers?
These are not glamorous questions, but they prevent wasted follow-up.
What Agents Should Ask Before Chasing Status
Before asking for short sale review status, ask a tighter sequence:
1. Is there a current third-party authorization on file? 2. Has it been reviewed and accepted by the servicer? 3. Who is authorized to speak on the loan? 4. What information can each authorized person request? 5. Is anything missing from the authorization? 6. Where should corrections be submitted? 7. When can we call back for status after the authorization is cleared?
Once that is confirmed, then the agent can ask whether the short sale package is complete, assigned, in valuation, in investor review, waiting on title, or pending approval-letter drafting.
Without authorization, those later questions may never get answered.
How This Affects the Buyer
Authorization issues can also hurt buyer confidence.
From the buyer's point of view, the bank is silent. The buyer may not care whether the issue is a missing authorization, document review, valuation delay, investor review, or title problem. They just know no one has a real answer.
That is why the agent should turn the issue into a concrete update.
Instead of saying:
"We are still waiting on the bank."
Say something more useful:
"The lender would not release status because the authorization had not cleared. We corrected the authorization today, confirmed who is allowed to speak with the servicer, and will follow up after their processing window."
That kind of update does not guarantee approval. But it shows the buyer that the file is being managed, not ignored.
When a Short Sale Processor Helps
A short sale processor or negotiator is not just there to upload documents.
The role is to keep the file organized enough that the lender can review it. Authorization is part of that. So are hardship documents, financials, buyer proof, listing documents, payoff numbers, title issues, valuation support, and approval terms.
When authorization is handled correctly, the rest of the file has a better chance of moving in order. The processor can document who can call, when the authorization was submitted, when it cleared, what department confirmed it, and what the next review step is.
That record matters if the file later misses a review date or if the buyer starts asking whether anyone has actually spoken with the bank.
Do Not Resend Everything Blindly
One common mistake is resending the full short sale package every time the servicer says it cannot discuss the file.
That may not solve the problem.
If the issue is authorization, then sending bank statements, hardship letters, contracts, or settlement statements again may create more clutter without opening communication.
Ask what is actually missing.
If the missing item is authorization, fix that specific item. If the servicer requires a particular form, use that form. If the borrower needs to call first, get that instruction clearly. If the authorization cleared but the file is still not assigned, then move to the next issue.
Short sale processing works best when each problem is named and solved in order.
The Bottom Line
When a bank will not talk about a short sale, do not assume the file is simply under review.
First, check authorization.
A missing or incorrect authorization can make the lender look silent, block status updates, delay document review, frustrate the buyer, and waste time before anyone reaches the real short sale decision-maker.
The fix is straightforward: get the correct authorization signed, list the right people, submit it where the servicer wants it, confirm it cleared, and document the next follow-up date.
That is not the whole short sale.
But without it, the rest of the short sale may not even get a fair chance to move.
If the lender will not talk, solve the permission problem first. Then chase the review.
If the file needs help before access problems turn into review delays, start the short sale process before the deadline gets tighter.
FAQ
Why won't the bank talk to my agent about a short sale?
The bank may not have a current authorization allowing it to discuss the borrower's loan with the agent. The borrower usually needs to sign written permission before the servicer can share loan or short sale details with a third party.
What authorization does a short sale lender need?
The exact form depends on the servicer, but it usually needs the borrower name, loan or account details, property address, authorized contact names, signatures, dates, and sometimes company information.
Can missing authorization delay short sale approval?
Yes. Missing authorization can delay communication, document follow-up, status checks, escalation, payoff coordination, and other steps needed before approval.
Should an agent resend the full package if the bank will not talk?
Not automatically. First ask whether the problem is authorization. If authorization is missing or rejected, fix that item before resending the full short sale package.
Short Sale Bank Missed the Review Date? What to Ask Next
Bank missed the short sale review date? See what agents should ask next to find the blocker, protect the buyer, and keep approval moving.
Fast Answer
If the bank misses a short sale review date, the agent should stop asking for a general update and ask for the exact review stage, the missing condition, the assigned owner, and the next documented deadline. A missed review date does not always mean the short sale is denied, but it does mean the file needs tighter follow-up before the buyer loses confidence or the foreclosure timeline gets tighter.
The simplest safe move is to ask the servicer what changed since the last promised review date and what specific item must happen before approval can move forward.
What To Do Next
- Confirm whether the file is marked complete.
- Ask which review stage is holding the file (https://www.crispshortsales.com/the-short-sale-blog/2026/8/25/why-is-the-short-sale-still-waiting-on-the-bank).
- Find out whether documents, value, investor review, mortgage insurance, title, payoff numbers, or approval-letter drafting caused the missed date.
- Ask for the new review date and the name or department responsible.
- Send one clean follow-up message that documents the missed date, the open condition, and the next promised action.
The Review Date Passed. Now What?
Few short sale moments frustrate agents more than a missed why banks delay short sale approval (https://www.crispshortsales.com/the-short-sale-blog/why-banks-take-so-long-to-approve-short-sales).
The lender said the file would be reviewed by Friday. Friday passed. The buyer wants answers. The seller is nervous. The agent has already sent the package, followed up, and waited.
Now the file feels stuck again.
The mistake is treating every missed review date like the same problem. A short sale can miss a review date for several different reasons. The file may be missing a document. The valuation may not be back. Investor review may be pending. Mortgage insurance may be involved. Title may have a lien or payoff issue. The approval letter may be waiting on final terms.
The next move is not just another "any update?" email.
The next move is to identify what caused the review date to slip.
First, Confirm The File Is Actually Complete
A bank review date may be missed because the file was never fully cleared for review.
That can happen even when the agent believes everything was submitted. The lender's system may still show a missing bank statement page, expired pay stub, unsigned form, outdated hardship letter, buyer proof issue, missing authorization, or settlement-statement mismatch.
Ask this directly:
Is the short sale package (https://www.crispshortsales.com/the-short-sale-blog/why-short-sales-stall-after-file-looks-complete) marked complete in the lender's system?
If the answer is no, ask for the exact missing item. Do not let the file sit under vague language like "still pending review." A short sale processor should identify the specific document, the required date range, where it should be uploaded, and when it will be cleared after submission.
That is the difference between document forwarding and real short sale processing help (https://www.crispshortsales.com/how-we-help).
Ask Which Review Stage Missed The Deadline
A missed review date is not useful unless you know what was supposed to be reviewed.
Was it document review? Valuation review? Negotiator review? Investor review? Mortgage insurance review? Title review? Final approval-letter review?
Those are different delays with different fixes.
If the file is waiting on valuation, the agent may need to confirm whether the BPO or appraisal was ordered, completed, received, and reviewed. If the value came in too high, the next step may be condition evidence or a value dispute.
If the file is waiting on investor review, the servicer may not control the final timeline. The agent should ask whether the package has actually been sent to the investor and whether any investor-specific conditions are open.
If the file is waiting on title or payoff numbers, the title company may need to resolve liens, HOA balances, judgments, taxes, junior liens, or updated payoff figures.
The question is simple:
Which review stage missed the deadline, and what is blocking it now?
Do Not Let "Under Review" Be The Whole Answer
"Under review" sounds official, but it often hides the real issue.
A stronger follow-up asks:
- Who has the file right now?
- What stage is open?
- What condition is preventing the next decision?
- Is anything missing, expired, mismatched, or waiting on a third party?
- What is the new review date?
- What happens if that date is missed again?
This does not mean the lender will suddenly approve the short sale. But it does create a record and pushes the conversation toward a specific next action.
That matters when a buyer is getting impatient or a foreclosure date is approaching.
Check Whether The Buyer Timeline Still Works
When the bank misses a review date, the buyer may start questioning the deal.
That is understandable. The buyer may have inspection deadlines, financing timelines, rate-lock concerns, moving plans, or another property available. If the buyer feels like nobody knows what is happening, they may walk before the lender reaches a decision.
Agents should update the buyer with facts, not filler.
Instead of saying, "The bank is still reviewing it," say something more specific:
"The lender missed the document review date. We confirmed the file is marked complete, and the negotiator says valuation review is now the active stage. The next promised review date is Thursday."
That kind of update gives the buyer a reason to keep waiting because it shows the file is being managed.
Watch For Approval Letter Timing
Sometimes the bank has accepted the terms internally but has not issued the written approval letter.
That still matters.
A short sale is not ready to close until the written approval letter confirms the approved sale price, closing deadline, allowed costs, deficiency language, seller contribution terms, junior lien terms, relocation assistance terms if any, and other closing conditions.
If the review date was tied to final approval, ask:
- Has the short sale been approved internally?
- Is the written approval letter being drafted?
- Are any approval-letter conditions still open?
- What deadline will appear in the approval letter?
- Will the buyer and title company have enough time to close?
This is where short sale help can protect the deal from a late-stage surprise. A verbal update is not the same as a written approval letter.
When To Escalate
Escalation makes sense when the lender misses a review date and cannot identify the active blocker.
Before escalating, organize the file:
- Submission date.
- Prior promised review date.
- Proof the package was submitted.
- Current buyer deadline.
- Foreclosure or sale-date pressure, if any.
- Exact open condition, if known.
- Prior lender responses.
- Requested next review date.
Then ask for the file to be reviewed by the assigned negotiator, team lead, escalation department, investor contact path, or loss mitigation supervisor, depending on the servicer's process.
The goal is not to send a louder version of the same message. The goal is to give the right person a clear reason to move the file.
What A Short Sale Processor Should Track
A strong short sale processor or short sale coordinator should track more than the date of the last follow-up.
They should track:
- Date the package was submitted.
- Date the file was marked complete.
- Active review stage.
- Assigned negotiator or department.
- Valuation order and completion status.
- Investor or mortgage insurance status.
- Title, payoff, HOA, and lien issues.
- Approval-letter conditions.
- Buyer deadline.
- Next promised lender action.
Without that tracking, every missed review date becomes a new emergency.
With that tracking, the team can see whether the file is truly stalled or moving through a specific review lane.
The Bottom Line
When a bank misses a short sale review date, do not treat the delay as a mystery.
Find out what stage missed the deadline, what condition is still open, who owns the next step, and when the file will be reviewed again.
A missed review date does not automatically mean the short sale is dead. But it does mean the file needs cleaner follow-up, better tracking, and more specific questions.
If the buyer is waiting, the seller is nervous, or the foreclosure timeline is tightening, vague updates are not enough. The file needs a clear short sale processing plan that turns missed dates into documented next steps.
Related short sale delay guides
For more context, review why banks delay short sale approval (https://www.crispshortsales.com/the-short-sale-blog/why-banks-take-so-long-to-approve-short-sales), which review stage is holding the file (https://www.crispshortsales.com/the-short-sale-blog/2026/8/25/why-is-the-short-sale-still-waiting-on-the-bank), and why short sales stall after the file looks complete (https://www.crispshortsales.com/the-short-sale-blog/why-short-sales-stall-after-file-looks-complete).
Need help keeping a delayed file organized? Start the short sale process (https://www.crispshortsales.com/start-short-sale).
Why Is the Short Sale Still Waiting on the Bank?
Short sale approval stuck? Learn which bank review lane is holding the file, what to ask next, and how to keep the buyer from walking.
Fast Answer
Short Sale Waiting on the Bank?
If a short sale is still waiting on the bank, the file may be in document review, valuation review, investor review, mortgage insurance review, title review, payoff review, or approval-letter drafting. Agents should ask the servicer which review lane is active, whether the file is marked complete, what condition is still open, and what specific next action is needed.
What To Ask Next
Is the file marked complete and assigned for short sale review?
Has the valuation been ordered, completed, received, and reviewed?
Is the file with the servicer, investor, or mortgage insurance company?
Are title, lien, payoff, HOA, or closing-cost conditions still open?
Has final approval been issued in writing, or is the approval letter still pending?
Short sale waiting can feel worse than a clear denial.
The buyer is asking for updates. The seller is nervous. The listing agent has already sent the package. Everyone wants to know the same thing: why is the bank still not answering?
The important point is this: a short sale is not usually sitting in one simple approved-or-denied pile. It often moves through several lender review lanes before anyone can issue a real answer. If you do not know which lane the file is in, every follow-up starts to sound the same, and that is when buyers lose confidence.
Good short sale processing help starts by identifying the active bottleneck.
The Bank May Not Be Waiting on the Same Thing You Are
Agents often think the lender is reviewing the offer.
Sometimes that is true. But many short sale delays happen before the offer is the real issue.
The servicer may still be checking seller documents. The valuation department may be waiting on a BPO or appraisal. The investor may need to approve the loss. Mortgage insurance may require a separate signoff. Title may have a lien, HOA, judgment, or payoff issue. The approval letter may be drafted but not released because one condition is still unresolved.
That is why a short sale can look quiet from the outside even when something is happening inside the lender's system.
The problem is that something is happening is not good enough when a buyer deadline is approaching.
Review Lane 1: Document Completeness
Before a bank can negotiate a short sale, the file has to be complete.
That sounds basic, but this is where many files lose time. A servicer may need updated bank statements, pay stubs, tax returns, hardship information, authorization forms, listing documents, buyer proof of funds, contract addenda, payoff statements, or investor-specific forms.
The agent may believe the package was sent. The servicer may still have it coded as incomplete.
Those are two different realities.
Ask this: Is the file marked complete and assigned for short sale review?
If the answer is no, ask for the exact missing item. Do not resend the entire package blindly unless the servicer specifically needs a full resubmission. That is one reason banks can appear to ask for the same thing twice, which we covered in why banks ask for short sale documents twice.
Review Lane 2: Valuation
A short sale can also stall while the bank decides what the property is worth.
This may involve a BPO, appraisal, automated value review, condition notes, comparable sales, repair evidence, or an investor value threshold. The bank may not counter, approve, or reject the offer until valuation is complete.
Ask this: Has the valuation been ordered, completed, received, and reviewed?
Those are four separate steps. A file can be delayed at any one of them.
If the value comes back too high, the next move may be a value dispute or better condition evidence, not just another status request.
Review Lane 3: Investor Review
The servicer is often not the final decision-maker.
Even after the servicer reviews the file, the investor may need to approve the loss. Investor rules can affect the acceptable payoff, closing timeline, contribution requirements, relocation money, deficiency language, and approval conditions.
This is why an agent can hear the file is in review for days without getting a usable answer.
Ask this: Is the file still with the servicer, or has it been submitted to the investor?
That one question can clarify whether the delay is internal servicer processing or final investor approval.
Review Lane 4: Mortgage Insurance
Mortgage insurance can add another review layer.
If mortgage insurance is involved, the servicer may need approval from the mortgage insurance company before issuing the final short sale approval letter. That can affect timing, required seller documents, contribution demands, and closing conditions.
Agents should not assume the servicer is ignoring the file if the delay is actually with mortgage insurance.
Ask this: Is mortgage insurance involved, and has that review been submitted?
That keeps the file from being treated like a generic lender delay.
Review Lane 5: Title, Liens, HOA, and Payoffs
Some short sale files wait because the lender needs clean numbers.
The bank is not just looking at the offer price. It is looking at the net. Title problems, junior liens, HOA balances, judgments, tax liens, utility liens, attorney fees, payoff changes, and closing costs can all change the lender's expected recovery.
If the title side is not clear, approval can slow down even when the buyer is ready.
Ask this: Are there any title, lien, payoff, HOA, or closing-cost conditions holding review?
This helps separate a lender delay from a closing-risk delay.
Review Lane 6: Approval Letter Drafting
Sometimes the file is close, but not done.
The servicer may have a verbal approval, internal approval, investor approval, or accepted terms, but the written approval letter still needs to be drafted and released.
That distinction matters because agents should not let the buyer, seller, title company, or closing attorney treat the deal as fully approved until the written approval letter is in hand.
Ask this: Has final approval been issued in writing, or is the approval letter still pending?
If the letter is pending, also ask whether any conditions must be resolved before release.
What Agents Should Send Instead of Another Vague Follow-Up
When the bank is quiet, the follow-up should make the next answer easy.
Send a short, organized message that includes:
The short sale submission date.
The buyer's current deadline or contract concern.
The foreclosure or sale-date pressure, if any.
A request to confirm whether the file is complete.
A request to identify the active review lane.
A request for the exact missing condition or next action.
A request for the assigned negotiator or escalation contact, if applicable.
The goal is not to sound louder. The goal is to remove ambiguity.
A good short sale negotiator does not just ask for updates. They make the lender identify what is actually blocking the file.
This is also how agents avoid the vague waiting period we covered in why short sales stall after the file looks complete.
When to Bring in Short Sale Help
If the file has been waiting and nobody can clearly say whether it is in document review, valuation review, investor review, mortgage insurance review, title review, payoff review, or approval-letter drafting, the file needs tighter management.
That is where short sale assistance can help.
A short sale processor or short sale specialist should keep the file organized, track the review lane, document follow-ups, manage buyer urgency, and push the correct next step without creating a mess of duplicate emails and scattered attachments.
The right question is not only why is this taking so long?
The better question is: Which review lane is holding the file, and what has to happen next?
Final Takeaway
When a short sale is still waiting on the bank, silence does not always mean nothing is happening. But it does mean the agent needs clearer answers.
Do not treat every delay the same.
Find out whether the file is waiting on documents, valuation, investor review, mortgage insurance, title, payoff numbers, or the written approval letter. That is the practical next step behind why banks delay short sale approval, and it is how an agent moves from vague silence to a real decision.
If your short sale file is stuck and the bank is not giving clear answers, Crisp can help you start the short sale process with a cleaner follow-up strategy.