

Short Sale Incentive Programs: What Blocks Seller Money
Short sale incentive money can help sellers move, but approval terms, occupancy, timing, and closing documents can block payment.
Short sale incentive programs can make a difficult move more manageable. For a seller who is already under foreclosure pressure, even a modest relocation payment can help with movers, storage, a rental deposit, utility setup, or the basic cost of leaving the home in good condition.
But agents and sellers should be careful with one assumption:
If incentive money exists, the seller will automatically receive it.
That is not how short sales work.
Short sale relocation assistance, move-out money, cash-for-keys style payments, and seller incentive programs usually depend on the loan type, investor, servicer, approval terms, occupancy status, closing documents, and timing. A seller can be in hardship and still be denied. A seller can qualify early and still lose the payment if the final approval or settlement statement is wrong.
Before anyone counts on the money, check the blockers.
The Approval Letter Has to Say More Than "Approved"
A short sale approval letter can approve the sale but still leave the seller with no incentive payment.
That is why the first check is simple: does the approval letter clearly allow the seller to receive money?
Look for language about short sale relocation assistance, incentive payment, transition assistance, seller proceeds, cash contribution, occupancy, closing costs, and disallowed payments. The amount should be clear. The payee should be clear. Any conditions should be clear.
If the approval letter is silent, vague, or says the seller cannot receive funds from closing, do not assume the payment can be added later.
The safest next step is to ask the servicer or authorized short sale contact in writing before closing. If the payment is approved, the file may need a corrected approval letter, written closing instruction, or settlement statement update.
Related guide: what the short sale approval letter must say about relocation assistance.
Occupancy Can Decide the Answer
Many short sale incentive programs are tied to the seller living in the property.
That means the seller may lose eligibility if the property is already vacant, rented, abandoned, occupied by someone else, or delivered in a condition that violates the approval terms.
Agents should confirm this before giving advice about moving out early. A seller may think leaving quickly shows cooperation, but in some files, moving before the right time can create a problem.
The practical question is not just:
Can this seller get incentive money?
The better question is:
Does this specific program require the seller to occupy the property through approval, closing, or a required move-out date?
If the answer is yes, the move-out plan should match the approval terms.
Seller Contributions Can Block the Payment
Some files require the seller to contribute cash toward the short sale. In those situations, incentive money can become more complicated.
Investor rules may prevent a seller from receiving relocation assistance if the seller is also required to make a cash contribution. There may be exceptions, but those exceptions usually need written approval.
This is where short sale files can become confusing. The seller may hear "relocation assistance" and "cash contribution" in the same conversation, but the two may conflict depending on the investor and file facts.
Do not try to solve that at the closing table. If the servicer is asking for seller contribution money, confirm whether that affects any relocation or incentive payment before final documents are prepared.
Outside Assistance Can Reduce or Eliminate Incentive Money
Some sellers may receive move-out help from another source. That can include government relocation assistance, employer relocation help, buyer concessions, third-party payments, or other transaction-related assistance.
Depending on the investor and program, outside assistance may reduce the incentive amount or make the seller ineligible for part of the payment.
That does not mean every outside payment is prohibited. It means the source and disclosure matter.
If money is connected to the transaction, the closing team and short sale negotiator should confirm whether it must be disclosed and whether it affects the lender-approved incentive.
Side payments are especially risky. If a payment is part of the deal, do not keep it informal. Get it reviewed before closing.
The Settlement Statement Has to Match
Even when incentive money is approved, it still has to be handled correctly in the closing documents.
The settlement statement should show the payment in the right amount, under the right description, and in a way that matches the approval letter and closing instructions. If the document is wrong, the lender may reject the final closing package or delay funding.
This is one of the most preventable problems in a short sale.
Before closing, compare:
- The approval letter.
- The settlement statement or closing disclosure.
- Any servicer closing instructions.
- Any investor-specific relocation or incentive conditions.
If they do not match, fix the mismatch before closing.
Late Requests Are Harder to Win
A seller may ask about move-out money after approval, especially if they are worried about paying for the move.
Sometimes a late request can still be reviewed. But it is harder once the servicer has approved final terms, issued a closing deadline, reviewed the net proceeds, and prepared closing instructions.
A late request is most likely to create a problem when:
- Closing is days away.
- The approval letter already says no seller proceeds are allowed.
- The settlement statement is locked.
- The buyer or title company is waiting on final approval.
- The incentive would reduce the lender's required net.
- The foreclosure deadline is close.
If incentive money matters to the seller, raise the issue before approval. That gives the short sale negotiator more room to document eligibility and request the payment correctly.
Related guide: asking for short sale move-out money after approval.
Program Names Can Be Misleading
Short sale incentive programs have changed over time. Some older programs ended, some investor rules changed, and different servicers may use different names for similar concepts.
That is why agents should avoid promising a seller a specific dollar amount based on something they saw online or handled years ago.
The current file controls the answer.
Loan type matters. Investor rules matter. Servicer authority matters. Occupancy matters. Approval-letter language matters. Closing documents matter.
If the seller needs the money to move, get the answer in writing early.
What Agents Should Check Before Promising Incentive Money
Before telling a seller they can count on short sale incentive money, check these items:
- What loan type is involved?
- Who is the investor or insurer?
- Does the servicer currently offer relocation or incentive money on this file?
- Does the seller still meet occupancy rules?
- Is the seller required to make a cash contribution?
- Is the seller receiving relocation help from another source?
- Is the amount written into the approval letter?
- Does the settlement statement show the payment correctly?
- Does the closing deadline leave enough time to correct mistakes?
- Has the payment been reconfirmed if terms changed?
If one of those answers is unclear, the seller should not make moving plans around the money yet.
The Safe Rule
Short sale incentive money is not real until it is approved in writing and matches the closing documents.
That may sound strict, but it protects everyone.
It protects the seller from counting on funds that may not be paid. It protects the agent from making a promise the lender will not honor. It protects the title company from closing with documents that do not match approval terms. It protects the buyer from a last-minute delay.
Short sale relocation assistance can be valuable. It can help a seller leave the home cleanly and move forward after a difficult financial stretch. But the details need to be handled before closing, not after the seller has already made commitments.
If a short sale file includes possible incentive money, review the approval terms early, confirm eligibility, and make sure the settlement statement matches before the deadline gets tight.
Crisp Short Sales helps agents and sellers review short sale approval terms, coordinate lender requirements, and avoid avoidable closing problems. If you need short sale help before the approval or move-out deadline gets too close, start the review early.
Related guide: short sale relocation assistance.
FAQ
Is short sale incentive money guaranteed?
No. Incentive money depends on the loan, investor, servicer, seller eligibility, occupancy, approval terms, and closing documents.
Why can short sale relocation assistance be denied?
It may be denied because the seller does not meet occupancy rules, the approval letter does not allow the payment, the seller is required to contribute cash, another source is providing assistance, or the settlement statement does not match the approved terms.
Does incentive money have to appear on the settlement statement?
In practical short sale closings, the payment should be disclosed correctly and match the lender's approval terms. If the approval letter and settlement statement do not match, the issue should be fixed before closing.
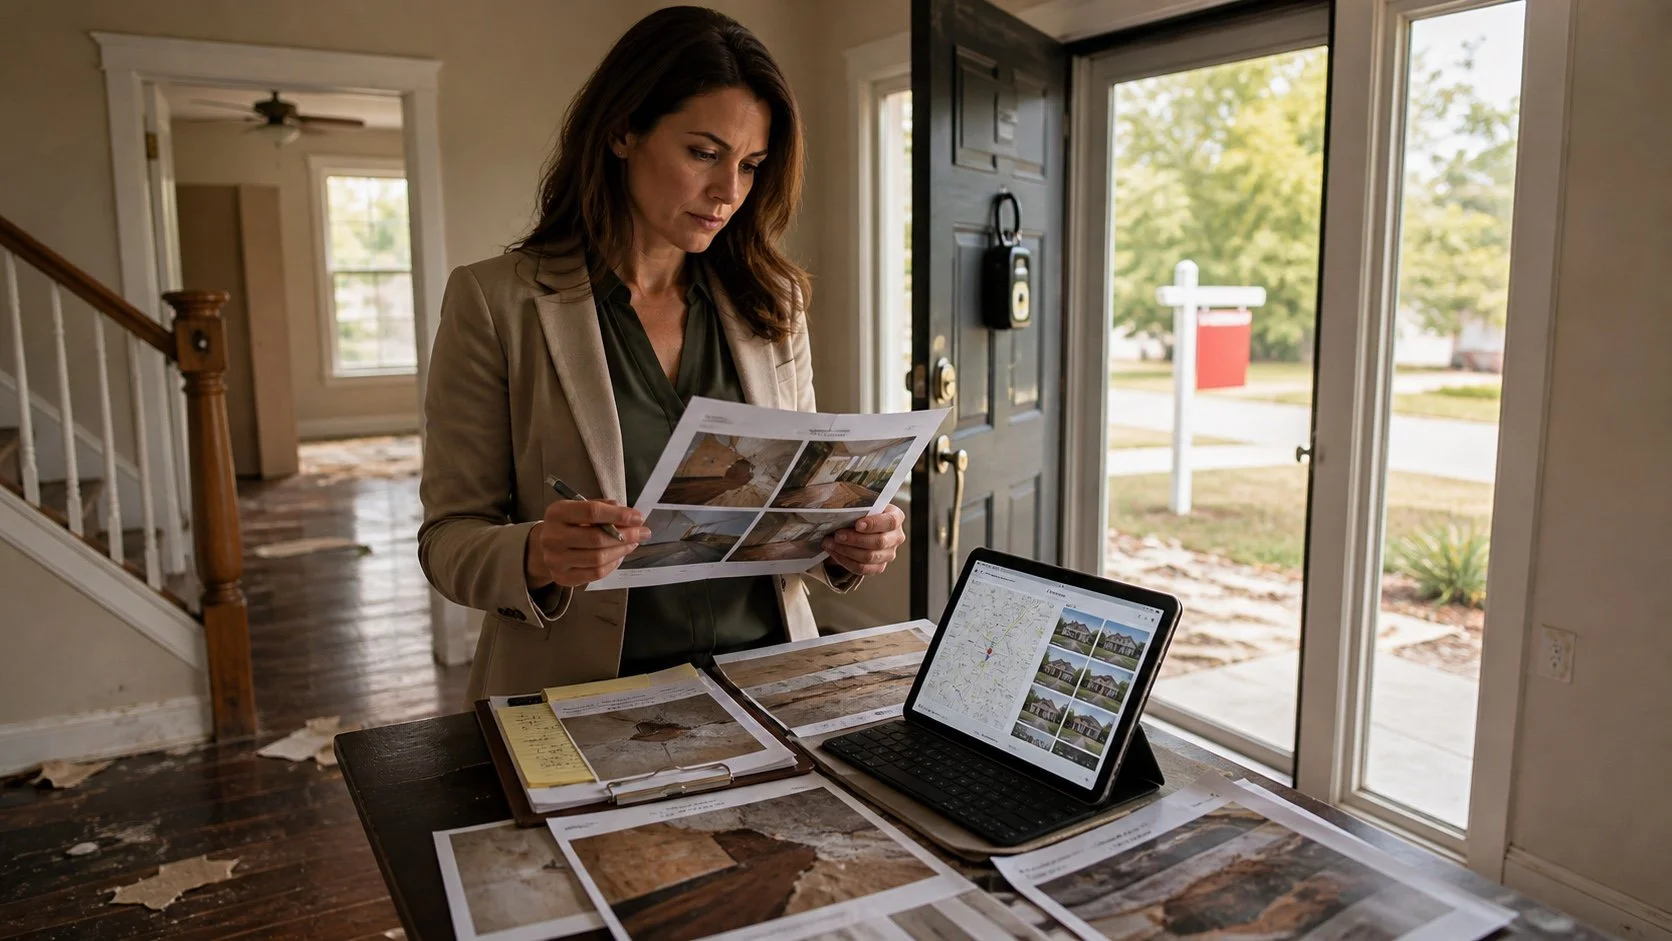
Short Sale BPO Rebuttal Package: What Evidence Works?
Bank value too high? See what evidence agents can send to challenge a short sale BPO and keep the approval moving.
What Is a BPO Rebuttal in a Short Sale?
A short sale can move smoothly for weeks and then suddenly stall because of one number: the bank's property value.
That value often comes from a BPO, or broker price opinion. If the BPO comes in too high, the lender may reject the offer, ask the buyer to increase, delay the approval, or hold the file open while the market moves around the deal.
The good news is that a high BPO is not always the end of the road. The bad news is that simply saying "the value is too high" usually does not help.
A stronger approach is to send a clean BPO rebuttal package that gives the lender specific reasons to question the value.
A BPO rebuttal is a value-challenge package sent to the lender or servicer when the short sale value appears too high for the property's real condition, location, market, or buyer pool.
The goal is not to argue emotionally. The goal is to make the lender's review easier.
A useful rebuttal answers three questions:
- What did the BPO likely miss?
- What evidence shows the property is worth less?
- Why is the current offer still the strongest realistic path to closing?
That means the package needs more than a short email. It should include photos, repair details, better comparable sales, market context, and a clear explanation of why the current BPO number may not match reality.
Start With the Property Condition
The first place to look is the property itself.
If the BPO relied on exterior photos, old listing photos, or broad neighborhood data, it may not reflect the true condition of the home. This matters in short sales because many properties have deferred maintenance, damage, occupancy issues, missing appliances, title delays, or repair problems that reduce buyer demand.
Strong condition evidence can include:
- Clear photos of damage or deferred maintenance
- Contractor estimates
- Inspection findings
- Agent notes from a walkthrough
- Buyer repair objections
- Photos showing outdated systems, flooring, roof issues, water damage, or safety concerns
The photos should be organized, not dumped into a messy attachment. Label the issue in plain English and explain why it affects value.
For example, "rear bedroom flooring damaged" is more helpful than "see attached photos."
If the file already has short sale BPO photos, use them as evidence instead of treating them as decoration. The lender needs to see what the valuation missed and why the buyer's offer may still be reasonable.
Use Comparable Sales That Match the Property
A common BPO problem is that the value is based on cleaner, newer, larger, or better-located homes.
Your rebuttal should show better comparable sales when possible. The best comps are recent, nearby, similar in size, similar in condition, and similar in buyer appeal.
If the BPO appears to use renovated homes while the short sale property needs repairs, point that out directly.
Useful comp notes include:
- Distance from the subject property
- Sale date
- Square footage
- Bedroom and bathroom count
- Condition differences
- Whether the comp was renovated or distressed
- Any location difference, such as a busy road, flood area, school zone, or neighborhood boundary
Do not overload the lender with every possible comp. A few strong, clean comparisons are better than a long list that makes the file harder to review.
The lender is looking for a reason to reconsider the number. Your job is to make that reason obvious.
Explain Buyer Reality
The lender may see a number on a report. The agent sees how buyers are reacting.
That market feedback can matter, especially when the property has already been exposed to buyers.
Include relevant buyer reality, such as:
- Days on market
- Showings with no offers
- Buyer repair concerns
- Low investor interest
- Financing issues caused by property condition
- Prior price reductions
- Offer history
The strongest point is simple: if the current buyer is the only serious buyer at a realistic price, the lender needs to understand that rejecting the offer may not produce a better result.
This is also why timing matters. Short sale BPO and appraisal delays can create a gap between what the lender thinks the property is worth and what the market is actually willing to pay.
Keep the Rebuttal Easy to Review
Short sale departments move through a lot of files. A rebuttal that is hard to understand may get ignored, delayed, or bounced back for more information.
A good package should be simple:
- One short cover letter
- A clean photo set
- A small group of better comps
- Repair estimates or condition notes
- The current offer summary
- A clear request for value review
The cover letter should not sound angry. It should sound useful.
A strong opening could be:
"The current BPO value appears to rely on comparable sales that do not reflect the property's repair condition. Attached are condition photos, repair notes, and recent comparable sales that support reconsideration of value."
That gives the lender a reason to keep reading.
What Not to Send
Some rebuttals fail because they create more confusion than clarity.
Avoid sending:
- Blurry photos
- Unlabeled repair pictures
- Old comps
- Comps from a different neighborhood
- Emotional hardship details unrelated to value
- Long arguments with no backup
- Huge attachments with no summary
- A demand that the lender accept the offer without evidence
The lender needs a reason to reconsider the BPO. Give them that reason quickly.
When to Send the Rebuttal
Send the rebuttal as soon as the value problem is clear.
Waiting too long can cause the buyer to walk, the foreclosure timeline to tighten, or the approval window to expire. If the file already has an offer, every extra week matters.
The short sale coordinator or negotiator should also confirm how the lender wants value disputes submitted. Some servicers want a specific form, portal upload, or escalation path. Others will accept a written rebuttal with supporting attachments.
This is where experienced short sale processing can help. The evidence is important, but so is getting it into the right channel before the file loses momentum.
If the BPO comes in too high, the next move should be organized proof, not a frustrated email.
The Bottom Line
A high BPO does not automatically end a short sale, but a weak response can make the problem worse.
The best BPO rebuttal package is clear, organized, and focused on evidence. Show the lender what the valuation missed, support the current offer with better market data, and make the review easy.
If the bank's value is too high, the next move is not panic. The next move is proof.
If you need help preparing or submitting a short sale value dispute, you can start the short sale process with Crisp Short Sales before a bad value review causes the buyer to walk.
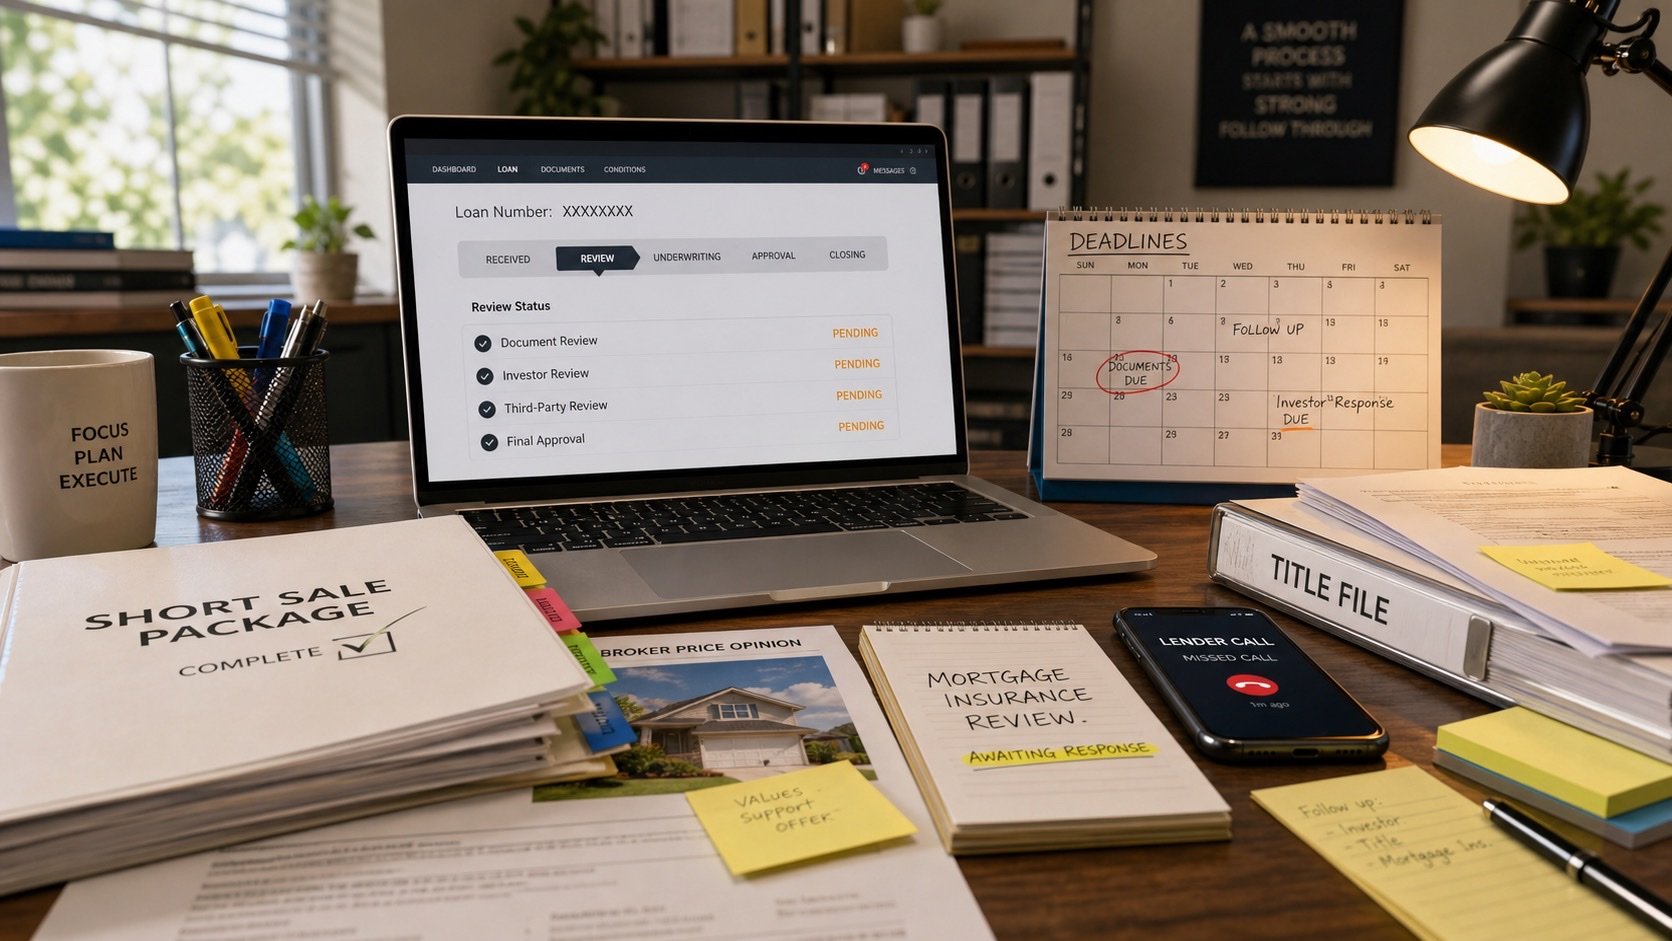
Why Short Sales Stall After the File Looks Complete
Short sale file submitted but still stuck? See the hidden lender, title, value, and approval steps that can delay review after everything looks complete.
The File Looks Complete. So Why Is Nothing Happening?
This is one of the most frustrating moments in a short sale.
The seller signed the hardship package. The buyer submitted the offer. The agent sent the contract. The financial worksheet is in. The payoff numbers have been requested. Everyone thinks the hard part is done.
Then the file sits.
No approval.
No clear answer.
No clean next step.
This is why so many agents ask the same question: why do short sales take so long after everything has already been submitted?
The answer is that a short sale package can be complete at the document level but unfinished at the review level. Those are not the same thing.
"Submitted" Does Not Mean "Approved"
In a normal transaction, sending a complete package often feels like the finish line.
In a short sale, it is closer to the starting line for lender review.
Once the servicer receives the short sale package, the file may still need to pass through several internal checkpoints. Depending on the loan, investor, insurer, and file history, that may include:
- Document intake review.
- Seller hardship review.
- Valuation or BPO review.
- Investor review.
- Mortgage insurance review.
- Title and lien review.
- Buyer and offer review.
- Final approval-letter drafting.
The file can be "complete" for intake but still waiting on one of those steps.
That is why short sale processing is not just about uploading documents. The real work is tracking what stage the file is in, what condition is open, and what response will move it forward.
Delay 1: The Documents Are Complete But Not Current
Short sale documents age quickly.
A bank statement that was current when the file was first submitted may be stale by the time the reviewer opens the file. Pay stubs, profit and loss statements, financial worksheets, hardship letters, buyer proof of funds, and estimated settlement statements can all need updates.
This is where a file starts to feel circular.
The agent says, "We already sent that."
The servicer says, "We need updated versions."
Both can be true.
The fix is to track document expiration dates before the servicer asks again. A short sale processor should know which items are likely to expire and refresh them before review resets.
Delay 2: The File Is Waiting On Valuation
Many short sales stall because the lender has not finished deciding what the property is worth.
That value may come from a BPO, appraisal, automated valuation, investor review, or a combination of those inputs. If the short sale BPO value comes in higher than the offer, the lender may counter, pause, or ask for more support.
This does not always mean the offer is dead.
It does mean the file needs evidence.
Helpful evidence may include:
- Clear property photos.
- Repair estimates.
- Condition notes.
- Comparable sales.
- Listing history.
- Buyer feedback.
- Market data that supports the offer.
If the value issue is not identified early, everyone may think the lender is simply slow. In reality, the approval may be waiting on a number nobody has challenged yet.
Delay 3: Investor Review Is Still Pending
The servicer is often not the final decision-maker.
The company collecting documents and communicating with the agent may be servicing the loan for another investor. That investor may have its own rules for hardship, net proceeds, offer terms, seller contributions, closing costs, relocation assistance, or deficiency language.
This matters because a servicer can say the file is under review even when the decision is waiting somewhere else.
A good short sale negotiator should ask whether investor review is required, whether it has started, and whether any investor-specific conditions are open.
If the answer is vague, keep pushing for the active stage.
"Under review" is not enough.
Delay 4: Mortgage Insurance Has A Separate Say
Some loans have mortgage insurance involved. When they do, the mortgage insurance company may need to approve the short sale terms.
That can create a second layer of review.
The servicer may be comfortable with the package, but the mortgage insurance review may still be pending. This can affect seller contribution requests, closing costs, deficiency language, or approval timing.
That is why mortgage insurance can make a file feel complete but still stuck.
The best move is to identify it early. Ask whether mortgage insurance is involved and whether the file has been sent for that review.
Delay 5: Title Is Not Actually Clear
Title problems often appear late because everyone focuses on the lender first.
But a short sale approval letter is not enough if title cannot close.
Common title-related issues include:
- Junior liens.
- HOA balances.
- Tax liens.
- Judgment liens.
- Incorrect payoff figures.
- Missing releases.
- Probate or heirship issues.
- Name or ownership problems.
If title is not clean, the file may stall even after the lender has most of what it needs.
This is why title review should not wait until the approval letter arrives. If a lien problem is hiding in the file, it needs to be handled while the lender review is still moving.
Delay 6: The Buyer Or Offer Changed
Short sales take time, and buyers do not always stay still.
The buyer's lender may update requirements. Proof of funds may expire. The closing date may need to move. The buyer may ask for a credit or repair. The contract may need an addendum.
Any change can affect the short sale review.
The lender approved, or is considering, a specific deal. If the deal changes, the review may need to be updated.
That does not mean every buyer change kills the file. It means the change needs to be submitted cleanly, with the settlement statement and supporting documents matching the new terms.
Delay 7: Approval Letter Conditions Are Not Ready
Sometimes the file is close to approval, but the final letter is not ready because the lender is checking conditions.
The short sale approval letter may need to confirm:
- Approved sale price.
- Approved closing costs.
- Closing deadline.
- Seller contribution terms.
- Deficiency language.
- Relocation assistance terms.
- Junior lien payoff limits.
- Required buyer or title conditions.
If those terms are wrong, vague, or missing, the file can still be delayed.
This is why the approval letter should be reviewed carefully before everyone celebrates. A weak approval letter can create closing problems after the lender finally says yes.
What Agents Should Ask Instead Of "Do You Have Everything?"
"Do you have everything?" is not a strong enough question.
The answer may be yes, even if the file is not moving.
Better questions include:
- What review stage is active right now?
- Is the file in document review, valuation review, investor review, mortgage insurance review, or final approval?
- Are any documents expired or about to expire?
- Has the BPO or appraisal value been received?
- Is title review complete?
- Are there any open approval-letter conditions?
- What is the next follow-up date?
- What exact item would move the file forward today?
Those questions force the file out of vague status updates and into real next steps.
How A Short Sale Coordinator Keeps The File Moving
A short sale coordinator does not just send paperwork.
The coordinator keeps the moving pieces from drifting apart.
That includes tracking deadlines, matching documents, watching stale dates, following up with the servicer, flagging title issues, checking the buyer package, and making sure approval conditions are answered before they become emergencies.
The role matters because short sale files rarely fail all at once. They usually slow down one small missing item at a time.
When nobody owns the follow-up, those small items turn into weeks of delay.
When To Bring In Short Sale Help
Bring in short sale help when the file has been submitted but nobody can explain what is still pending.
That is the sign that the problem may not be missing paperwork. It may be unclear file control.
A short sale processor or short sale negotiator can help identify whether the blocker is:
- Document freshness.
- Hardship review.
- BPO value.
- Investor review.
- Mortgage insurance.
- Title.
- Buyer changes.
- Approval-letter conditions.
Once the real blocker is named, the file has a better chance of moving.
Bottom Line
A short sale can look complete and still be stuck.
That does not mean the deal is hopeless. It usually means the active review stage has not been identified clearly enough.
The best next move is not to resend the same documents blindly. It is to find the exact stage, condition, or approval layer that is holding the file in place.
That is how agents turn "we submitted everything" into a real plan for getting the short sale reviewed, approved, and closed.