

Short Sales in Hawaii: Why a Cooling Market Is Creating New Opportunities
Hawaii’s market is cooling, condos are stalling, and days on market are rising. Learn when short sales make sense in HI.
Hawaii’s real estate market has long been known for its resilience. Limited land, strong tourism, and high demand have historically kept prices elevated even when mainland markets softened. But as we move through late 2025, the data is starting to tell a more nuanced story.
Foreclosures are still relatively low compared to the rest of the country, but distress is quietly building beneath the surface. Inventory is lingering longer. Condo deals are falling apart. Sellers who expected quick closings are now facing longer timelines and shrinking buyer pools.
That’s exactly the type of environment where short sales begin to re-enter the conversation.
Foreclosures in Hawaii: Low, But Not Gone
Let’s start with the numbers.
In September and October of 2025, Hawaii recorded approximately 78 foreclosure filings statewide, which translates to about one foreclosure for every 7,242 housing units. On a national scale, that might not sound dramatic, but for a state with Hawaii’s traditionally tight market, it’s meaningful.
Earlier in the year, in April 2025, Hawaii ranked 44th nationwide for foreclosure filings, with roughly one foreclosure per 8,559 housing units. In other words, Hawaii is not a foreclosure hotspot, but distress is present and persistent.
This matters because foreclosure activity rarely spikes out of nowhere. It tends to trail broader market softening, and that softening is already visible across several segments of Hawaii real estate.
Market Softness Is Showing, Especially in Condos
One of the clearest warning signs in Hawaii right now is the condo market.
Across many islands, condo transactions are becoming harder to close. Contract cancellations are up, buyer hesitation is increasing, and inventory is sitting longer than it did just a year ago. More units are competing for fewer buyers, especially as financing costs and HOA concerns weigh heavily on affordability.
This creates a familiar pattern we’ve seen in other states:
• Sellers price aggressively based on last year’s comps
• Buyers hesitate or back out during escrow
• Listings sit longer, often requiring price reductions
• Mortgage balances remain high relative to market value
When a homeowner owes more than the property can realistically sell for in today’s conditions, a short sale becomes a viable exit strategy, even if foreclosure isn’t imminent.
Longer Days on Market Change Seller Psychology
Another key indicator is days on market.
Across Hawaii’s housing market in late 2025, days on market have increased. That shift alone doesn’t create short sales, but it changes expectations. Sellers who planned to sell quickly and move on are now facing months of uncertainty, continued carrying costs, and the risk of chasing the market downward.
This is often when sellers start asking different questions:
• “What if I can’t get my price?”
• “What happens if I can’t bring cash to closing?”
• “Is there a way to sell without defaulting?”
That’s where short sales come into play, especially for homeowners who still want to avoid foreclosure, protect their future options, and resolve the situation cleanly.
Why Short Sales Matter More in a Cooling Hawaii Market
Short sales aren’t just a foreclosure alternative. In markets like Hawaii, they serve a very specific role:
They allow homeowners to sell proactively, before distress becomes visible to everyone else.
In a slowing market, waiting too long can be costly. Values may soften further, buyers may grow more cautious, and lenders may become less flexible. A properly structured short sale gives sellers a way to exit with dignity while lenders recover as much value as possible.
For buyers and agents, short sales can also represent rare opportunities in a state where discounted inventory is historically limited.
The Importance of Professional Short Sale Handling
Short sales in Hawaii come with unique challenges. High property values, layered mortgages, condos with complex HOA structures, and out-of-state lenders can all complicate the process.
That’s why professional short sale negotiation and processing is critical.
At Crisp Short Sales, we specialize in handling every step of the process, from document preparation to lender negotiations. Our role is to remove friction from the transaction so deals actually close, not just look good on paper. If you want to understand exactly how we step in behind the scenes to make that happen, this overview of our short sale negotiation and processing services explains it in detail:
Who Benefits Most From Short Sales in Hawaii Right Now
We’re seeing increased short sale relevance across several groups in Hawaii:
• Condo owners facing declining values or stalled escrows
• Homeowners dealing with job changes or relocation
• Sellers who purchased near peak pricing
• Investors holding underperforming rentals
• Real estate agents navigating deals that keep falling apart
If you work with any of these groups, having a dedicated short sale partner can be the difference between a listing expiring and a transaction closing. We regularly support agents, investors, and homeowners across multiple states, including Hawaii. You can see the types of clients we typically work with here:
Timing Matters More Than Ever
In a market that’s cooling but not collapsing, timing is everything.
Waiting until foreclosure notices appear limits options. Starting the short sale process early gives lenders more flexibility and sellers more control. It also reduces stress and increases the odds of approval before market conditions worsen further.
If a homeowner suspects they may be upside down, or an agent sees a listing heading toward trouble, starting the conversation early is key. This is especially true in Hawaii, where even small market shifts can have outsized impacts due to high price points.
If you or someone you’re working with wants to explore whether a short sale makes sense, the first step is simple: start the process early and get clear answers. This process begins here:
Final Thoughts: Quiet Shifts Create Real Opportunities
Hawaii’s real estate market isn’t in crisis, but it is changing. Foreclosure activity exists, days on market are rising, condo deals are struggling, and sellers are facing realities they didn’t expect a year ago.
Those conditions don’t signal panic. They signal opportunity for informed sellers, prepared agents, and experienced short sale professionals.
Short sales may never dominate Hawaii’s housing landscape, but in moments like this, they play a critical role. Knowing when and how to use them can make all the difference.
Short Sales in Michigan: Why 2025 Is Becoming a Turning Point for Distressed Homeowners
Michigan foreclosures are rising: filings up 8% year-over-year with over 6,100 filings in the first half of 2025, and the Detroit metro area tops national lists. Our blog explains why short sales are increasingly important for homeowners and agents across the state.
Michigan is quietly re-entering the national conversation around foreclosure and distressed housing—and for homeowners, real estate agents, and investors, that shift matters.
While Michigan isn’t making daily headlines like it did during the Great Recession, the data from 2025 tells a clear story: financial pressure is building, foreclosure activity is rising, and more homeowners may soon need alternatives to foreclosure. One of the most effective—and often misunderstood—options is the short sale.
Let’s break down what’s happening across Michigan and why understanding short sales right now is critical.
Foreclosure Activity Is Rising Across Michigan
According to ATTOM’s Q2 2025 U.S. Foreclosure Market Report, Michigan foreclosure filings increased 8% year-over-year in the second quarter of 2025. That alone is notable—but the broader context is even more important.
In the first half of 2025, Michigan recorded over 6,100 foreclosure filings, placing the state among the top 15 states nationally for foreclosure activity. This isn’t isolated distress—it’s systemic pressure building across the housing market.
And the trend is especially pronounced in southeast Michigan.
Detroit Metro Area Leading the Increase
ATTOM’s Midyear 2025 Foreclosure Report shows the Detroit metro area ranking among the top U.S. metro areas for foreclosure starts this year. Filings are rising across:
- Wayne County
- Oakland County
- Macomb County
These are not fringe markets. These are core counties with large populations of homeowners who bought, refinanced, or modified loans during very different economic conditions than we see today.
When foreclosure starts rise in multiple neighboring counties at the same time, it typically signals that homeowners are falling behind faster than lenders can absorb the backlog.
Lenders Are Moving Faster Than Before
Another key signal in Michigan’s data: completed foreclosures (REOs) increased 17% year-over-year in mid-2025.
This matters because it shows lenders are no longer sitting on distressed loans indefinitely. Instead, they’re pushing files through the system—either to foreclosure sale or REO—once borrowers fall far enough behind.
For homeowners, this reduces the margin for error. Waiting too long can eliminate options that were available just months earlier.
This is exactly where short sales become a critical strategy.
Distressed Sales Are Back on the Map
Nationally, distressed sales—including foreclosures and short sales—now represent roughly 2% of all existing home sales, double their share from one year ago, according to the National Association of Realtors.
Midwest states like Michigan are contributing disproportionately to this increase.
That tells us two things:
- Distressed homeowners are returning to the market.
- Buyers and agents are encountering short sales more frequently than they have in years.
Understanding how to navigate them properly is no longer optional.
Why Short Sales Matter More in Michigan Right Now
A short sale allows a homeowner to sell their property for less than the total amount owed on the mortgage, with the lender’s approval. In many cases, it helps homeowners:
- Avoid foreclosure on their credit report
- Exit an unaffordable loan with dignity
- Relocate without the stigma of foreclosure
- Reduce or eliminate deficiency balances
From the lender’s perspective, a properly structured short sale often results in a better financial outcome than foreclosure—especially in markets where property values may not justify REO holding costs.
But short sales are not simple transactions. They require extensive documentation, lender negotiations, accurate valuations, and constant follow-up. This is where many Michigan deals fall apart—not because the seller or buyer did anything wrong, but because the process was underestimated.
That’s why many agents and homeowners rely on professional short sale coordination and negotiation support to keep deals moving forward. At Crisp Short Sales, this is exactly how we help distressed homeowners and agents navigate complex lender requirements.
What Michigan Homeowners Should Do If They’re Behind
If a homeowner in Michigan has received a notice of default, missed multiple payments, or is simply struggling to keep up, timing is everything. The earlier a short sale is evaluated, the more options exist. Once a foreclosure sale date is set—or worse, completed—those options shrink dramatically.
Starting the short sale process early gives homeowners a chance to:
- Understand lender expectations
- Prepare the right documentation
- Market the property properly
- Avoid last-minute emergencies
Homeowners can begin that process by understanding what lenders require and how the process works before foreclosure accelerates. This is why we guide sellers step-by-step when they’re ready to start a Michigan short sale.
What This Means for Michigan Real Estate Agents
Agents across Michigan are seeing more listings labeled “short sale,” “subject to lender approval,” or “bank negotiation required.” These deals can close—but only when they’re handled correctly.
Agents who succeed with short sales typically:
- Partner with experienced short sale negotiators
- Set realistic expectations with buyers
- Maintain consistent communication with lenders
- Avoid pricing and documentation mistakes
Crisp Short Sales works behind the scenes helping real estate agents close short sales faster while allowing them to focus on marketing and client relationships instead of lender portals and negotiation delays.
Michigan Is Early—But the Window Is Closing
Michigan’s distressed housing numbers are rising, but they’re not yet at crisis levels. That’s actually good news. It means homeowners, agents, and investors still have time to act proactively rather than reactively.
Short sales are most effective when they’re started early, structured properly, and managed by people who know how lenders operate today—not how they operated ten years ago.
As foreclosure filings continue to climb across Michigan in 2025, short sales will play an increasingly important role in helping homeowners exit difficult situations and helping transactions actually reach the closing table.
Short Sales in Rhode Island: Why More Homeowners Are Quietly Exploring Their Options
Rhode Island may be small, but rising foreclosure filings, serious delinquencies, and increasing distressed sales mean more homeowners are considering short sales. Providence leads New England’s foreclosure rates, and lenders are expanding loss mitigation efforts across the region.
Rhode Island may be one of the smallest states in the country, but when it comes to housing distress, the warning signs are getting harder to ignore.
Foreclosure activity is rising, mortgage delinquencies are increasing, and lenders across New England are quietly ramping up loss‑mitigation efforts. For Rhode Island homeowners who are feeling financial pressure, this moment matters. The decisions made now can determine whether a home is sold strategically through a short sale or lost to foreclosure later.
At Crisp Short Sales, we’re already seeing the early stages of this shift. Here’s what’s happening in Rhode Island’s housing market and why short sales are becoming an increasingly important tool for homeowners and agents alike.
Foreclosure Filings Are Rising Across Rhode Island
After several relatively quiet years, foreclosure filings in Rhode Island are moving upward again. According to the ATTOM U.S. Foreclosure Market Report, foreclosure filings in Rhode Island increased approximately 9% year‑over‑year in 2024 compared to 2023. While that number may sound modest at first glance, it represents a meaningful change in direction for a small state where market shifts tend to show up faster and hit harder.
Rhode Island’s housing market doesn’t have the same volume cushion as larger states. Even small increases in distress can quickly affect pricing, buyer confidence, and lender behavior.
Providence Metro Is Emerging as a Foreclosure Hot Spot
The trend becomes even clearer when you zoom in on the Providence metro area.
The Providence–Warwick metro recorded roughly one foreclosure filing for every 1,900 housing units in late 2024, placing it among the highest foreclosure rates in New England, according to ATTOM Metropolitan Foreclosure Rankings.
That concentration matters. Foreclosure activity tends to cluster, and once it does, nearby homeowners often feel the ripple effects through declining property values, stricter buyer underwriting, and slower transaction timelines.
This is often the point where proactive sellers start asking an important question: Is there a way out before foreclosure becomes unavoidable?
Mortgage Delinquencies Signal What’s Coming Next
Foreclosures rarely come out of nowhere. They’re usually preceded by months of missed payments and growing financial strain.
Throughout 2024, Rhode Island saw an increase in serious mortgage delinquencies (90+ days past due), according to the CoreLogic Mortgage Delinquency Trends Report. This category is widely considered one of the strongest leading indicators of future short sales.
When homeowners fall that far behind, lenders typically begin reviewing alternatives to foreclosure. Short sales often become a viable option during this window, especially when the property value no longer supports a traditional sale.
This is where timing becomes critical. Waiting too long can reduce options, while early action can preserve control and equity where possible.
Distressed Sales Are Rising Nationally, and Small States Feel It First
On a national level, distressed sales are making a comeback.
The National Association of Realtors’ 2025 Housing Outlook reports that distressed transactions (short sales and foreclosures) now represent about 2% of all U.S. home sales, up from roughly 1% the year before. While that figure is still far below crisis‑era levels, the doubling year‑over‑year is notable.
For smaller states like Rhode Island, these national shifts tend to be amplified. Limited inventory, fewer buyers for distressed homes, and localized economic pressure can all accelerate the need for structured solutions like short sales.
Lenders Are Quietly Increasing Loss‑Mitigation Reviews in New England
Behind the scenes, lenders are already adjusting.
According to the Mortgage Bankers Association National Delinquency Survey, lenders reported increased loss mitigation activity across New England in late 2024, including reviews for short sales, loan modifications, and deeds‑in‑lieu.
This is an important signal. Lenders don’t expand these departments unless they expect more files to come through.
For Rhode Island homeowners, it means banks are increasingly open to alternatives that avoid foreclosure when presented correctly.
The key phrase there is presented correctly.
Why Short Sales Matter More Than Ever in Rhode Island
A short sale allows a homeowner to sell their property for less than the mortgage balance with the lender’s approval. When handled properly, it can:
• Avoid foreclosure and its long‑term credit damage
• Reduce or eliminate deficiency risk
• Provide a cleaner exit during financial hardship
• Allow more dignity and control during the sale process
But short sales are not DIY transactions. They require detailed financial packaging, lender negotiation, and constant follow‑up to prevent delays or denials.
That’s where professional short sale processing and negotiation becomes critical. At Crisp Short Sales, we handle the heavy lifting behind the scenes, from financial document prep to lender communication and approval strategy. You can learn more about how we guide homeowners and agents through this process on our How We Help page.
Helping Rhode Island Agents and Homeowners Close, Not Just List
Short sales don’t fail because there’s no buyer. They fail because the process breaks down.
We work directly with listing agents, buyers, and lenders to keep files moving and deals alive. If you’re an agent navigating distressed listings or a homeowner unsure of your next step, our role is to stabilize the transaction so it actually reaches the closing table.
You can see who we typically support and how those relationships work here.
And if you’re ready to explore whether a short sale makes sense for your Rhode Island property, the best first step is starting the process early.
The Bottom Line for Rhode Island in 2025
Rhode Island is not in a foreclosure crisis, but it is clearly in a transition period.
Rising delinquencies, increasing foreclosure filings, and expanded lender loss‑mitigation efforts all point to one conclusion: short sales are becoming a more relevant and necessary solution again.
Homeowners who act early have options. Agents who understand the process can protect their clients and their commissions. And lenders are more willing to negotiate when files are properly positioned.
In a small market like Rhode Island, knowing when and how to use a short sale can make all the difference.
Short Sales and Foreclosures in Montana: What Homeowners Need to Know in 2025
When people think of housing distress, Montana is not usually the first state that comes to mind. With wide-open spaces, smaller population centers, and historically stable housing markets, many homeowners assume foreclosure issues are a big-city problem.
But 2025 is telling a different story.
Foreclosure activity is rising nationwide, and Montana is beginning to feel that pressure as well. For homeowners who are behind on payments or worried about what comes next, understanding short sales and foreclosure options early can make the difference between damage control and long-term financial harm.
Let’s break down what’s happening in Montana and what homeowners should know right now.
Foreclosures Are Rising Nationwide and Montana Is Not Immune
Across the U.S., foreclosure filings are climbing again after several relatively quiet years.
Nationally, foreclosure filings rose approximately 17–20% year-over-year through late 2025 compared to 2024. This increase reflects broader market stress driven by higher interest rates, rising living costs, insurance increases, and tighter lending standards.
Smaller states like Montana often feel these shifts a little later than major metros, but they still feel them. And now, Montana’s data is catching up.
Montana Foreclosure Activity Is Increasing Year-Over-Year
Recent foreclosure data shows a clear upward trend in Montana:
- February 2025: Montana recorded 21 total foreclosure filings, representing roughly a 5% year-over-year increase compared to the same period the prior year.
- September 2025: Montana saw 47 foreclosure filings, translating to a foreclosure rate of 1 in every 11,126 housing units.
- Most notably, September filings reflected an estimated 113% year-over-year increase compared to September 2024.
Those numbers may look small compared to states like Florida or California, but for Montana’s housing market, the percentage increases are meaningful. They indicate growing pressure on homeowners who may have been stable just a year or two ago.
Why Foreclosures Are Rising in Montana
Several factors are contributing to the increase:
- Higher mortgage payments for homeowners with adjustable-rate loans
- Rising property taxes and insurance costs, especially in rural and wildfire-prone areas
- Job instability tied to seasonal employment, tourism, and agriculture
- Limited buyer pools in certain rural markets, making traditional sales harder when time is tight
When homeowners fall behind, many assume foreclosure is automatic or unavoidable. That is not true. This is where short sales come in.
What Is a Short Sale and How Does It Work in Montana?
A short sale allows a homeowner to sell their property for less than what is owed on the mortgage, with the lender’s approval. Instead of going through foreclosure, the lender agrees to accept the sale proceeds as full or partial satisfaction of the debt.
In Montana, short sales can be a powerful alternative when:
- The home is worth less than the mortgage balance
- The homeowner is behind or about to fall behind on payments
- A traditional sale will not cover closing costs and loan payoff
- Foreclosure timelines are approaching
A properly handled short sale can help homeowners avoid foreclosure, minimize credit damage, and move on with less financial fallout.
Why Timing Matters More Than Ever
One of the biggest mistakes homeowners make is waiting too long.
Foreclosure filings often start quietly, with notices and deadlines that are easy to ignore. But once a foreclosure sale date is scheduled, options shrink quickly.
Starting early gives more flexibility:
- More time to negotiate with the lender
- More buyer options
- Less stress and fewer emergency decisions
This is why working with professionals who understand short sale negotiation and lender approval processes is critical. Many real estate agents do not handle these files regularly, and lenders will not guide homeowners through the process.
At Crisp Short Sales, this is exactly where we step in. Our team focuses exclusively on short sale processing and negotiation, working behind the scenes with lenders so homeowners and agents do not have to manage that complexity themselves. You can learn more about how we handle lender negotiations and approvals through our short sale support services on our How We Help page.
How Short Sales Can Help Montana Homeowners Avoid Foreclosure
A successful short sale can offer several benefits:
- Stops or pauses foreclosure proceedings
- Avoids the public stigma of a foreclosure auction
- Often results in less long-term credit damage
- Allows for a more controlled move-out timeline
- In some cases, provides relocation assistance at closing
Short sales are not “easy,” but they are often far better than foreclosure when handled correctly. If you are a homeowner in Montana dealing with missed payments, or a real estate agent with a distressed listing, getting expert help early is key. We regularly work with homeowners and agents nationwide through our short sale assistance for realtors and sellers, outlined on our Who We Serve page.
Montana Homeowners Still Have Options in 2025
The rising foreclosure numbers do not mean Montana is in crisis, but they do signal a shift. More homeowners are feeling financial strain, and ignoring it rarely leads to good outcomes.
If you or someone you know is facing foreclosure in Montana, a short sale may still be possible even after a notice has been filed. The key is acting before deadlines close the door.
If you are unsure where to start, the first step is simply understanding your options. You can begin that process by reaching out through our Start a Short Sale page and getting clear guidance on what makes sense for your situation.
Foreclosure does not have to be the end of the story. With the right timing and support, many Montana homeowners can still take control of the outcome.
Short Sales and Foreclosures in Delaware: What Homeowners and Agents Need to Know in 2025
Delaware foreclosure filings are rising. Learn how short sales work, foreclosure trends, and how homeowners and agents can act early.
Delaware may be one of the smallest states in the country, but it’s no longer flying under the radar when it comes to housing distress. New data from 2025 shows a clear uptick in foreclosure activity and distressed inventory, especially in a judicial state like Delaware where timelines can stretch and pressure quietly builds behind the scenes.
For homeowners facing hardship and real estate agents managing distressed listings, understanding how short sales and foreclosures intersect in Delaware has never been more important.
Foreclosure Activity Is Rising in Delaware
- Foreclosure filings in Delaware increased 10% year-over-year in Q2 2025 compared to Q2 2024
- 1 in every 1,497 housing units in Delaware had a foreclosure filing in the first half of 2025
- Foreclosure starts increased across the Mid-Atlantic region, signaling renewed distressed inventory
- Completed foreclosures nationally rose 18% year-over-year, creating downstream pressure in judicial states like Delaware
- Distressed sales now account for roughly 2% of existing-home sales nationwide, double the prior year
In judicial states, that combination matters. More foreclosure starts plus slower court timelines often lead to more short sale opportunities, but only if the process is handled early and correctly.
Delaware’s Judicial Foreclosure Process Creates a Window — and a Risk
Delaware requires lenders to pursue foreclosure through the court system. While this provides homeowners more time than non-judicial states, it also creates a false sense of security.
Once a foreclosure complaint is filed:
- Legal costs accumulate
- Notices become public record
- Sheriff sale timelines begin forming
- Negotiation leverage gradually erodes
This is where many homeowners wait too long, assuming they still have plenty of time. In reality, the best options often exist months before a sale date is scheduled.
That window is exactly where short sales work best.
How Short Sales Work in Delaware
A short sale allows a homeowner to sell their property for less than the total mortgage balance, with lender approval, instead of going through foreclosure.
In Delaware, short sales are commonly used to:
- Stop a foreclosure already in progress
- Avoid a sheriff sale and public auction
- Reduce long-term credit damage
- Exit the property with dignity and control
However, Delaware short sales come with challenges:
- Judicial timelines that vary by county
- Multiple liens including HELOCs, HOA balances, or tax liens
- Investor-specific rules that override servicer guidelines
- Lenders requiring complete, error-free submissions
That’s why many homeowners rely on experienced short sale processing and negotiation support, like the lender-facing services outlined in how we help homeowners navigate short sales and approvals at How We Help.
Short Sale vs Foreclosure in Delaware
Foreclosure
- Court-driven process
- Public record and sheriff sale
- Severe, long-lasting credit impact
- Little homeowner control
Short Sale
- Marketed sale with buyer involvement
- Negotiated lender approval
- Less damaging credit outcome
- More flexibility and privacy
With foreclosure filings rising statewide, short sales are increasingly becoming the preferred alternative when handled early enough.
Why Delaware Agents Are Leaning on Short Sale Coordinators
As distressed sales now represent a growing share of closings, many Delaware agents are realizing that short sales fail more often from poor coordination than from pricing.
Common breakdowns include:
- Missing or outdated financial documents
- Inexperienced lender communication
- Buyers walking due to slow approvals
- Title issues discovered late
This is why more agents partner with specialists who focus exclusively on short sale coordination, lender negotiation, and approval management, allowing the agent to focus on marketing and buyer communication.
Our services are specifically designed for professionals helping real estate agents close short sales faster, which is why agents turn to our solutions on the who we serve page.
Can Delaware Homeowners Receive Money at Short Sale Closing?
In some cases, yes.
Depending on the loan type, investor, and hardship, homeowners may qualify for relocation assistance paid at the closing of a short sale. These funds can help cover moving expenses and reduce the financial shock of transition.
This is not automatic. It must be requested, justified, and negotiated properly as part of the lender approval process.
Timing Matters More Than Ever in 2025
With foreclosure starts rising and distressed inventory increasing, early action preserves options.
The best time to start a Delaware short sale is:
- After hardship begins, not after sheriff sale scheduling
- As soon as foreclosure notices are filed
- While buyer interest and lender flexibility still exist
If foreclosure is already looming, starting early can still make the difference between approval and auction.
Homeowners and agents can review next steps on how to start a short sale properly at Start a Short Sale.
Final Thoughts
Delaware’s foreclosure numbers are trending upward, but foreclosure is not inevitable. In a judicial state, time can be either your greatest asset or your biggest risk.
With the right strategy, documentation, and lender negotiation, short sales remain one of the most effective tools for homeowners and agents navigating distress in 2025.
Kentucky Foreclosures Are Rising in 2025: What Homeowners, Agents, and Title Companies Need To Know About Short Sales
If you work in Kentucky real estate — whether you’re a homeowner worried about falling behind, a listing agent trying to keep deals alive, or a title company staring at more delayed closings — you’ve probably noticed something: distress is rising again across the Commonwealth.
And the numbers back it up.
Kentucky logged 1,722 foreclosure filings in the first half of 2025, affecting 1 in every 1,168 homes statewide. That’s up 4.7 percent year-over-year, but the bigger story is the long-term trend: filings are up a stunning 80.7 percent compared to the first half of 2023.
In other words — yes, there’s more trouble in the pipeline. But the good news is that short sales are becoming a faster, more predictable alternative for everyone involved, and that’s exactly where a service like Crisp Short Sales shines.
Let’s break down what’s happening across Kentucky and how short sales are helping homeowners, agents, and title teams keep deals moving.
---
Kentucky Foreclosures: The 2025 Picture
Foreclosure activity in Kentucky has been steadily rising for almost two years, and the monthly data shows the trend isn’t slowing:
• September 2025: 234 properties had a foreclosure filing
• Foreclosure starts: 129 new starts that month — up 40.2 percent year-over-year
• October 2025: 329 total filings statewide, or 1 in every 6,111 homes
• End of 2024 baseline: 253 filings, or 1 in every 7,902 homes
Kentucky currently ranks 32nd nationally in foreclosure rate — not the worst, but the acceleration matters. It means lenders are moving more quickly, and homeowners have less time to navigate their options.
Another sign of what’s ahead? Delinquencies.
As of December 2024:
• 3.2 percent of Kentucky mortgages were 30+ days late
• 1.0 percent were 90+ days late
That’s significantly higher than many other states and signals a growing pool of at-risk homeowners who may not be able to catch up.
For agents, that means more listings where equity isn’t quite what the seller hoped. For title companies, it means more payoff issues, more delays, and more files needing specialized help.
---
Where Distress Is Rising the Most in Kentucky
While foreclosure activity is rising statewide, a few counties are driving the majority of filings:
• Jefferson County (Louisville) — highest volume of filings in the state
• Fayette County (Lexington) — steady YOY increases, many FHA loans underwater
• Kenton County — inherited homes and older housing stock adding pressure
• Boone & Warren Counties — rising default activity as ARMs reset and costs rise
These markets are also where we see the most short sale opportunities — and where homeowners and agents can avoid foreclosure damage if they act early.
---
Why More Kentucky Homeowners Are Considering a Short Sale
Short sales are gaining traction in Kentucky for a few reasons:
- Equity Isn’t What People Think
Many homes purchased between 2019–2022 are worth less today than the homeowner expected — especially if repairs are needed.
- FHA Loans Are Common
Kentucky has a large FHA buyer pool. Between MIP and payoff totals, many sellers discover they’re upside-down once a payoff order hits the title company’s inbox.
- Higher Living Costs Are Catching Up
Insurance, utilities, food, and maintenance costs have risen faster than wages. When payments fall behind, homeowners are reaching out sooner.
- ARM Resets + Deferred Maintenance
Older properties with deferred repairs or loans that are adjusting are showing up more frequently in pre-foreclosure.
This combination is exactly why short sales are becoming the preferred path for homeowners and agents who want a softer landing — and a clean closing.
---
How Short Sales Help in a Rising-Foreclosure Environment
For Homeowners
A short sale prevents foreclosure, protects credit far better, and often includes help with the logistics of moving. At Crisp Short Sales, we regularly secure seller relocation assistance at closing, giving families the ability to move forward without financial ruin. You can learn more about how we do this on our page explaining how we help homeowners navigate approvals and relocation incentives.
For Real Estate Agents
Agents in Kentucky are carrying more listings where the math just doesn’t pencil out. A short sale allows you to keep the listing, keep the client relationship, and still bring the deal to the finish line. And when you’re working with a team that specializes in helping real estate agents close short sales faster, you don’t have to spend hours negotiating with lenders or dealing with their document demands.
For Title Companies
Payoffs are getting harder — higher escrow shortages, rising fees, and underwater balances. A well-run short sale takes those problems off your plate:
• No more last-minute lender surprises
• No more payoff figures that don’t align with contract dates
• No more guessing what the bank wants
Our job is to get the approval letter issued correctly and on time, so your closing can stay on track.
---
Why a Kentucky Short Sale Is Often Faster in 2025
Lenders nationwide are pushing to close files faster, automated document systems are finally improving, and banks are hiring more loss-mitigation staff. The result? Short sale approvals are moving faster than they were just a few years ago.
And when homeowners start early, the process becomes even smoother. Agents can initiate a file by sending clients to our streamlined intake form at Crisp Short Sales, where we handle everything from document prep to lender follow-up. Start a short sale today.
---
The Bottom Line: Kentucky’s Distress Is Rising — but The Right Help Keeps Deals Alive
Foreclosures are trending upward across Kentucky, and the data points to even more coming in 2026. But most of these homeowners can still avoid foreclosure entirely — and agents and title companies can keep transactions from collapsing — if a short sale is started early.
Kentucky’s market favors proactive decision-making. Whether it’s a homeowner struggling with payments or a title company trying to make a payoff work, a well-managed short sale offers a clean, controlled path to closing.
If you're dealing with a property in pre-foreclosure or already listed under market value, this is the time to explore your options. And if you're an agent or settlement team member trying to keep a transaction from falling apart, you don’t have to solve it alone.
Crisp Short Sales is here to help — and we keep the process moving from start to finish.
---
The Hidden Costs Idaho Homeowners Face When They Try to Avoid Foreclosure — and How a Short Sale Fixes Them
Foreclosure filings nearly doubled in Idaho in October 2025, and mortgage delinquencies and affordability pressures are rising across the state. Learn why many homeowners are better off pursuing a short sale than facing foreclosure.
Idaho has spent years being labeled a “low-distress” state, but 2025 is telling a very different story. Foreclosure filings are rising, mortgage delinquencies are climbing, and affordability has pushed many homeowners into a corner where tough decisions can’t be ignored anymore.
But here’s the good news: most Idaho homeowners don’t actually need to go through foreclosure — even if they’re behind, underwater, or facing financial pressure. A well-managed short sale can offer a clean, controlled exit from a stressful situation, protect long-term credit, and often put money back into the homeowner’s pocket at closing.
Let’s break down what’s happening across Idaho — and why a short sale is becoming the smartest option for more families in 2025.
## Idaho Foreclosures Nearly Doubled — And That Signals a Bigger Problem
Here’s the headline homeowners keep seeing in the *Idaho Statesman* and *Coeur d’Alene Press*: **Foreclosure filings almost doubled statewide in October 2025.**
- **206 Idaho properties** entered foreclosure
- That’s a **94 percent increase year-over-year**
- It marks the **3rd-largest foreclosure spike in the entire U.S.**
A jump that sharp isn’t random — it’s the result of mounting financial pressure, rising mortgage delinquencies, and affordability issues that have been building for months.
**What this means for homeowners:** Many are waiting too long to explore options, and by the time the sale deadline arrives, foreclosure feels inevitable. But in almost every one of these situations, a short sale could have stopped the foreclosure clock while giving the homeowner more control.
## Idaho Now Ranks Among the Highest States for Foreclosure Starts
Idaho doesn’t just have more filings — **it’s now one of the fastest-rising states for new foreclosure starts.**
- **13th highest foreclosure start rate in the U.S.**
- Roughly **1 in every 3,770 properties** received a foreclosure start
- Slightly worse than the national average of **1 in 3,781**
This is one ranking where Idaho homeowners want to be nowhere near the top — but again, this increase reflects an opportunity.
Lenders in rising-distress states often become *more receptive* to alternatives like short sales. By showing hardship and a legitimate market-based offer, a homeowner can typically avoid foreclosure entirely and transition out of the property with dignity — often with *relocation assistance* or other **money at closing** via programs connected to homeowner-support incentives (a great place to learn more is our page on [how we help homeowners navigate complex short sale situations](/how-we-help)).
## Foreclosure Filings Were Already Elevated Going Into October
The October spike didn’t come out of nowhere.
Back in September 2025:
- Idaho recorded **102 foreclosure filings**
- That equals **1 filing for every 7,615 housing units statewide**
- Meaning filings were already climbing before October’s surge
For distressed homeowners, this means one thing: **you’re not alone — and you’re not early to the problem.** Idaho’s housing market is shifting, and many homeowners are facing circumstances they didn’t expect after years of rapid appreciation and competitive buying.
The best move is to get ahead of the timeline, not wait for the sale date to catch up.
## Delinquent Mortgages Are Quietly Building Future Short Sale Pressure
Most Idaho homeowners who end up in foreclosure don’t start there. They start with a missed payment… then another… then an unavoidable hardship.
Right now:
- **1.9 percent of Idaho mortgages are 30+ days delinquent**
- That’s higher than the sub-2% range earlier in the cycle
- And it signals a wave of future short sales and foreclosure filings
Delinquencies are one of the clearest predictors of short sale volume, and lenders know this. That’s why they often prefer a clean, well-packaged short sale instead of carrying a non-performing loan indefinitely.
This is exactly where having a **short sale expert** (like us — and here’s how we [work directly with real estate agents to close short sales faster](/who-we-serve)) makes all the difference.
## Affordability Stress Is Crushing Key Idaho Metros
Idaho homeowners aren’t struggling because they’re careless — they’re struggling because housing costs have simply outpaced income growth.
Consider this:
- In **Boise**, a median-income household needs **44 percent of monthly income** just to afford a median-priced home.
- In the **Hailey** area? A staggering **95 percent** of income goes toward a median home payment.
No budget survives that kind of pressure for long. When affordability reaches these levels, even responsible homeowners with steady income can fall behind.
A short sale doesn’t erase the hardship, but it *does* give homeowners a way out that preserves their ability to recover financially.
## Why a Short Sale Beats Foreclosure for Most Idaho Homeowners
Here’s what a short sale can do that foreclosure simply can’t:
1. **Stop the foreclosure process.** Once a buyer is found and the lender reviews the short sale package, the foreclosure timeline is typically paused.
2. **Protect credit better than a foreclosure.** A short sale is far less damaging on a credit report than a completed foreclosure.
3. **Eliminate deficiency liability.** Many Idaho homeowners walk away **owing nothing**, even if they’re tens or hundreds of thousands underwater.
4. **Potential relocation assistance.** Lenders regularly offer **cash at closing** to help homeowners move — something foreclosure will never provide.
5. **A faster path back to homeownership.** After a short sale, many Idaho homeowners are able to buy again in 2–3 years.
After a foreclosure, that timeline is much longer.
## The Bottom Line for Idaho Homeowners in 2025
Foreclosures are rising fast, affordability is stretched thin, and lenders are already bracing for more distress ahead.
But Idaho homeowners still have choices — and a well-managed short sale is often the cleanest, fastest, and most financially beneficial exit available.
If you’re an Idaho homeowner, agent, or investor looking for **short sale approval assistance**, this is exactly what we do every day at Crisp Short Sales. You can start a short sale immediately using our secure intake form here: [start the short sale process today](/start-short-sale).
Why Wisconsin Homeowners Are Turning to Short Sales in 2025: Market Shifts, Foreclosure Trends, and What Agents Should Know
WI foreclosures are rising. Learn why short sales are increasing in 2025 and how homeowners, agents, and title companies can benefit.
Wisconsin may be known for cheese curds, Friday fish fries, and football rivalries, but lately another topic has been dominating conversations with homeowners and real estate professionals across the state: rising mortgage distress.
And the numbers don’t lie.
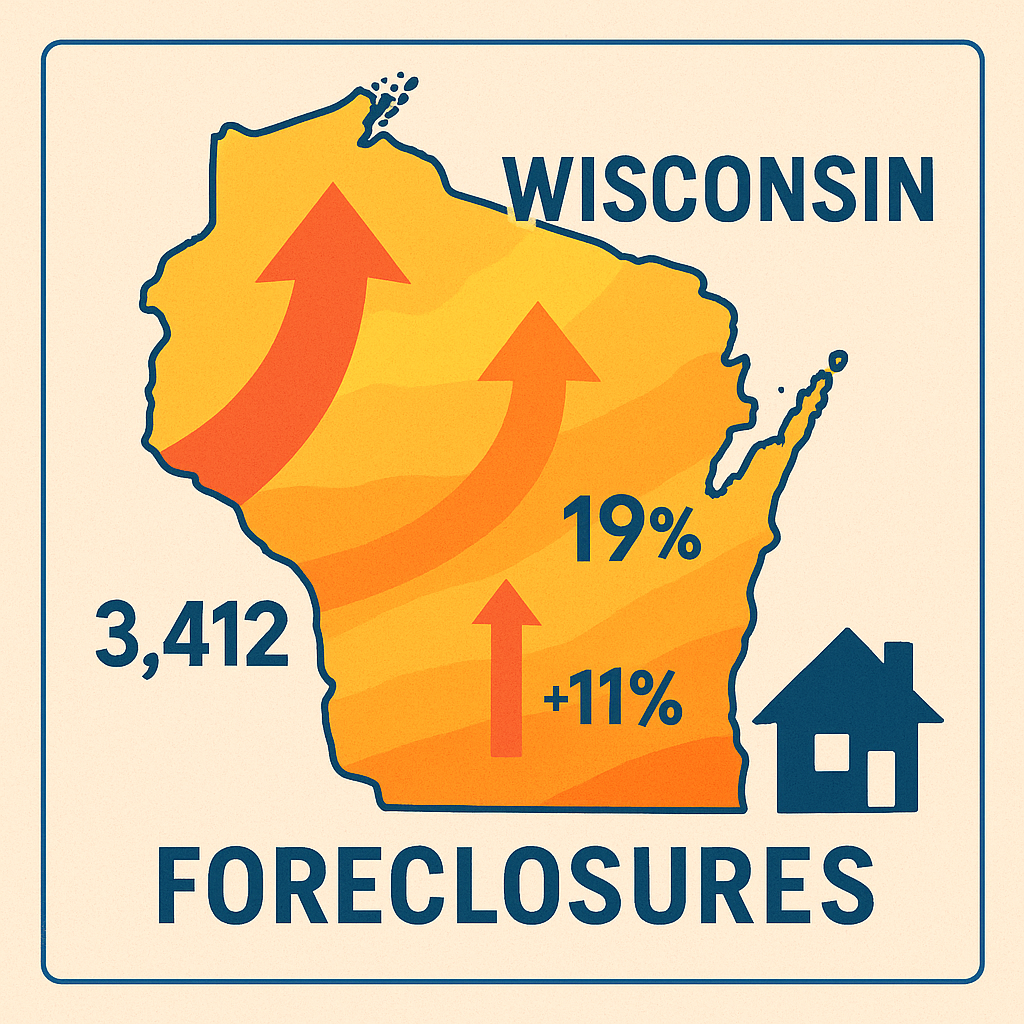
According to the ATTOM Midyear 2025 U.S. Foreclosure Market Report, Wisconsin foreclosure filings rose 11 percent year-over-year in the first half of 2025, totaling 3,412 filings — one of the highest foreclosure counts in the Midwest. Metro areas like Milwaukee, Madison, and Green Bay are seeing the pressure even more acutely, and that shift is pushing more homeowners to explore alternatives long before a sheriff’s sale becomes reality.
If you’re a homeowner, real estate agent, or title company navigating these changing conditions, short sales are becoming one of the most important tools to understand — and one of the best ways to prevent deals from falling apart.
Milwaukee Leads the State’s Distress Spike
Foreclosure starts in the Milwaukee metro jumped 19% year-over-year as of Q2 2025 (RealtyTrac / ATTOM Metro Foreclosure Activity Summary). That means more homeowners are entering the earliest stages of mortgage default, whether due to job changes, rate resets, medical expenses, or simply falling behind after months of financial strain.
At the other end of the pipeline, Wisconsin REO completions rose 15% year-over-year in 2025. When bank-owned properties rise, it signals one thing: lenders are pushing more distressed files through to completion. That means fewer delays, fewer extended timelines, and fewer second chances for homeowners hoping to avoid foreclosure.
For families facing hardship, the window for solutions is tightening — and for many, a short sale is the lifeline that prevents a full foreclosure from hitting their credit for seven years.
For agents and title partners, this means one thing: more distressed listings… and more transactions that need reliable short sale processing to close smoothly.
Madison & Green Bay Are Quietly Becoming Foreclosure Hotspots
It’s not just Milwaukee feeling the squeeze.
In the 2025 ATTOM Metro Foreclosure Rate Rankings, both Madison and Green Bay were listed among the top 20 midsize U.S. markets for rising foreclosure rates.
These aren’t markets typically associated with major housing distress, which means:
- Many homeowners don’t recognize the early warning signs
- Many agents haven’t handled a short sale recently
- Title companies may see sudden surges in complex, lender-driven transactions
That’s exactly where having an experienced short sale partner becomes valuable. A short sale requires precise document handling, weekly lender follow-ups, valuation challenges, and constant communication — all the things that bog down a transaction if not managed proactively.
At Crisp Short Sales, we specialize in helping homeowners avoid foreclosure far more efficiently, while also helping real estate agents close short sales faster by taking the negotiation workload off their plate. Our goal is simple: keep deals alive and moving, even when lenders slow things down.
Why More Wisconsin Homeowners Are Choosing Short Sales in 2025
- Loan balances are outpacing property values in certain pockets
Competition cooled, rates climbed, and some owners who bought in 2021–2023 at peak prices now owe more than their home can sell for — especially if repairs have been deferred.
A short sale allows them to sell without bringing money to closing, avoid foreclosure, and in many cases walk away with assistance to help with relocation. That assistance is handled through the lender at closing, and we coordinate those details as part of how we help homeowners through the short sale process — with minimal stress and no out-of-pocket costs.
- Lenders are moving files through faster
The rise in REOs shows banks are less patient with delinquent borrowers. But when a properly packaged short sale is submitted, the lender often prefers it over foreclosure because it:
- Reduces legal costs
- Reduces property maintenance costs
- Gets the asset off their books faster
A well-managed file can get approved far more quickly when handled by a short sale expert, especially when agents and title partners have someone pushing lenders each week.
- It preserves homeowner dignity and future buying power
A foreclosure is devastating to a credit report. A short sale is difficult, yes, but it is:
- Faster to recover from
- Better for future lending
- More respectful to the homeowner’s situation
And Wisconsin families deserve every opportunity to move forward without a years-long financial penal
Learn more about how we help homeowners through the short sale process. more about how we help homeowners through tshort sale process.ss.ty.
What Wisconsin Real Estate Agents Should Know
If you’re handling a listing that might be a short sale, here’s your biggest advantage: you don’t have to negotiate it yourself.
Short sales can overwhelm even experienced agents. That’s why hundreds of agents nationwide partner with specialists like us who manage:
- Full document collection
- File setup and lender submission
- Weekly follow-ups with the bank
- Valuation disputes
- Approval letter review
- Coordination with title and buyers
We work behind the scenes while you stay focused on the relationship and the sale — and you remain in full control of your listing. If you want a partner who specializes in short sale coordination, you can learn more about who we serve at Crisp Short Sales, including realtors throughout Wisconsin.
Learn more about who we serve at Crisp Short Sales.
Why Title Companies in Wisconsin Benefit Too
Title officers are often stuck waiting for approval letters, lien releases, and lender conditions that slow closing timelines.
A proactive, experienced negotiator keeps the file moving, updates everyone weekly, and ensures title is prepared long before the lender issues final approval. That means faster closings and fewer surprises.
Submitting your file through our streamlined online form
helps us get a jump on everything the lender needs — saving you time and helping everyone reach the closing table faster.
Final Takeaway: Wisconsin’s Distress Market Is Growing — But So Are the Solutions
Rising foreclosure activity doesn’t have to lead to foreclosure outcomes. Whether you’re a homeowner, agent, or title company, the smartest move you can make in 2025 is understanding how a short sale works — and partnering with someone who does this every single day. Wisconsin’s market is shifting quickly, but with the right support, distressed properties can still lead to successful, fully closed transactions.
From Filing to Closing: Understanding Arkansas Foreclosure Trends and When a Short Sale Is the Better Option
Arkanas is seeing some of its sharpest distressed-property activity in years, and everyone involved in the process — homeowners, agents, and title companies — is feeling the shift.
Foreclosure filings across the state rose **13 percent year over year in the first half of 2025**, according to ATTOM’s Midyear Foreclosure Market Report. That bump alone would get attention, but Arkansas is also seeing **1 in every 1,621 housing units** receive a foreclosure filing — a meaningful sign that default activity is spreading into more markets and price points.
And in the Little Rock metro? Things are moving even faster. **Foreclosure starts jumped 19 percent in Q2 2025**, making it one of the more rapidly accelerating distressed markets in the Southeast. Add in the **11 percent rise in REO (bank-owned) properties statewide**, and it’s no surprise that distressed sales — short sales plus foreclosures — now make up **1.8 percent of all Arkansas residential transactions**, up from 1.1 percent last year.
So what does this mean for homeowners facing financial hardship?
For agents fielding increasingly complex listings?
For title companies trying to keep files moving toward the finish line?
It means the window for action is tightening — and understanding when a short sale is the better path can be the difference between a smooth transition and a costly foreclosure.
## Why Short Sales Matter More Than Ever in Arkansas
Foreclosure trends tell us one clear thing: families are struggling earlier in the pipeline, and banks are pushing files forward faster. For many Arkansas homeowners, the foreclosure timeline feels confusing, intimidating, and abrupt. That’s why starting the short-sale conversation early matters.
A well-run short sale helps homeowners avoid foreclosure entirely, protects credit, and often provides a far cleaner exit strategy. When homeowners work with a partner experienced in helping them navigate the process and secure relocation assistance or other closing incentives, the experience shifts from crisis to clarity. (See how we help: helping homeowners navigate short sales smoothly)
For agents, short sales offer something critical during times of rising distressed activity: control. Instead of letting a listing drift toward foreclosure, you can present a viable alternative, maintain your relationship with the seller, and guide the transaction with confidence. Our role is to handle the lender side so you can focus on what you do best —helping real estate agents close short sales faster and with fewer surprises. With. distressed sales up to **1.8 percent** statewide, it’s becoming essential to have a clear process and a reliable point of contact who can keep communication flowing, deliver documents on time, and resolve lender conditions before they threaten closing. The smoother the negotiation, the cleaner your workflow — and the more confident your client relationships remain.
## From Filing to Closing: What Arkansas Homeowners Should Expect
Every Arkansas county handles foreclosure a bit differently, but the big picture is consistent statewide: once filings begin, the process moves faster than most homeowners expect.
Here’s the simplified flow:
1. **Missed payments trigger early intervention**
Banks send reminders, late notices, and loss-mitigation letters. Most homeowners don’t realize they can start a short sale right here — before things escalate.
2. **Foreclosure filing hits public record**
This is the moment when homeowners feel the most pressure. With filings up 13 percent, more families are seeing their situations move from private to public faster.
3. **Foreclosure starts (especially rising in Little Rock)**
A 19 percent rise in starts means banks are initiating formal action more quickly. This is the last safe moment to begin a short sale before the process becomes much harder.
4. **Sale scheduled**
Once a sale date is posted, the clock is ticking. A short sale is still possible — but only with a negotiator who knows how to get emergency reviews, escalations, and approvals.
5. **REO / bank-owned stage**
At this point, the homeowner has lost the property and options shrink dramatically. Arkansas saw an 11 percent year-over-year rise in REOs, meaning more families are hitting this stage because they didn’t get help early enough.
A short sale can prevent foreclosure at multiple points — but starting earlier always leads to better outcomes.
## Why Agents, Investors, and Title Companies Are Leaning More on Specialized Short Sale Support in 2025
A rising distressed market doesn’t just affect homeowners — it strains every professional in the transaction chain.
### For Agents
More complex listings, more lender delays, more paperwork, more emotional clients. Having a partner who handles the lender side gives you margin to manage pricing, marketing, showings, and negotiations without drowning in bank emails.
### For Title Companies
Short sales require constant status updates, condition tracking, approval letter review, HOA coordination, and payoff accuracy checks. A dedicated short-sale processor keeps all parties aligned and reduces the risk of last-minute surprises.
### For Investors
More REOs mean more competition. Investors looking for opportunities increasingly prefer pre-foreclosure short sales because the timelines are more predictable and the deals are often better.
If you’re any one of these three groups, partnering with a specialist avoids bottlenecks and ensures the file keeps moving — even when the bank slows down. If someone is ready to start a short sale today, the fastest route is here: start a short sale with our team
.Start a short sale with our team.
## Why 2025 Is the Year to Get Ahead of the Curve
Arkansas is shifting. With distressed sales rising statewide, the professionals who adapt early will serve their clients best.
Homeowners need guidance.
Agents need reliable negotiation support.
Title companies need clean, predictable approval workflows.
Short sales, when handled correctly, bring all three together.
Massachusetts Foreclosures Are Rising: What Homeowners Need to Know About Short Sales in 2025
If you’re a Massachusetts homeowner, attorney, or real estate agent, you’ve probably noticed a trend that isn’t exactly welcome news: foreclosures across the state are climbing again in 2025. What was once a slow, modest uptick at the end of last year has turned into a sharper rise — especially in certain counties and cities.
And while that’s never good news for families, it *does* make this the right moment to talk about options. Specifically: short sales.
Short sales are often misunderstood, but they’re one of the most powerful tools homeowners have to avoid foreclosure. They also give realtors and attorneys a way to provide a soft landing for clients who are underwater, behind on payments, or facing unmanageable mortgage terms. With foreclosures increasing across Massachusetts, options matter more than ever.
Let’s break down what’s happening with Massachusetts foreclosure activity — and why a short sale might be the smartest path forward for many households in 2025.
Foreclosures Are Increasing Across Massachusetts
Foreclosure filings in Massachusetts recently reached 1 per every 5,101 housing units. With 591 filings across roughly 3,014,657 homes, that puts the state notably above where it was just months earlier.
As recently as April 2025, Massachusetts saw filings at 1 per every 5,442 units — so the increase is noticeable. Analysts across the housing industry are clear about what’s driving it:
- Higher interest rates
- Economic and household budget pressures
- Elevated consumer debt
- Borrowers struggling to stay current on FHA-insured mortgages
- A growing number of homeowners still carrying pandemic-era financial strain
In other words, homeowners aren’t falling behind because of one isolated issue. It’s a pile-up, and it’s pushing more Massachusetts borrowers toward default.
Springfield and Hampden County Are Facing Much Higher Distress
While the statewide foreclosure rate is increasing, some areas are getting hit much harder than others. From January through June 2025, municipalities in Hampden County — especially Springfield — saw significantly higher concentrations of foreclosure petitions.
Here’s the standout stat:
- Springfield recorded approximately 3.48 foreclosure petitions per 1,000 owner-households,
- Compared to the statewide average of just 1.13 petitions per 1,000 households.
That is more than triple the state average.
For attorneys and realtors working in Western Massachusetts — and especially for homeowners in Springfield — this means the risk of foreclosure isn’t theoretical. It’s on your doorstep.
And when lenders begin filing at this pace, the timeline can move fast.
Why Short Sales Matter More in 2025
Most homeowners don’t realize this, but a short sale is almost always less damaging than a foreclosure — financially, legally, and emotionally.
A foreclosure in Massachusetts includes:
- Public notice
- Court filings
- A long-term credit impact
- Limited ability to buy again for years
- Potential pursuit of deficiency balances depending on loan type
- A stressful, uncertain process for both the homeowner and the agent
A short sale, on the other hand:
- Stops the foreclosure clock
- Avoids the public stigma
- Protects credit far better
- Allows the homeowner to transition smoothly
- Often includes relocation assistance at closing, especially with FHA short sales
- Gets both the homeowner and their attorney/legal advisor out of a much more damaging scenario
Short sales are designed for situations exactly like the one Massachusetts is experiencing right now: rising mortgage delinquencies, higher FHA defaults, and pockets of intense foreclosure pressure.
If you’re a homeowner who’s starting to fall behind — or an attorney or realtor representing one — a short sale is almost always the more controlled, predictable, and client-friendly option.
What Massachusetts Homeowners Should Do Now
If you’re reading the numbers above and thinking, *“This looks like my situation,”* the key is not to freeze. Foreclosure is a timeline-driven process — but so is a short sale. And the short sale gives you the power to act *before* the lender does.
Here’s what every MA homeowner should consider:
- Don’t wait until the auction date is set.
Once the lender schedules a sale date, your options shrink. Short sales need time — but they *can* stop the auction when handled correctly.
- FHA borrowers should act early.
FHA-insured loans have specific timelines and requirements. Early action typically results in better approvals and access to relocation assistance.
- Agents should be advising clients early, not late.
In a rising-foreclosure market like Massachusetts, homeowners need guidance sooner — not when they’re already in panic mode. Realtors who help clients avoid foreclosure position themselves as trusted advisors, not just listing agents.
- Attorneys can protect clients with a short sale pathway.
A short sale is often a homeowner’s cleanest legal exit. Attorneys can help clarify Massachusetts-specific foreclosure rules while coordinating with a short sale expert who handles lender negotiation.
How Crisp Short Sales Helps Massachusetts Homeowners, Realtors, and Attorneys
Short sales are notoriously complex. Lenders lose paperwork, FHA forms get kicked back, attorneys get frustrated, agents get stuck, and homeowners get stressed.
That’s why we built Crisp Short Sales around one core idea: make this easier for everyone involved.
We handle:
- All lender communication
- Full document prep and submission
- Weekly progress updates
- Coordination with attorneys and title
- FHA, VA, conventional, and portfolio short sales
- Complex files with multiple liens
- Keeping the deal moving so agents can focus on selling
If you’re in Massachusetts and need help starting a short sale today, you can begin right here:
Start here: Start a Short Sale
If you’re an attorney or realtor looking for a partner who knows how to help real estate agents close short sales faster, visit our service overview:
👉 Learn more: Who We Serve
If your homeowner client needs relocation assistance or help understanding the process, we also explain what we do here:
Massachusetts foreclosure numbers may be rising — but that doesn’t mean homeowners need to go through the worst possible outcome. A short sale is a dignified, structured, and solution-focused alternative.
And in 2025, for many MA homeowners, it’s exactly the tool they need.
Short Sales & Foreclosures in Oregon: What Agents Should Know in 2025
Oregon is one of those states where the housing data can look calm at a distance—then you zoom in and suddenly the story gets a lot more interesting. On paper, the foreclosure rate seems relatively mild compared to other parts of the country. But rising national foreclosure activity, a noticeable uptick in Oregon’s distressed inventory, and cooling investor demand are all creating a perfect environment where short sales are becoming increasingly relevant again.
If you’re an Oregon agent juggling listings, buyers, and changing market signals, now is the time to understand how short sales fit into today’s landscape—and how they can actually save deals that might otherwise fall apart.
Oregon’s Foreclosure Activity: The Calm Before the Storm?
Let’s start with the basics.
In April 2025, Oregon saw one foreclosure for every 7,384 housing units statewide.
Is that higher than the national average? No.
Is it significantly lower than the hardest-hit states? Also yes.
But here’s the part that matters: nationally, foreclosure filings rose nearly 20% year-over-year, and Q3 2025 filings were up 16–17% compared to the prior year. Whenever national numbers move sharply, Oregon is never far behind. The state tends to follow national cycles—just with a slight delay.
Translation: the low foreclosure rate looks good now, but the pressure is building.
And this pressure is showing up in a more worrisome place…
The Rise of Zombie Foreclosures in Oregon
While Oregon’s overall foreclosure rate is relatively modest, the vacant and abandoned pre-foreclosure numbers are not.
As of Q4 2025, Oregon had a:
Zombie foreclosure rate of 7.07%
That’s 51 zombie foreclosures sitting empty among properties already in the foreclosure process.
This matters for two reasons:
- Vacant homes deteriorate fast, often dropping in value well below the lender’s expectations.
- Vacancy almost always increases the likelihood of a short sale, because repairs, vandalism, and deferred maintenance make full payoff unrealistic.
Agents who understand this dynamic can get ahead of the curve by educating sellers before the bank steps in—or worse, before the property declines further.
The Investor Pullback Is Quietly Fueling Short Sale Opportunities
During the pandemic boom, deep-pocketed investors swooped into Oregon markets like Portland, Salem, and Eugene, scooping up distressed homes and tight inventory before most traditional buyers even had a chance. But that momentum has cooled dramatically.
In Q1 2025, only 4.4% of Oregon homes were purchased by institutional investors, down from 4.7% a year earlier.
That may sound like a small drop, but it represents a bigger shift:
- Institutional investors are pausing or tightening criteria.
- The quick-cash offers that once bailed out distressed sellers are slowing down.
- More distressed properties are left to traditional retail buyers—who often need repairs, concessions, or price reductions to make the deal work.
Short sales naturally fill this gap.
When investors back away and homeowners can’t sell fast enough, a bank-approved short sale can keep a foreclosure off their record and help agents close deals that wouldn’t pencil out otherwise.
Why Short Sales Matter in Oregon Right Now
Even though Oregon doesn’t appear in most “top foreclosure states” lists today, the data points all trend toward increased distress:
- More national foreclosure activity
- More vacant pre-foreclosures
- Fewer investor rescue-offers
- Rising repair costs
- Higher interest rates squeezing equity
And when those conditions collide, short sales become one of the most effective tools for agents to:
- Save a listing that won’t appraise
- Avoid a foreclosure for a struggling homeowner
- Get an underwater seller to closing
- Help first-time buyers purchase homes that need work
- Close a deal in situations where traditional offers are falling apart
But of course, short sales are still paperwork-heavy, lender-slow, and filled with pitfalls—unless you have the right partner.
Where Crisp Short Sales Fits Into the Oregon Market
If you’re an Oregon agent staring at a pre-foreclosure, a behind-on-payments homeowner, or a zombie-ish property where the seller hasn’t visited in months… you don’t need to handle the lender side yourself.
That’s exactly what we do.
Crisp Short Sales specializes in handling all lender communication, document collection, valuation disputes, and approval negotiations—so you can focus on selling, not chasing banks. If you’ve never used a third-party processor, you can think of us as your behind-the-scenes teammate.
Agents use us when:
- A home is underwater and needs a short sale negotiator
- A bank needs updated docs, payoffs, or hardship letters
- You want help getting short sales approved faster
- You need a partner who knows Oregon lenders, servicers, and timelines
- You want to avoid a deal slipping into foreclosure
And we’re always here to help your business too. If you want to grow your short sale volume without adding hours of paperwork, our service for helping real estate agents close short sales faster links smoothly with your workflow — and keeps you out of the lender chaos.
If you’re new to short sales, our page on short sale processing and negotiation explains exactly how we work, and if you already have a deal that needs help, you can start right now through our simple short sale intake form.
Final Takeaway for Oregon Agents
Oregon isn’t flashing red on foreclosure maps—yet.
But the indicators that lead to distressed sales are all rising:
- National foreclosure filings are climbing.
- Zombie properties are increasing.
- Investor safety nets are shrinking.
This is exactly the kind of environment where smart agents prepare early, position themselves as the go-to expert for distressed homeowners, and build trusted partnerships so they’re ready when the wave arrives.
Short sales aren’t going anywhere. In Oregon, they’re just getting started again.
Kansas Short Sales & Foreclosures: What Rising Vacancy Rates Really Mean in 2025
Kansas isn’t usually the first state people point to when talking about distress in the housing market. But 2025 is shaping up to be a different kind of year — one where vacant homes, zombie foreclosures, and a spike in new foreclosure starts are creating real challenges for homeowners, agents, and title companies across the state.
Whether you’re a homeowner trying to avoid foreclosure, a real estate agent navigating difficult listings, or a title company working through messy files, Kansas’ shifting numbers tell a story you can’t afford to ignore.
In this post, we’ll break down the latest data, explain the risks behind rising vacancies, and show how short sales are becoming one of the most important tools for keeping deals alive and avoiding costly foreclosures in Kansas.
---
## Kansas Foreclosures Are Rising — Fast
Kansas saw one of the sharpest increases in foreclosure starts in the entire country.
**✔ Foreclosure starts jumped 117% year-over-year (Q1 2025)**
According to ATTOM data summarized in an AmeriSave October 2025 report, Kansas saw more than double the number of homes begin the foreclosure process compared to the year before.
That kind of spike isn’t normal — especially for a state that typically ranks near the bottom in total filings.
**✔ 565 foreclosure filings in H1 2025**
That’s roughly 1 in every 2,275 housing units, placing Kansas 47th nationally — still low overall, but with pockets of concentrated distress.
Statewide, filings were technically 6.3% lower than the same period in 2024, but that doesn’t tell the whole story. In major counties — Wyandotte, Sedgwick, Shawnee — foreclosures began ramping up faster than the statewide average.
And the trend isn’t happening in a vacuum.
Nationally, 140,006 properties started foreclosure in the first half of 2025 — a 7% increase.
Kansas is rising alongside a broader wave.
---
## Zombie Foreclosures? Kansas Is Nearly at the Top of the List
Here’s the stat catching everyone’s attention:
➡ 12.35% of Kansas homes in foreclosure are “zombie foreclosures” — that’s 81 vacant, distressed homes, making Kansas the 3rd-highest state in the U.S.
Zombie foreclosures happen when:
- The homeowner has left the property
- The foreclosure is still in progress
- The home sits vacant, often deteriorating
- And lenders haven’t taken possession yet
For Kansas, this is a big deal.
Vacant distressed homes drain neighborhood value and create risk for everyone handling the transaction.
### Why this matters to you
#### Homeowners:
Vacant properties can lower comps, making it harder to sell traditionally. A short sale often stops the foreclosure and prevents your property from being the next zombie.
#### Agents:
Vacancy + foreclosure =
- tougher valuations
- more repair issues
- harder buyer financing
- increased chance the bank denies the offer
Working with a short sale expert can stabilize the timeline and help get approvals faster — especially when the property condition is a concern.
#### Title Companies:
Zombie homes often lead to:
- abandoned liens
- code violations
- unpaid utilities
- outdated tax data
- unrecorded lender notices
A coordinated short sale file simplifies the title chain and clears issues before they become closing-day surprises. If your team wants a partner skilled at helping real estate agents close short sales faster, Crisp Short Sales can help — and you can learn exactly how at our [who we serve](https://crispshortsales.com/who-we-serve) page.
---
## Vacancies Are Rising — A Warning Sign Not To Ignore
Kansas ranks among the highest-vacancy states in ATTOM’s Q4 2025 report:
- 2.3% of all homes are vacant
- 5.8% of investor-owned homes sit empty, one of the highest rates nationwide
High vacancy rates are often the earliest indicator of housing stress.
Vacant homes → deferred maintenance → lower comps → reduced values → higher foreclosure exposure.
And when you combine high vacancies with rising foreclosure starts?
That’s when short sales stop being an “option” and start becoming a necessary strategy to keep deals from collapsing.
---
## Why Short Sales Are Becoming Critical in Kansas (2025 Edition)
With more homes moving toward foreclosure — and more of them sitting empty — Kansas homeowners, agents, and title companies need fast, predictable solutions.
Here’s where short sales fit into the picture:
### For Homeowners
A short sale can:
- Stop the foreclosure
- Prevent the home from becoming a zombie property
- Limit credit damage
- Provide a dignified exit
- Often include move-out assistance
(Many Kansas sellers qualify for lender-paid relocation funds — learn more about these options at our page on [how we help](https://crispshortsales.com/how-we-help).)
### For Real Estate Agents
Short sales help you:
- Save listings that might otherwise get foreclosed
- Handle distressed valuations without losing the buyer
- Keep your pipeline moving instead of dying on lender desks
- Avoid the complexity of negotiating with lenders yourself
Most agents don’t have the time (or desire) to spend hours each week on hold with servicers.
That’s where a Kansas-specific short sale processor becomes invaluable.
### For Title Companies
Short sales reduce:
- title defects
- unknown liens
- HOA arrears
- municipal issues
- solar/UCC complications
- payoff delays
And because our clients start files through our secure intake system at [start a short sale](https://crispshortsales.com/start-short-sale), all documents, approvals, and updates remain centralized and organized throughout the transaction.
---
## The Bottom Line for Kansas in 2025
Kansas isn’t facing a traditional foreclosure wave — it’s facing a vacancy-driven distress wave.
- Foreclosure starts are up 117%
- Vacancies are among the highest in the nation
- 12.35% of foreclosure homes are already empty
- Distress is rising in metro hubs
- And national trends show more foreclosure pressure ahead
Whether you’re a homeowner trying to avoid foreclosure, an agent managing distressed listings, or a title company clearing complex files, short sales are becoming the critical safety valve in the Kansas real estate market.
If you or your client needs help navigating a short sale anywhere in Kansas, I’m here to help every step of the way.
Short Sales in North Carolina: What Homeowners, Agents, and Title Companies Need to Know in 2025
North Carolina’s housing market has been on a wild ride over the last few years. Fast price increases, bidding wars in Charlotte and Raleigh, and a wave of transplants from other parts of the country drove demand and pushed up values. But 2025 looks different. The market is stabilizing, appreciation is slowing, and more homeowners are quietly slipping into mortgage trouble.
For anyone working with distressed properties—whether you’re a homeowner trying to avoid foreclosure, an agent navigating complex listings, or a title company preparing for a tricky closing—short sales are absolutely back on the table in North Carolina.
Below, we break down what’s happening and why short sales matter right now.
The NC Numbers Everyone Should Pay Attention To
📍 Mortgage Delinquency Rate: 2.7% (2025)
A 2.7% delinquency rate may not sound huge, but in a state with millions of housing units, this represents a large pool of households under real financial stress. Many of these homeowners don’t realize a short sale is even an option—or they don’t know how early they can start the process. In reality, a lot can be done before foreclosure ever becomes a threat, especially if they connect with someone experienced in short sale negotiation and pre‑foreclosure support, like the services outlined in our guide to helping homeowners avoid foreclosure with a short sale.
📍 Foreclosure Activity: 1 in Every ~4,454 Housing Units (April 2025)
This statistic puts North Carolina in a “moderate but meaningful” distress category. It’s not a crisis. But it’s steady—and that’s often worse. Steady distress means:
- A pipeline of homeowners falling behind month after month
- Agents encountering more upside‑down listings
- Title companies dealing with more payoff complications
- A growing need for smooth, well‑managed short sale files
When a property enters pre‑foreclosure in NC, the timeline moves faster than people expect. Having a team that specializes in short sale coordination—and communicates clearly with lenders, agents, and title teams—is often the key difference between a workout that closes and one that falls apart.
📍 NC Median Home Price: ≈ $365,000 (Early 2025) — Slowed Growth (~3–4%)
North Carolina has seen explosive growth over the past decade. But 2025 is the first year where appreciation has cooled significantly. Slower price growth affects short sales directly:
- Homeowners who bought in the last two or three years may no longer have much equity
- Rising interest rates mean some owners can’t refinance
- A small decrease in value can instantly turn a “normal sale” into a short sale
- Distressed sellers may owe more than the property is worth
This stabilization period is often when short sales quietly spike. When equity shrinks but payments stay high, homeowners stuck between financial pressure and declining home values benefit from exploring whether they qualify for a short sale to avoid foreclosure. Agents can direct them to our page on starting a short sale quickly and efficiently.
Why This Matters for Homeowners
If you’re falling behind on payments, you’re not alone. Many homeowners across NC are stuck between rising living costs, cooling property values, and mortgages that suddenly feel overwhelming. A short sale can:
- Stop foreclosure
- Prevent long‑term credit damage
- Allow relocation with dignity
- Help you walk away without owing the deficiency balance (in many cases)
Most importantly—you don’t need to wait until foreclosure is imminent. Many of your options disappear if you wait too long. That’s why connecting with a short sale expert early matters.
Why This Matters for Agents in North Carolina
North Carolina agents are seeing more listings with tricky situations:
- Sellers with no equity
- Payoff numbers higher than the list price
- Properties needing repairs sellers can’t afford
- Borrowers more than 90 days late
A short sale is often the best way to salvage a listing that would otherwise expire—but only if it’s managed well. Agents who partner with a professional experienced in helping real estate agents close short sales faster can:
- Avoid endless back‑and‑forth with lenders
- Prevent last‑minute surprises with title
- Dramatically reduce approval timelines
- Focus their time on selling instead of negotiating
Short sales are paperwork‑heavy, deadline‑sensitive, and unforgiving of mistakes. Having a specialist handle the lender side allows the agent to stay in control of the client relationship without drowning in tasks.
Why This Matters for Title Companies
Title teams across NC are increasingly encountering:
- Junior liens
- HOA super liens
- Solar/UCC filings
- Delinquent taxes
- Payoffs that exceed anticipated proceeds
Short sales require precision, communication, and timeliness. When the lender demands corrections or approvals larger than expected, closing can be delayed for weeks—unless the negotiation is handled proactively. Title companies benefit tremendously when a short sale is managed through a system designed to keep all parties aligned, document‑ready, and updated. Our structured process ensures:
- Weekly lender updates
- Full document packages
- Addressing title issues early
- Direct lender communication to prevent delays
The goal is simple: get the file cleared and close on time.
The Bottom Line for NC in 2025
North Carolina isn’t in crisis—but the numbers don’t lie. Mortgage delinquencies are meaningful. Foreclosures are steady. Equity is thinning for many homeowners. That combination is exactly what precedes a rise in short sale activity.
Whether you’re a homeowner trying to avoid foreclosure, an agent with a challenged listing, or a title company managing complexities, short sales offer a real solution—if handled correctly.
If you want a fast, organized, and experienced approach to short sale negotiation, you can start your short sale here or reach out anytime. We’ve helped agents, homeowners, and title companies across multiple states keep distressed deals on track and get them to the closing table.
Short Sales & Foreclosures in Indiana (2025): What Agents, Homeowners & Investors Need to Know
Indiana is not typically the first state people think of when discussing housing distress — but 2025 has changed that narrative. With rising foreclosure activity, increasing vacancy issues, and significant pockets of local distress, more owners and agents in Indiana are being forced into tough decisions about how to handle mortgage hardship.
This is where the short sale becomes an essentia tool — and where agents close short sales faster becomes more important than ever.
Learn more about how we help real estate agents close short sales faster.
In today’s breakdown, we’ll look at what’s really happening across Indiana, where the pressure is building, and why short sales are becoming a smarter (and often overlooked) alternative to foreclosure for thousands of homeowners.
Indiana’s Foreclosure Landscape in 2025
Indiana is now in the Top 10 for Foreclosure Rates
In the first half of 2025, Indiana logged foreclosure filings on 0.18% of all housing units — about 1 in every 556 homes. That places the state among the 10 worst foreclosure rates in the country.
When the overall rate climbs that high, you can assume three things:
- Many homeowners are underwater.
- Loan modifications are being denied more frequently.
- Short sales are about to surge.
For agents, this is exactly when understanding short sales becomes a strategic differentiator — especially when you can rely on an expert to manage negotiation and approval so you stay focused on listings and closings.
October 2025: 668 New Filings in a Single Month
By October 2025, Indiana recorded 668 foreclosure filings statewide — approximately 1 in every 4,421 housing units.
This month-to-month consistency in filings shows that distress isn’t spiking — it’s ongoing. That means homeowners in hardship aren’t just a small category anymore; they’re a major segment of the market.
Indiana Ranked 8th Nationally by Foreclosure Count
ATTOM’s 2025 data puts Indiana 8th in the nation, with:
- 937 total foreclosures
- A statewide rate of 1 in every 3,129 households
For context, that means Indiana has more foreclosure activity than many larger states — and far more than markets previously considered “high-risk.”
Short sales are becoming an increasingly necessary alternative to prevent these numbers from getting worse — and to help owners escape years of credit damage. When they choose that route, many rely on resources like short sale processing and lender negotiation through Crisp Short Sales.
Often, the biggest barrier to completing these transactions is simply having someone who knows how to prepare the file, manage the lender’s process, and keep the transaction moving.
The Hotspot: Marion County (Indianapolis)
If Indiana is heating up, Marion County is the boiling point.
Marion County Distress Snapshot
- - 899 foreclosure starts between January–July 2025
- Roughly 1 in every 234 owner-occupied homes
- 1,630 filings in 2024 — the highest since 2018
- Foreclosure rates rising three consecutive years
Marion County’s volume is so heavy that even well-qualified sellers can get stuck in stalled foreclosure timelines or unresponsive servicers.
is exactly where short sales help prevent the worst-case scenario. For distressed sellers, starting a short sale early — especially a guided page like how we help homeowners avoid foreclosure through a short sale — can keep the process controlled instead of chaotic.
Zombie Foreclosures: Indiana’s Quiet (But Growing) Problem
A “zombie foreclosure” means a property is vacant while going through foreclosure — a double hit for neighborhoods, comps, and local governments.
Indiana has 219 zombie foreclosures as of Q4 2025, which is:
- 6.4% of all statewide foreclosures
- The 8th highest concentration nationally
Vacant distressed homes pull down neighborhood values, attract vandalism, and interfere with traditional sales.
Short sales prevent zombie foreclosures because the owner stays engaged in the process — signing documents, communicating with lenders, cooperating with agents — instead of disappearing and letting the property deteriorate.
Why Indiana Agents Are Leaning on Short Sales More Than Ever
Between underwater mortgages, higher interest rates, and accelerating foreclosure timelines, Indiana agents are turning to short sales as a strategic listing opportunity, not an inconvenience.
The catch? Short sales only work smoothly when the lender negotiation is handled by an expert. Agents don’t have the time — or desire — to chase loss mitigation departments for 6–12 weeks.
That’s why many Indiana agents work with a third-party short sale negotiation service like Crisp.
They stay in control of the listing, the commission, and the client relationship — while we manage the bank.
If a homeowner is ready to begin, they can do so instantly through the start a short sale intake form.
Why Short Sales Are Often Better Than Foreclosure in Indiana
For homeowners:
- Avoid foreclosure reporting on credit
- Avoid eviction
- Often get relocation assistance paid at closing
- Walk away with a clean break
For investors & agents:
- Faster closings
- Improved deal structure
- Less risk of lender delays or denials
- A dedicated file manager who keeps everything moving
Short sales are not “easy,” but with experience and structure, they are absolutely winnable — especially in a state like Indiana where lender volume is rising but not yet overloaded.
Indiana’s 2025 foreclosure data tells a clear story:
Distress is growing, and short sales are becoming a critical exit path for thousands of homeowners.
Agents who know how to spot early signs of hardship — and who partner with a reliable specialist to handle the lender side — will separate themselves quickly as the market continues shifting.
If you’re an Indiana agent with a complicated file, a dead-end lender, or a seller overwhelmed by the process, you don’t have to manage it alone. Short sales work best when the negotiation is handled by someone who does it every day — and that’s where Crisp steps in.
Short Sales & Foreclosures in Alabama: What 2025 Is Really Telling Us
Short answer: yes, Alabama is definitely feeling the pressure from rising foreclosures in 2025—and that’s exactly where smart, well-timed short sales can save the day for homeowners, agents, and attorneys.
---
Short Sales & Foreclosures in Alabama: What 2025 Is Really Telling Us
If you work in Alabama real estate—or you’re a homeowner getting scary letters from the lender—you’ve probably noticed: things feel *busier* than they did a year or two ago.
And the numbers back that up.
- H1 2025: 3,040 Alabama properties had foreclosure filings, about 1 in every 762 homes (0.13% of housing units). Foreclosure activity was up 18.5% vs. early 2024 and 35.8% vs. 2023.
- April 2025: 737 properties entered foreclosure, about 1 in every 3,143 homes, ranking 8th-worst in the nation for that month.
- September 2025: Alabama still had 547 properties with foreclosure filings, about 1 in every 4,234 homes, with Mobile, Jefferson, and Montgomery among the hardest-hit counties.
- January 2025: 510 properties had foreclosure filings—1 in every 4,542 homes—with elevated activity in Perry, Bullock, and Coffee counties.
In plain English:
Alabama isn’t just having a blip. Foreclosure pressure has been rising and staying elevated throughout 2025.
The good news?
For many homeowners, foreclosure is not the only option—and for realtors and closing attorneys, that’s where a properly structured short sale can turn a losing situation into a controlled, dignified exit.
---
Why Foreclosure Numbers Matter to Real People in Alabama
For Homeowners
If you’re behind on payments in Birmingham, Mobile, Montgomery, Huntsville, Tuscaloosa, or in one of the smaller counties like Perry, Bullock, or Coffee, you’re not alone. Rising filings mean:
- More competition if you try to sell fast.
- More distressed inventory hitting the market.
- Lenders tightening guidelines as they deal with higher volume.
But it also means lenders are actively working loss-mitigation files—including short sales—because they don’t actually *want* to own more property.
That’s where a well-negotiated short sale can help you:
- Avoid a full foreclosure on your record.
- Potentially walk away owing less—or nothing at all—after closing.
- Get a cleaner path to financial recovery than just “letting it go back to the bank.”
If you’re not sure whether your situation qualifies, this is exactly the kind of scenario where our team steps in to explain options and handle the back-and-forth with the bank. You can see exactly how we help Alabama homeowners through the short sale process and what that actually looks like in practice.
---
What Alabama Realtors Need to Watch in 2025
For agents, these foreclosure stats translate into something very practical:
- More listings with missed payments behind them.
- More sellers with little or no equity, especially if they bought in the last few years.
- More situations where you *can’t* just price, list, and close like a normal sale.
If you’re listing a property in Jefferson, Mobile, or Montgomery County and you see:
- Mortgage balances that look higher than today’s realistic sale price
- Late notices, default letters, or scheduled sale dates
- Second liens, HELOCs, or HOA judgments
…you’re probably looking at a short sale candidate, not just a “tough comp.”
This is where partnering with a dedicated short sale processor becomes a huge advantage. Instead of spending your nights on hold with loss mitigation, you can stay focused on:
- Pricing strategy
- Marketing the property
- Managing buyer expectations
- Keeping your pipeline moving
Our role is behind the scenes—collecting documents, working through value disputes, communicating with multiple lienholders, and pushing the file from “submitted” to “approved.” That’s why we built a system specifically for supporting real estate agents and closing professionals with short sale files nationwide.
---
Closing Attorneys: Why Short Sales Are Worth the Extra Work
Attorneys and title/closing offices in Alabama are seeing the same trend:
- More title searches with old liens or judgments.
- More scheduled foreclosure sale dates hanging over contracts.
- More files where the seller’s proceeds are nowhere near enough to clear everything.
Short sales can look messy at first glance—but when managed correctly:
- They reduce the risk of last-minute cancellations on the eve of foreclosure.
- They create clear, documented approvals from all lienholders.
- They often convert “dead deals” into closings that actually fund.
A coordinated short sale approval gives you what you need:
- Written lien releases
- Final approved HUD/CD
- Clear instructions for who gets paid what
Our job is to quarterback that lender side so that by the time the file hits your desk, you can focus on clean title and a smooth closing, not chasing loss-mitigation departments for answers.
---
Short Sales vs. Foreclosure in Alabama: Key Differences
Here’s how the two paths usually compare for distressed Alabama homeowners:
Foreclosure:
- Public auction, public record, and long-term credit damage
- No control over sale price or buyer
- Possible deficiency actions or lingering debt, depending on the case
- Emotional and logistical stress for the homeowner and their family
Short Sale:
- Property listed and sold through a licensed real estate agent
- Buyer and price negotiated like a normal sale (subject to lienholder approval)
- Potential for deficiency waiver or agreed-upon repayment terms
- More dignified exit, with time to plan your move and next steps
With filings up 18.5% over last year and still elevated heading into fall 2025, waiting and hoping things work out is not a strategy. If the numbers don’t pencil out for a traditional sale, a short sale may be the best way to protect everyone involved.
If you (or your client) are in that spot, you can start a short sale file and get us involved early so we can review the situation before foreclosure deadlines creep up.
---
What To Do *Right Now* if You’re in Alabama and Falling Behind
Whether you’re a homeowner, agent, or closing attorney, here’s a simple roadmap:
- Get the full story.
Confirm the loan balance(s), arrears, foreclosure status, and any second liens or HOA dues.
- Know your timeline.
Ask the lender for the next scheduled foreclosure sale date (if any) and what’s required to pause it.
- Get a realistic valuation.
Work with a local agent who understands today’s Alabama market—not last year’s prices.
- Decide if a traditional sale works.
If the numbers don’t clear all liens + closing costs, don’t force it. That’s when a short sale is your tool.
- Bring in a short sale specialist early.
The sooner we’re involved, the more options we have to challenge values, negotiate lien releases, and keep the file on track.
Our entire focus at Crisp Short Sales is making sure good deals don’t die just because banks are overloaded or the paperwork is confusing.
Short Sales & Foreclosures in Tennessee: 2025 Market Trends Every Homeowner, Agent & Title Company Should Know
Tennessee foreclosure trends, housing data, and how short sales help homeowners, agents, and title companies navigate 2025’s market.
If you’re a Tennessee homeowner struggling with payments, a real estate agent navigating distressed listings, or a title company trying to keep deals on track, understanding what’s happening in the Tennessee market is more important than ever.
Foreclosures in Tennessee: What the Numbers Show
Foreclosure activity in Tennessee is still relatively low compared to many states, but filings have been climbing in 2025. According to Safeguard Properties, 486 Tennessee homeowners received a foreclosure notice in April 2025 — that’s one filing for every 6,369 housing units (486 out of 3,095,472). By August, filings dipped slightly to 381, or one in every 8,125 homes, according to SoFi’s “Foreclosure Rates for All 50 States” report (Oct 2025). Hundreds of Tennessee families are entering the foreclosure process every month, and many are searching for a way to avoid losing their home to the courthouse steps.
Home Prices & Inventory Are Rising — But Not Fast Enough for Distressed Sellers
Tennessee home values continued to climb in 2025. Redfin reports that the median Tennessee home sold for $405,500 in October 2025, up 4.6% year over year. Inventory has also expanded: the number of homes listed for sale in October was 13.1% higher than it was a year earlier. Higher prices and more listings can help some homeowners regain equity, but others facing job loss, medical debt, rising insurance, or adjustable-rate mortgage resets may still find themselves underwater. As buyers gain more choices, distressed properties often sit longer, making a short sale a more realistic exit than a traditional listing.
Why Short Sales Matter in Tennessee Right Now
Even though Tennessee isn’t a high-foreclosure state, short sales fill an important gap for homeowners who don’t have the luxury of time.
For homeowners:
- Avoid the long-term credit damage of foreclosure.
- Maintain control over the move-out timeline, rather than being forced out after a sheriff’s sale.
- Potentially receive relocation assistance or money at closing, depending on lender approval.
- Settle remaining mortgage balances without owing a deficiency, depending on lender terms.
For real estate agents:
- Gain listing opportunities in a competitive market and help clients who are upside down.
- Close deals even when the seller owes more than the home is worth.
- Lean on a specialized short sale team for lender paperwork and negotiations so you can focus on pricing, showings, and marketing.
For title companies:
- Navigate payoff shortages, judgment liens, HOA balances, and municipal fines that often accompany distressed properties.
- Coordinate lender approval and title work to keep closings on track.
- Benefit from a dedicated short sale processor who can communicate with all parties and ensure documentation is complete.
What’s Causing Tennessee’s Short Sale Activity in 2025?
Based on statewide data and the files we see moving through our office, the top contributors include:
- Payment shock from adjustable-rate mortgage resets issued during 2020–2022.
- Rising cost of living: property insurance, taxes, and everyday expenses are squeezing budgets.
- Major life events such as job changes, medical issues, divorce, or family transitions.
- Over-leveraged purchases: buyers who used FHA, VA, or minimal down payments during peak pricing periods may still be underwater, especially if the property needs repairs.
Short Sales vs. Foreclosure — Which Is the Better Path?
For most Tennessee homeowners, a short sale is the faster, less damaging option. Here’s how they compare:
- Credit impact: A short sale typically causes a smaller credit score drop and is easier to recover from, while foreclosure can severely hurt credit for years.
- Timeline control: Sellers can negotiate their move-out date in a short sale; in a foreclosure, the lender determines when the property is sold.
- Potential incentives: Some lenders offer relocation funds in a short sale; there are no incentives in a foreclosure.
- Future homebuying: Homeowners who complete a short sale may qualify to buy again sooner than those with a foreclosure on their record.
- Stress level: A negotiated short sale provides a more predictable path and professional support; foreclosure is forced and unpredictable.
What This Means for Tennessee Real Estate Professionals in 2025
Agents: Expect more hardship listings, particularly in counties where property taxes or insurance premiums have spiked. Be prepared to analyze whether clients have equity and advise them on short sale options when they don’t.
Title companies: Anticipate files with tight timelines, second liens, HOA claims, and payoff complications. A dedicated short sale processor can reduce surprises and keep closings moving.
Homeowners: If you’re struggling with your mortgage or owe more than your home is worth, don’t wait for foreclosure notices. The sooner you explore a short sale, the more likely you are to avoid foreclosure and protect your credit.
Final Thoughts
Tennessee’s foreclosure rates remain moderate, but they are trending upward. With home prices climbing and inventory expanding, distressed sellers have more options than they may realize. A properly managed short sale can help homeowners, agents, and title companies achieve a win‑win resolution and avoid the lasting damage of foreclosure. If you or your client is facing a complicated Tennessee short sale, reach out early — we’re here to help every step of the way. You can Start a Short Sale or learn more about how we help homeowners and how we assist real estate agents.
Connecticut Short Sales & Foreclosures in 2025: What Homeowners, Agents & Attorneys Need to Know
CT foreclosure rates are rising in 2025. Learn how short sales help homeowners, agents, and attorneys avoid long judicial foreclosure timelines.
Connecticut Short Sales & Foreclosures in 2025: What Homeowners, Agents & Attorneys Need to Know
Connecticut has always been a unique real estate market—one with long foreclosure timelines, heavy judicial oversight and a slower-moving process than almost any other state. In 2025, however, the pressure has increased. Foreclosure filings have ticked up, distressed homeowners are struggling with rising payments and aging properties, and agents are seeing more “complex listings” pop up on their radar.
If you’re a real estate agent, attorney or homeowner in Connecticut, understanding today’s short sale landscape matters more than ever. The good news? A properly negotiated short sale can resolve hardship, avoid a judgment, and get your clients to closing without fees or drama—as long as the file is managed correctly.
Here’s the state of the market and why short sales are becoming an essential tool again.
**Connecticut Foreclosure Trends: Why the Spike in Activity?**
- **October 2025:** Connecticut had **1 foreclosure filing for every 4,085 housing units** — that’s **376 filings statewide across 1,536,049 housing units**. *(Source: ATTOM U.S. Foreclosure Market Report — October 2025)*
- **Q1 2025:** The state ranked **#9 in the nation** for foreclosure activity, with **1 filing for every 1,182 units**. *(Source: ATTOM U.S. Foreclosure Market Report — Q1 2025)*
- **June 2025:** The average time to complete a foreclosure in Connecticut hit **1,874 days** — more than **5 years**, among the longest timelines in the U.S. *(Source: ATTOM H1 2025 data via PR Newswire)*
- **May 2024:** Connecticut had the **4th‑highest foreclosure rate** in the country, with **1 filing in every ~2,600 homes**. *(Source: Hartford Business Journal)*
That combination—high activity *and* extremely long timelines—creates the perfect environment for short sales. When foreclosure drags on for years, homeowners remain stuck in limbo, properties deteriorate, liens multiply and legal fees escalate. Real estate agents face drawn-out listings that stall out, and attorneys inherit cases that could have resolved far earlier through a negotiated workout.
**Why Short Sales Matter in Connecticut Right Now**
In judicial foreclosure states, the legal process is designed to provide due process—but the downside is time. A *lot* of time. Here’s what that means:
1. **Homeowners remain stuck for years.** During a multi-year foreclosure timeline, hardships don’t resolve themselves. Debt grows, missed payments accumulate and property condition declines. A short sale offers a clean exit: **no fees, no judgment and the ability to move on quickly**.
2. **Deferred maintenance becomes a major problem.** Connecticut has an aging housing stock. In distressed situations, repairs stack up quickly. Traditional buyers hesitate, and price reductions continue until the property finally hits the market at distress pricing. Short sales allow buyers to factor condition into the offer from day one, avoiding repeated price‑cut cycles.
3. **Attorneys avoid multi‑year litigation.** Connecticut’s 5-year average foreclosure timeline benefits no one. Attorneys often inherit files that drag on with no resolution. A well-negotiated short sale lets attorneys close the chapter quickly while giving their client a fresh start.
4. **Agents can actually get difficult listings to the finish line.** A short sale is the best tool an agent can use when a homeowner:
- Owes more than the home is worth.
- Has a second mortgage or HOA lien.
- Faces unemployment, medical hardship, divorce or property damage.
- Wants to sell but cannot cover the payoff.
When handled correctly, **short sales get approved, close on time and give agents a full commission — without the chaos of traditional foreclosure work**.
This is why so many agents partner with specialists who focus solely on [helping real estate agents close short sales faster](/who-we-serve) — using a dedicated process rather than trial‑and‑error.
**How Short Sales Work in Connecticut (And Why They’re Different Here)**
Short sales in Connecticut follow federal guidelines, but the state’s foreclosure timeline introduces unique challenges:
- Attorney‑driven transactions.
- Judicial oversight.
- Frequently higher lien complexity.
- Slower lender communication cycles.
- More aged delinquencies (creating large payoff gaps).
This is where having a dedicated short sale negotiation partner matters. Homeowners and agents don’t need to fight lenders alone—especially when specialists can manage documentation, hardship review, valuation challenges and back‑and‑forth negotiation.
If you’re unsure whether a situation qualifies, you can always start with a **free early review** using our intake form on [starting a short sale](/start-short-sale).
**Why Connecticut Attorneys Are Turning to Short Sales Again**
More attorneys are recommending short sales to clients because they:
- Reduce deficiency exposure.
- Close cases faster.
- Prevent judgments.
- Avoid escalating legal fees.
- Allow homeowners to exit with dignity.
- Help clients rebuild credit far faster than after foreclosure.
Short sales are more than a real estate tool—they are a legal strategy.
For attorneys looking to streamline cases, our service provides a complete behind‑the‑scenes process so your office doesn’t get pulled into daily lender communication. You stay in control; we handle the heavy lifting.
**A Smoother Path Forward for Connecticut Homeowners**
For homeowners overwhelmed by foreclosure notices, rising payments or declining equity, there *is* a path forward—one that avoids foreclosure and helps you move without paying a dime out of pocket.
Our team specializes in **short sale negotiation, document prep and full‑service coordination**, and we walk every seller and agent through the process personally. You can learn more about [how we help distressed homeowners](/how-we-help) — closing costs paid, flexible move‑out, relocation assistance at closing and stress‑free processing — on our website.
The bottom line: **Connecticut has one of the longest and most painful foreclosure processes in the country — but short sales offer a faster, cleaner and far more humane solution.** If you’re an agent with a tough listing, an attorney with a distressed client or a homeowner trying to get ahead of a foreclosure, now is the time to explore your options.
If you’re an agent interested in learning how we’re [helping real estate agents close short sales faster](/who-we-serve), or a homeowner ready to start your own short sale, we’re here to help. Let’s chart a new course together.
Short Sales & Foreclosures in Oklahoma: What Title Companies, Agents, and Homeowners Need to Know Going Into 2026
Oklahoma’s housing market has always had pockets of volatility, but 2025 has been a different story altogether. Distress activity is rising, timelines are tightening, and both agents and homeowners are feeling pressure from lenders who are processing more defaulted files than they have in years. Title companies, too, are fielding more calls about postponed closings, lien complications, and files stuck in loss-mitigation limbo.
If you work in Oklahoma real estate, now is the time to understand what the numbers really mean — and why short sale expertise matters more than ever.
Let’s break down the current landscape using verified ATTOM data, and talk about how real estate professionals can protect their clients (and their closings) as filings continue trending upward.
Mid-Year 2025: Oklahoma Distress Activity Surges 26.53% Year‑Over‑Year
By the halfway point of 2025, 2,194 Oklahoma properties had received a foreclosure filing. That represents a foreclosure rate of 0.12%, or 1 in every 804 housing units, ranking Oklahoma 19th-highest in the country. More importantly, it marked a 26.53% increase compared with the first half of 2024.
This level of mid-year growth is the earliest indicator that lenders, servicers, and asset managers are processing more delinquent files — and, in many cases, are tightening tolerance on valuation variances and documentation issues.
For agents and homeowners, that means:
- Fewer approved price reductions
- Stricter valuation reviews
- Heavier document requests and longer processing queues
- More files falling apart months into negotiations
This is exactly where a specialized short sale coordinator becomes invaluable. When lenders get overwhelmed, precision and persistence are the only things that keep a file moving. If you’re an agent needing help helping real estate agents close short sales faster, this is where we step in.
Q3 2025: Month‑to‑Month Decline, But Year‑Over‑Year Increase
While Oklahoma saw a moderation in Q3 2025 — 944 properties with foreclosure filings, or 1 in every 1,868 housing units, down 15.79% from Q2 — the story doesn’t stop there. Compared with Q3 2024, filings were still up 11.98% year-over-year.
This is classic early-cycle distress behavior: month-to-month swings, quarterly moderation, but a steady, unmistakable upward trend year-over-year.
For title companies, this means an increase in:
- Files requiring lien cure
- Deals involving underwater sellers
- Closings dependent on HOA payoffs, second-mortgage negotiations, and partial releases
A well-managed short sale file can mean the difference between a closing that happens and a closing that evaporates. When a seller is underwater, the fastest path to the closing table starts with short sale document prep and negotiation support. That’s exactly how we help homeowners avoid foreclosure and keep deals alive.
October 2025: A Major Spike (+74.34% Month‑to‑Month)
Then came October.
Foreclosure filings jumped to 462 statewide, equal to 1 in every 3,816 housing units — a dramatic 74.34% increase vs. September 2025, and 40% higher than October 2024.
This kind of spike can signal seasonal catch-up by servicers, bank-initiated pushes on older delinquent files, and expedited foreclosure actions where alternatives weren’t pursued. For agents, this means more homeowners will call panicked — after ignoring the problem too long. For homeowners, it means fewer options the deeper they are into the foreclosure timeline.
If someone receives a Notice of Default or is more than 90 days behind, starting a short sale immediately is critical. Waiting 30–60 days often removes negotiation flexibility completely. If a homeowner isn’t sure where to begin, they can start a short sale.
September 2025: The Volatility Warning
Interestingly, just one month before the October spike, September saw Oklahoma with only 265 foreclosure filings, or 1 in every 6,653 housing units — a 10.47% decrease from August and 27% lower than September 2024.
This tells us something important: month-to-month foreclosure data is reactive, not predictive. For real estate professionals, the actionable trend is the year-over-year increase, not temporary dips. Lenders are clearly continuing to process more distressed files overall, even though certain months appear calmer.
National Context: Distress Rising Everywhere
Oklahoma’s trends don’t exist in a vacuum. Nationally, October 2025 marked the eighth consecutive month of year-over-year increases in foreclosure activity: 36,766 properties received filings, foreclosure starts were up 20% YoY, and REO completions up 32% YoY. When the national distress wave grows, states like Oklahoma — with large rural populations, older housing stock, and wide price variability — tend to feel outsized impacts.
Why Title Companies & Agents Are Seeing Tougher Files
With filing volumes rising, title companies and agents across Oklahoma are noticing:
- More properties with junior liens
- More unresolved judgments
- More utility liens and HOA arrears
- More sellers underwater due to repairs they can’t afford
A short sale keeps the closing viable — but only if it’s managed with:
1. Clean document collection
2. Accurate hardship analysis
3. Aggressive lender follow-up
4. Protection of commission and buyer incentives
The number one reason short sales fail is not value — it’s file mismanagement. That’s why more Oklahoma agents are partnering with dedicated coordinators to get approvals issued faster and prevent deals from collapsing months into the process.
The Bottom Line for Oklahoma Real Estate Professionals
Oklahoma isn’t in crisis — but it is stepping into a multi-year period of increasing foreclosure activity. The combination of rising mid-year filings, higher Q3 activity year-over-year, a large October spike, and national distress momentum all point to one thing: short sales will become more common heading into 2026.
Agents, title companies, and homeowners who prepare early will navigate this cycle smoothly. Those who wait risk deals falling apart, sellers losing homes unnecessarily, and buyers walking away frustrated.
If any agent or homeowner in Oklahoma needs guidance on whether a short sale is appropriate — or how to structure one that actually gets approved — we’re here to help.
Short Sales & Foreclosures in Ohio: What Title Agents, Realtors & Homeowners Need to Know Right Now
Ohio has quietly become one of the fastest-shifting foreclosure markets in the country — and for anyone working in real estate here (title companies, agents, investors, and especially homeowners), understanding what’s happening beneath the surface is essential.
In 2025, the Buckeye State consistently ranked among the top ten markets for foreclosure activity. And when foreclosure pressure rises, short sales almost always follow.
Ohio’s Foreclosure Numbers Tell a Clear Story
- October 2025 – 1 in every 3,079 homes — Source: ATTOM — U.S. Foreclosure Rates by State (Oct 2025). This puts Ohio among the higher-distress states nationally, and it confirms a steady increase from earlier in the year.
- August 2025 – 1 in every 3,026 homes — Source: SoFi — Foreclosure Rates for All 50 States (Aug 2025). Only two months earlier, filings were already high — a sign that foreclosure pressure was not a short-term spike.
- April 2025 – 1 in every 3,002 homes (ranking #6 worst in the U.S.) — Source: Safeguard Properties — Foreclosure Rates by State (Apr 2025). This early-year ranking was the warning sign. Foreclosure filings placed Ohio firmly in the top tier of states experiencing homeowner distress.
Bottom line: Ohio homeowners have been navigating a difficult landscape throughout 2025. And when foreclosure pressure increases, the opportunity — and need — for well-executed short sales increases with it.
Why This Matters for Ohio Realtors
Short sales are no longer niche transactions here. They’re becoming a regular part of the market again. When handled correctly, a short sale can:
• Help your listing avoid foreclosure
• Salvage a deal that otherwise dies due to mortgage payoff challenges
• Protect your seller’s credit while giving them a clean exit
• Put you in control of the transaction rather than letting the bank dictate terms
The key phrase here, though, is “when handled correctly.” A short sale with no guidance, no follow-up, or no negotiation strategy becomes a 6-month headache. A properly managed short sale becomes a win for everyone — including you. If you ever need a partner specialized in helping real estate agents close short sales faster, you can learn more about how we support agents on the Who We Serve page.
What Title Companies Should Pay Attention To
Ohio title companies are feeling the pressure too — short sale files hit your desk with:
• Approval letters missing required language
• Payoff miscalculations
• Deadlines coming too fast
• Multiple mortgages or HOA balances
• IRS or state tax liens needing negotiation
• Miscommunication from servicers
When these files get messy, you get stuck chasing documents instead of clearing title. That’s exactly why we work directly with title teams — coordinating documents, correcting approvals, and making sure you receive lender-ready paperwork early rather than last-minute. If you'd like a clearer look at what that looks like, our How We Help page breaks down the entire process, from negotiations to approval letter cleanup.
For Ohio Homeowners: The Short Sale Is a Lifeline, Not a Last Resort
If you're a homeowner facing foreclosure in Ohio, the rising monthly filings aren’t just statistics — they’re stress points. A short sale can:
• Stop foreclosure
• Protect your credit far better than a foreclosure
• Wipe out mortgage deficiencies
• Offer relocation funds at closing (yes — real money to help you move!)
• Give you control over timing, move-out date, and transition
We even built a simple guide for homeowners who want to start their short sale today, available here: Start a Short Sale. When you’re in distress, the process needs to be simple, not overwhelming. That’s why we take on the negotiation, document coordination, and weekly communication — so homeowners don’t have to.
Why Short Sales Are Growing Again in Ohio
Here’s what’s driving the surge:
• Homeowners who bought in 2021–2022 are underwater
• Property taxes and insurance costs have jumped statewide
• Adjustable-rate mortgages adjusting upward
• Job disruptions and rising consumer debt
These macro-factors don’t just increase foreclosures — they increase short sale eligibility, especially when a homeowner tries to sell but the payoff is higher than the home’s value.
Ohio Agents: How to Know If Your Listing Qualifies for a Short Sale
You don’t need to guess. Quick checklist:
• Property value is lower than mortgage payoff
• Seller has a legitimate hardship
• Seller has missed payments — or will soon
• Multiple liens, HOA balances, or judgments are involved
• Appraisal disputes are likely
• Buyer needs faster approval than a large servicer usually provides
If any of these sound familiar, there’s a good chance the listing qualifies. And if you’re unsure, we’ll look at it with you — no commitment and no cost.
The Ohio Market Is Heading Toward More Short Sales in 2026
Foreclosure filings have been consistent for months, and unless something dramatic changes in the economy, short sale volume will continue rising. This is the moment for:
• Realtors to prepare
• Title companies to streamline processes
• Homeowners to explore options before foreclosure impacts long-term credit
A rising market doesn’t eliminate distress — it often just hides it. And Ohio’s data shows that distress is still very real. If you’re navigating a short sale or think one may be needed, we’re here to help — from the first phone call to the closing table.
Short Sales & Foreclosures in Minnesota 2025
If you live or work in Minnesota, you’ve probably noticed more “notice of default” and foreclosure headlines creeping back into the news. The good news: we’re nowhere near 2008 levels. The bad news: distress is clearly rising, and short sales are about to matter again for homeowners, agents, and title companies.
Let’s break down what’s happening in Minnesota right now—and how a well-run short sale can keep a problem file from turning into a full-blown foreclosure.
The Minnesota foreclosure numbers (and what they really mean)
- Foreclosure filings in Minnesota are up ~17% year-over-year, according to Realtor.com data reported by local Minnesota outlets.
- In September 2025, Minnesota had a foreclosure rate of 1 in every 9,031 housing units (279 filings out of ~2,519,538 units).
- For the first half of 2025 (Jan–June), Minnesota logged 2,197 properties with foreclosure filings, which works out to roughly 1 in every 1,147 housing units and a 2.04% increase vs. the same period last year.
- By October 2025, the pace ticked up again: ATTOM shows 1 in every 6,903 Minnesota homes had a foreclosure filing that month (365 filings).
So what does that mean in plain English?
- Minnesota is still mid-pack nationally, not a crisis state.
- But trend direction matters: filings are rising, and more homeowners are feeling payment pressure.
- For agents and title, that means more files with some level of distress, tighter timelines, and a higher chance that “normal” listings quietly morph into short sale situations.
Short sales sit right in the middle of this story: they’re often the off-ramp between “I’ve fallen behind” and “The bank is taking the house.”
For homeowners: when a short sale should be on your radar in Minnesota
Here are some signs you should at least have a short sale conversation:
- You’re 60+ days behind on your mortgage and can’t realistically catch up.
- You’ve had a job loss, income reduction, divorce, or medical issue, and your payment is now permanently unaffordable.
- Your home needs repairs you can’t afford and the as-is sale price won’t cover what you owe.
- You’ve tried to sell at a payoff price, had low showings or no offers, and your agent is telling you the market value is below your loan balance.
In those cases, a properly negotiated short sale can:
- Avoid a completed foreclosure and sheriff’s sale.
- Typically hit your credit less harshly than a full foreclosure.
- Give you a clear move-out date, with time to plan your next housing step.
- Potentially include relocation assistance at closing (money to help with your move) if your lender’s guidelines allow it.
At Crisp Short Sales, my focus is on helping Minnesota homeowners avoid foreclosure with a well-structured short sale, handling the lender paperwork, valuation disputes, and back-and-forth so you don’t have to live on hold. You can see exactly how we help homeowners and their agents through the short sale process and what that looks like step by step.
For real estate agents: how the MN market shift changes your job
A few practical implications of Minnesota’s rising foreclosure activity:
- More listings will be quietly underwater.
That “priced aggressively” listing with very little equity may actually be a short sale candidate once you net out commissions, closing costs, and repairs.
- Banks are getting busier again.
National foreclosure filings are up double-digits year-over-year, which means more files on fewer desks at the servicers. This can slow approvals—unless someone is on the lender side all day, every day, pushing.
- You can’t afford a blown deal right now.
A failed short sale is months of work ending in “foreclosure sale cancelled the closing.” Not fun for you, your client, or the buyer.
This is where partnering with a short sale specialist becomes a leverage play, not an expense. My role is helping real estate agents close short sales faster and with fewer surprises, while you stay the face of the deal and keep the relationship with your client. If that’s something you want in your back pocket for Minnesota listings, take a look at who we serve and how we work with agents and investors.
In practice, that looks like:
- Reviewing the net sheet early to confirm it’s truly a short sale.
- Helping you set realistic list pricing based on investor guidelines and recent approvals, not fantasy comps.
- Handling the BPO/appraisal disputes when the bank’s value comes in high.
- Keeping everyone updated weekly so your client isn’t blowing up your phone asking, “Have you heard anything yet?”
For title & closing companies: why short sale files are a different animal
If you’re on the title or settlement side in Minnesota, your work gets harder when foreclosures and short sales increase:
- Approval letters drive everything. Every fee, credit, and net has to match the lender’s written approval. One stray admin fee or incorrect prorate can trigger a last-minute re-approval request.
- Second liens, judgments, and HOAs show up more often. As homeowners fall behind, you’ll see more junior liens and delinquent HOA balances that must be negotiated and approved in writing before closing.
- Timelines are tighter and less flexible. Approval letters often have firm expiration dates, especially when foreclosure sale dates are already scheduled.
Working with a dedicated short sale processor means:
- You get clean, lender-approved settlement statements on time.
- You’re not stuck tracking down addenda or updated letters the morning of closing.
- You have a clear point person to coordinate when something changes at the last minute.
Crisp Short Sales routinely coordinates with title companies nationwide to keep short sale approvals in sync with the final Closing Disclosure or ALTA. If you want a go-to contact for short sale coordination and document prep in Minnesota, start with the overview on how we help title and settlement teams stay in compliance with lender approvals and feel free to reach out.
How to stay ahead of Minnesota’s rising foreclosure & short sale activity
Here’s a simple game plan tailored to each group.
Homeowners
- Talk to your servicer early if you’re falling behind. Ask about forbearance, modification, and other options.
- If the numbers don’t work, discuss a short sale with your agent and a short sale specialist before a foreclosure sale date is set.
- Gather your financials, hardship letter, and listing agreement early so your file can be submitted quickly.
- When you’re ready, you can start a short sale with Crisp online in just a few minutes—we’ll take it from there.
Real estate agents
- Add a quick “equity check” to every listing consult: What’s owed? What are realistic net proceeds? Is this actually a short sale?
- Flag any Minnesota listing where delinquency + low equity + needed repairs are all present. That’s short sale territory.
- Build a relationship with a short sale manager who will own the lender side so you can focus on pricing, marketing, and negotiations.
- Keep a simple script ready: “We can sell, but it’ll need to be as a short sale. I have someone who handles that process all day—let’s bring them in.”
Title & settlement
- Create a short sale checklist: approval letter on file, all payoffs in writing, HOA/judgment approvals, commission/fee structure matches approval, expiration dates tracked.
- Ask upfront: “Is this a true short sale with a lender approval letter, or just a tight equity file?”
- Make sure you have a single point of contact on the short sale side who can quickly update approvals if something changes.
At Crisp Short Sales, we provide short sale processing, negotiation, and closing support so these deals actually get to the table.