

Short Sale Relocation Assistance: 7 Questions Before You Count on the Money
Short sale relocation assistance can be a major relief for a homeowner who needs to move after a difficult sale. It may help with deposits, movers, temporary housing, or the basic cost of starting over.
But the important word is may.
Relocation money in a short sale is not automatic. It can depend on the loan type, investor rules, servicer requirements, occupancy, timing, approval-letter language, and whether the seller follows every condition before closing.
Before a seller counts on that money, these are the seven questions that should be answered.
1. Does the Approval Letter Actually Promise Relocation Assistance?
A seller should not rely on a verbal comment, an old program name, or something the servicer mentioned early in the process.
The <a href="/the-short-sale-blog/short-sale-relocation-assistance-approval-letter">short sale approval letter</a> needs to be reviewed carefully. It should confirm whether relocation assistance is approved, how much may be paid, who receives it, and what conditions must be met before payment is released.
If the approval letter does not clearly include the relocation terms, the seller should ask for clarification before moving or signing final documents.
2. Is the Seller Required to Occupy the Property?
Many relocation-assistance programs are tied to occupancy. If the property is already vacant, rented, abandoned, or occupied by someone other than the borrower, the seller may not qualify.
This is one of the biggest problems with <a href="/the-short-sale-blog/relocation-incentives-short-sales">short sale relocation assistance</a>. A seller may assume they are eligible because they are cooperating with the sale, but the program may require that they still live in the home.
That occupancy requirement should be confirmed early, especially if the foreclosure date is close or the seller is already planning a move.
3. When Is the Money Paid?
Relocation assistance is usually not paid upfront. In many cases, it is paid at or after closing, often through the closing statement.
That matters because the seller may still need money for moving expenses before the payment is available.
The safest approach is to confirm the timing in writing. The seller should understand whether the funds are paid at closing, after closing, through escrow, or only after the property is delivered vacant and in acceptable condition.
4. Can the Buyer, Agent, or Investor Object to the Payment?
Relocation assistance can affect how the short sale is structured. The servicer, investor, buyer, agents, and closing office may all need the payment disclosed correctly.
If the payment is not handled properly, it can delay approval or create a closing problem.
This is why a short sale specialist or experienced short sale negotiator should make sure the relocation payment is included correctly before closing documents are finalized.
5. Could a Foreclosure Date Cancel the Opportunity?
A short sale can still be active while a foreclosure date is pending. But if the deadline gets too close, there may not be enough time to approve the file, issue final terms, close the sale, and release relocation assistance.
The closer the sale date gets, the more urgent the file becomes.
A seller should not wait until the last week to ask about relocation help. The earlier the issue is raised, the better the chance of confirming eligibility and avoiding a last-minute surprise.
6. What Condition Must the Property Be In?
Some relocation payments require the property to be left clean, vacant, and undamaged. Personal belongings may need to be removed. Keys may need to be delivered. Utilities, access, and final walkthrough conditions may matter.
If the seller moves out but leaves the property in a condition that violates the approval terms, the relocation assistance could be delayed or denied.
The approval letter should be checked for any move-out requirements before the seller schedules movers.
7. What Happens If the Closing Is Delayed?
Short sale approvals often have expiration dates. If the buyer delays, title issues appear, documents are missing, or the lender needs an extension, the relocation terms may need to be reconfirmed.
A seller should ask whether the relocation assistance remains valid if the closing date changes.
This is especially important when the seller is relying on the money for a new rental, security deposit, or moving costs.
The Bottom Line
Short sale relocation assistance can help a seller move forward, but it should not be treated like guaranteed money until the approval terms are clear.
Before counting on it, confirm:
- The approval letter includes the relocation payment.
- The seller qualifies under occupancy rules.
- The payment timing is clear.
- The closing office knows how to handle it.
- The foreclosure timeline still allows enough time.
- The property condition requirements are understood.
- The payment remains valid if closing is delayed.
A short sale has enough pressure already. The safest move is to confirm the relocation terms before the seller makes financial commitments based on money that may still have conditions attached.
Crisp Short Sales helps sellers, agents, and homeowners review short sale approval terms, negotiate with lenders, and avoid avoidable closing problems. If relocation assistance is part of the file, it should be checked before the move-out plan is final.
If you need clear <a href="/start-short-sale">short sale help</a> before a move-out deadline gets too close, Crisp Short Sales can help review the file and identify the closing risks early.
Related guide: <a href="/the-short-sale-blog/short-sale-incentive-programs">short sale incentive programs</a>.
FAQ
Is short sale relocation assistance guaranteed?
No. It depends on the loan, investor, servicer, occupancy, approval terms, and closing conditions.
When is short sale relocation assistance paid?
It is often paid at or after closing, but the exact timing should be confirmed in the approval letter.
Can a seller lose relocation assistance?
Yes. Common risks include missed occupancy rules, expired approval terms, property condition issues, or closing delays.
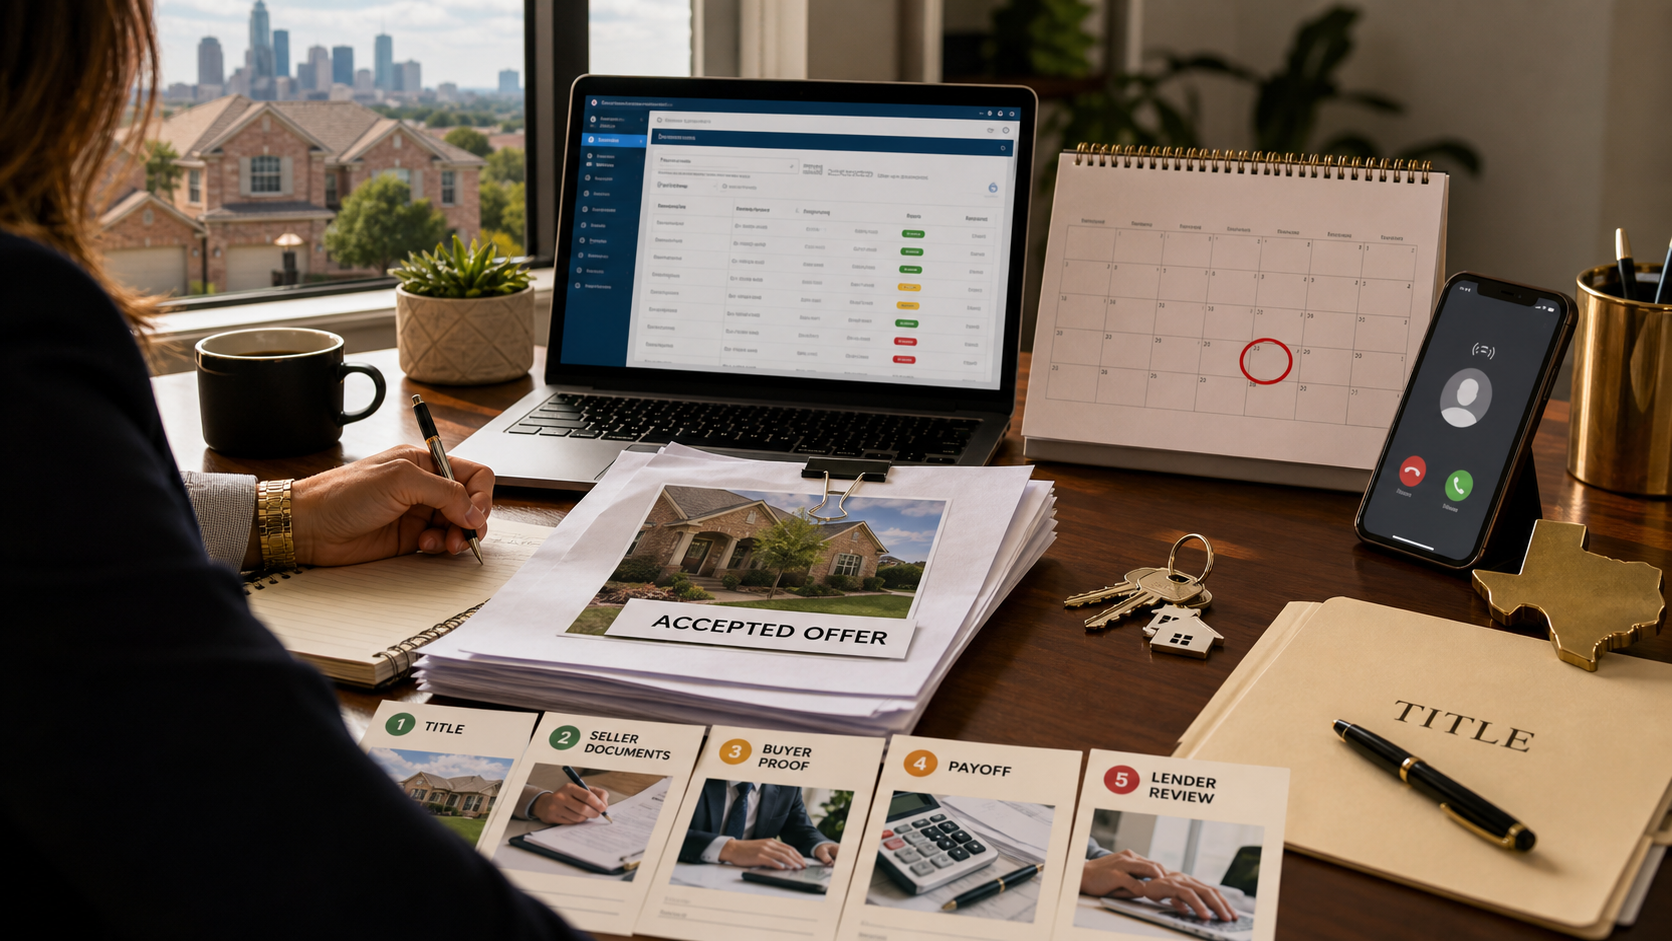
Houston Short Sale Timeline: What Agents Should Move First After the Offer
An accepted offer is a good start in a Houston short sale. It is not the finish line.
This is where many short sale files get quietly slower. The seller accepts the buyer's offer. The agents feel like the hard part is behind them. Everyone starts talking about closing.
But the lender has not approved the sale yet.
That matters because a short sale is not a normal listing where the seller can simply sign and move toward closing. The lender or servicer still has to review the offer, the seller hardship, the property value, the payoff, the settlement statement, the buyer's ability to close, and any other approval conditions.
In Houston and the rest of Texas, the timeline can feel especially tight when foreclosure pressure is already in the background. Texas foreclosure timelines can move quickly, so agents should not wait until the lender asks for the next item. The safer move is to front-load the file.
Step 1: Open Title Immediately
The title company should be involved as soon as the short sale offer is accepted.
Title issues do not care that the buyer is ready or that the seller wants the deal done. Old liens, unreleased mortgages, HOA balances, tax issues, judgment liens, probate questions, and payoff problems can all slow the file before closing.
This is why title should not wait until the lender is close to approval. If the title company finds a problem late, the short sale approval window may become harder to use.
For Texas files, this connects directly to the same closing risk covered in <a href="/the-short-sale-blog/texas-short-sale-title-problems-before-auction">Texas short sale title problems before auction</a>. The earlier title is opened, the more time the agent has to solve problems before lender approval becomes time-sensitive.
Step 2: Update the Seller Package Before It Goes Stale
Short sale documents can go stale quickly.
The lender may want current bank statements, pay stubs, hardship information, tax documents, authorization forms, and signed financial worksheets. If the seller package was gathered before the offer came in, the agent should assume at least some of it may need to be updated.
This is where clean <a href="/the-short-sale-blog/short-sale-processing-companies-check-first">short sale processing</a> helps. The processor or negotiator should check the package before submission, not after the servicer rejects it for missing or outdated items.
The goal is simple: make the first lender review as complete as possible.
Step 3: Confirm the Buyer Can Still Close
The lender will not only look at the seller.
The buyer's proof of funds, pre-approval, financing type, earnest money, inspection timing, and closing ability can all matter. If the buyer's documents are weak or outdated, the servicer may question whether the offer is real enough to approve.
Agents should confirm the buyer's current approval or proof of funds before the short sale package is submitted. If the buyer needs lender approval, condominium approval, investor approval, or extra underwriting time, that should be known early.
This is one reason a Houston short sale timeline should be managed as a live file, not a passive waiting period.
Step 4: Check Payoffs, Liens, and Net Sheet Numbers
The short sale package usually needs a settlement statement or net sheet that shows the lender what it would receive from the sale.
If the payoff is wrong, the HOA balance is missing, taxes are not estimated, or seller-paid costs are not handled correctly, the review can slow down. Worse, the lender may issue approval based on numbers that do not actually match the closing file.
That can create a problem later when title is trying to close and the numbers no longer fit.
Agents should treat the payoff and net sheet as living documents. They may need to be updated as the review moves forward.
Step 5: Watch the Foreclosure Date Before It Becomes the Emergency
If there is a foreclosure or auction date, it should be tracked from day one.
Waiting until the week of the sale date to ask for help is risky. The lender may need a complete short sale package before it will even consider postponement. Some investors or servicers require specific documents before they will review a delay request.
The broader <a href="/the-short-sale-blog/texas-short-sale-timeline-after-offer">Texas short sale timeline after the offer</a> matters here too: the faster the agent moves the file after acceptance, the better the chance of keeping foreclosure pressure from overtaking the deal.
Why Houston Short Sales Slow Down After the Offer
Most delays are not caused by one dramatic problem.
They usually come from ordinary missing pieces:
- The seller package is incomplete.
- The title company finds a lien late.
- The buyer's approval expires.
- The payoff changes.
- The servicer asks for updated documents.
- The foreclosure date gets too close.
- The settlement statement does not match the lender's expected net.
None of these issues are unusual. That is exactly why agents should expect them.
The best timeline is not built by waiting for the servicer to complain. It is built by checking the file before the servicer has a reason to pause review.
What Agents Should Do First
After the offer is accepted, the agent should move in this order:
- Open title and request the title search.
- Confirm the seller's hardship and financial package is current.
- Verify buyer proof of funds or financing.
- Request current payoff figures.
- Prepare the settlement statement or net sheet.
- Check HOA, tax, and lien issues.
- Submit a clean package to the servicer.
- Track every lender request and deadline.
That order gives the lender fewer reasons to slow the file down.
The Crisp Take
In a Houston short sale, the accepted offer is not the approval.
It is the point where the file has to become organized fast.
If title, seller documents, buyer proof, payoff figures, and the lender package are handled early, the agent has a better chance of keeping the file moving. If those pieces wait, the deal can lose days or weeks before anyone realizes the timeline is slipping.
That is why short sale help matters most after the offer, not only when the listing goes live.
For agents who want a cleaner file, the question is not just how long the lender will take. The better question is: what can we move today so the lender has less reason to delay tomorrow?
Related guide: <a href="/the-short-sale-blog/why-short-sales-take-so-long-bottlenecks-agents-can-fix">why short sales take so long</a>.
Short Sale Approval Letter Expired: What Happens Next?
Why an Expired Approval Letter Is a Real Problem
A short sale approval letter is not just a permission slip. It is a set of written closing instructions.
The lender or servicer may approve the sale only under specific terms: a specific buyer, purchase price, closing deadline, minimum net proceeds, approved closing costs, seller contribution, commission, junior lien payment, relocation assistance, and deficiency language.
When the approval letter expires, those terms may no longer be valid.
That does not always mean the short sale is dead. But it does mean the file needs attention before closing can move forward. A title company may not be comfortable closing on an expired approval. A buyer may not want to wait through another review. A servicer may require updated documents. A foreclosure deadline may keep moving in the background.
This is where short sale processing matters. The problem is not only getting approval. The problem is keeping that approval alive long enough to close.
The First Question: Did the Deadline Actually Pass?
Start with the exact approval-letter language.
Some letters say the sale must close by a specific date. Others say funds must be received by a certain date. Some may require the closing statement to match the approved numbers by the deadline. Others may include separate deadlines for relocation assistance, seller documents, or final payoff figures.
Agents should not rely on memory or a verbal update. Read the letter.
Then confirm:
- The approved closing deadline.
- Whether the approval has already expired.
- Whether the file is still inside the extension request window.
- Whether the buyer can close immediately if the extension is granted.
- Whether title, payoff, lien, or settlement statement issues are still unresolved.
If the deadline has not passed yet, move quickly. It is usually easier to request an extension before expiration than to revive a file after the deadline has already passed.
Why Short Sale Approvals Expire
Short sale approvals often expire because the lender is approving a specific deal at a specific point in time.
The lender's expected recovery can change. Payoffs can change. Taxes, HOA dues, title fees, interest, late charges, and legal costs can change. Buyer financing can change. The property's condition can change. Foreclosure timing can change.
The servicer may not want an old approval letter floating around if the numbers no longer match the file.
Common reasons approvals expire include:
- The buyer's loan is not ready.
- The appraisal or inspection caused a delay.
- The title company found a lien late.
- HOA, tax, judgment, or payoff numbers changed.
- The settlement statement does not match the approval.
- The buyer requested a closing credit or price change.
- The servicer requested updated seller documents.
- The foreclosure sale date created additional timing pressure.
Some of these problems can be solved. But they need to be handled before everyone assumes the same letter can still close the transaction.
Is an Extension Automatic?
No. A short sale approval extension should not be treated as automatic.
Some servicers may grant a short extension if the file is otherwise ready and the delay is minor. Others may require updated numbers, updated buyer documents, investor review, mortgage-insurance review, or a full resubmission.
The safest question is not, "Can we close late?"
The safer question is, "What does the servicer need in order to extend this exact approval?"
The short sale negotiator should ask for clear written direction. If the servicer approves an extension, the closing team should get the new date and any changed terms in writing.
What Can Trigger a New Review?
An expired approval letter becomes more risky when something material has changed.
A new review may be needed if:
- The buyer changed.
- The price changed.
- The closing date moved outside the allowed window.
- The settlement statement changed.
- Seller-paid costs changed.
- Buyer credits changed.
- Commission changed.
- Junior lien payments changed.
- HOA, tax, IRS, or judgment payoffs changed.
- The seller's financial situation changed.
- The foreclosure sale date is close.
- The investor or mortgage insurer requires updated approval.
Small changes can matter in a short sale because the lender is approving a net result, not just a contract.
If the final settlement statement does not match the approval letter, closing can stall even when the buyer and seller are ready.
What Agents Should Check Before Asking for an Extension
Before requesting an extension, agents and the short sale processor should make sure the file is actually ready to close.
Check:
- Is the buyer still committed?
- Is buyer financing clear enough to close quickly?
- Is the title company ready?
- Are all lien, HOA, tax, and payoff numbers current?
- Does the settlement statement match the approval letter?
- Are seller documents still current?
- Are relocation assistance terms still valid?
- Is the foreclosure timeline under control?
An extension request is stronger when the servicer can see that the file is close to closing and the delay has a clear reason.
It is weaker when the request sounds vague, the buyer is not ready, title is not clear, or the numbers do not match.
What Sellers Should Understand
Sellers may hear "approved" and think the short sale is finished.
That is understandable, but risky.
Short sale approval means the lender has agreed to specific written terms. It does not mean the seller can ignore deadlines, move-out rules, document requests, deficiency language, or final closing conditions.
If the approval expires, the seller should understand:
- The closing may be delayed.
- The servicer may require updated documents.
- The buyer may lose patience.
- Relocation assistance may need to be confirmed again.
- Deficiency or release language should be reviewed carefully.
- Foreclosure timing may still matter.
The seller should also be reminded that short sale approval is not legal or tax advice. If the approval letter discusses deficiency, debt forgiveness, taxable income, foreclosure rights, or release language, the seller should speak with the appropriate attorney or tax professional.
What Buyers Should Be Told
Buyers can tolerate some delay when the process is explained clearly.
They usually lose patience when nobody can tell them what is happening.
If the approval letter expired or is about to expire, the buyer should get a plain-English update:
- The approval has a deadline.
- The closing team is requesting or confirming an extension.
- The lender may need updated numbers or documents.
- The buyer should avoid changing terms unless absolutely necessary.
- The deal is not safe to close until the extension is confirmed.
This helps protect the transaction without promising something the servicer has not approved yet.
Why a Short Sale Specialist Helps Here
An expired approval letter is exactly the kind of issue that can look small until it becomes urgent.
A short sale specialist or negotiator can help:
- Read the approval letter against the settlement statement.
- Identify what changed before requesting the extension.
- Communicate with the servicer.
- Track updated documents.
- Confirm whether relocation assistance still applies.
- Watch for foreclosure timing.
- Help the agent and title company avoid closing on stale terms.
The goal is not to make the process more complicated. The goal is to keep the file from drifting into a preventable re-review.
Final Takeaway
If a short sale approval letter expires, do not assume the deal can still close on the old terms.
Check the deadline. Compare the letter against the settlement statement. Confirm whether the buyer, price, closing costs, title issues, junior liens, relocation assistance, and seller terms still match. Then get written extension approval before closing.
An expired approval letter does not always kill a short sale. But ignoring it can.
The best move is to treat the approval letter like a live closing document, not a past milestone. If the deadline is close or already missed, get short sale help before the buyer walks, title stalls, or the servicer sends the file back for another review.
Short Sales Near Me? When to Call a Short Sale Specialist
Why "Near Me" Is Only Part of the Search
It makes sense to search for short sales near you. Real estate is local. Foreclosure timelines, title issues, buyer expectations, and closing logistics often depend on the state, county, and local market.
But short sales are not only local.
They are also lender-driven.
That is the part many homeowners and agents underestimate. A short sale does not close just because the seller accepts an offer. The lender or servicer usually has to review the hardship, financial documents, purchase contract, estimated settlement statement, property value, title issues, investor rules, and closing terms before approval.
That means the best short sale help is not always the person closest to the property. It is the person who understands both the local real estate pressure and the lender approval process.
If you are searching "short sales near me," look for more than a nearby name. Look for someone who can explain what happens after the listing agreement is signed and before the approval letter arrives.
What a Short Sale Specialist Actually Does
A short sale specialist helps manage the approval path between the seller, listing agent, buyer, title company, and mortgage servicer.
That can include:
- Reviewing whether the file looks like a real short sale.
- Helping identify which documents the servicer may need.
- Checking for lender, investor, or mortgage-insurance requirements.
- Coordinating the short sale package.
- Watching for missing or expired financial documents.
- Tracking lender review and escalation points.
- Reviewing the approval letter before closing.
- Helping spot title, payoff, lien, or closing-window problems.
This is different from simply putting the home on the MLS.
A regular listing is mainly about marketing, offers, inspection, appraisal, and closing. A short sale adds a lender decision in the middle. That lender decision can change the timeline, require updated documents, reject costs, question the buyer, demand value review, or set a strict closing deadline.
That is why short sale processing matters. The file needs someone watching the lender side while the agent keeps the sale moving.
When a Regular Agent May Not Be Enough
Many strong agents can handle the real estate side of a short sale. They can price the property, communicate with buyers, manage showings, negotiate contract terms, and coordinate closing.
The problem is that short sales also require a separate skill set.
An agent may need help if:
- The seller has a foreclosure sale date.
- The agent has not handled a short sale recently.
- The servicer keeps asking for the same documents.
- The buyer is getting impatient.
- The file has multiple mortgages, liens, HOA balances, IRS issues, or judgment problems.
- The bank value does not match the contract price.
- The seller is missing financial documents.
- The approval letter has confusing conditions.
- The closing statement does not match what the lender approved.
None of those issues means the agent did anything wrong. They mean the file needs short sale experience before small gaps become bigger delays.
For agents, the right short sale specialist can protect the client relationship. The agent stays involved with the listing, buyer, and contract while the specialist helps manage the lender side.
Signs You Should Call Before the Offer Comes In
Many people wait too long to ask for short sale assistance.
They wait until the property is under contract. They wait until the buyer threatens to walk. They wait until the lender says the file is incomplete. They wait until title finds another lien. They wait until the foreclosure date is too close.
That makes everything harder.
Call earlier if any of these are true:
- The seller owes more than the home is likely to sell for.
- The seller cannot bring money to closing.
- Missed payments have already started.
- A foreclosure notice or sale date has arrived.
- The seller has more than one mortgage.
- There are HOA, tax, judgment, or lien concerns.
- The seller completed a loan modification, partial claim, forbearance, or other loss-mitigation plan.
- The buyer wants a normal closing timeline.
- The agent is unsure which documents the lender will require.
The earlier the file is reviewed, the easier it is to set expectations with the seller and buyer.
What Homeowners Should Ask a Short Sale Specialist
Homeowners should not choose short sale help just because someone appears in a local search.
Ask practical questions:
- Have you handled short sale files with lender approval before?
- What documents will my servicer likely need?
- How will you coordinate with my listing agent?
- What happens if there is a foreclosure date?
- Who communicates with the servicer?
- How do you track missing or expired documents?
- Will you review the approval letter before closing?
- What costs, if any, should I expect?
- Should I speak with an attorney, tax adviser, or housing counselor before making a decision?
The specialist should be able to explain the process in plain English. If the answer is only "list the home and see what happens," that is not enough.
A short sale is not a normal sale with a discount. It is a sale that needs lender consent. That approval path should be part of the plan from the beginning.
What Agents Should Ask Before Handing Over the File
Agents should also ask direct questions before trusting anyone with a short sale file.
Ask:
- Who prepares and tracks the short sale package?
- How are document requests handled?
- How often is the agent updated?
- Does the specialist review title and payoff issues?
- What happens if the lender value comes in too high?
- Who reviews the approval letter and settlement statement?
- Will the specialist communicate clearly with the title company?
- Does the agent keep control of the listing and client relationship?
Good short sale help should make the agent's job easier, not blur responsibilities.
The best setup is clear:
- The agent handles the listing, buyer, contract, and seller relationship.
- The title company handles title and closing requirements.
- The short sale specialist helps manage the lender approval process.
When those roles are clear, the file has fewer surprises.
Why Local Knowledge Still Matters
Even though the lender review is central, local knowledge still matters.
A short sale specialist should understand that a file in Georgia may have different practical pressure than a file in Texas, Pennsylvania, Ohio, or another state. Foreclosure timelines, notice periods, sheriff sale procedures, HOA expectations, buyer behavior, title customs, and closing practices can all affect the strategy.
But local knowledge should be paired with short sale process knowledge.
A local agent who has never handled a short sale may know the neighborhood but miss lender-review problems. A remote processor who ignores local title and foreclosure pressure may miss timing issues. The file usually needs both perspectives.
That is why agents and homeowners should look for help that can work with the local transaction while still controlling the short sale approval path.
What Can Go Wrong If You Wait
Waiting too long can create avoidable problems.
Common issues include:
- The buyer walks because the timeline was not explained.
- Seller documents expire during review.
- The lender rejects the package as incomplete.
- Title finds a junior lien late.
- HOA or payoff numbers change.
- The bank value comes in too high and no rebuttal is ready.
- The foreclosure sale date arrives before the file is complete.
- The approval letter arrives but the closing statement does not match it.
Some short sale delays are unavoidable. Lenders review files on their own timeline. Investors have their own rules. Buyers can change their minds.
But many delays are preventable when the file is organized early.
That is the main reason to call a short sale specialist before the file is already in trouble.
How Crisp Short Sales Helps
Crisp Short Sales helps agents and sellers with the short sale process so the lender side of the file does not get ignored.
The goal is not to replace the listing agent. The goal is to support the transaction where short sales are different from regular sales.
That can mean helping with:
- Short sale document organization.
- Servicer communication.
- Lender package tracking.
- Buyer and agent expectation setting.
- Escalation when the file stalls.
- Approval-letter review.
- Closing-risk checks before the deadline gets tight.
For agents, this can be the difference between guessing through the bank side and having a short sale processor involved from the beginning.
For sellers, it can mean a clearer path through a stressful situation.
Final Takeaway
Searching "short sales near me" is a reasonable first step, but location alone does not solve a short sale.
The better move is to find short sale help that understands lender review, documents, deadlines, title issues, buyer expectations, and approval-letter conditions.
If the seller owes more than the property is worth, foreclosure pressure is building, or the agent is unsure how to manage the lender side, call a short sale specialist before the file starts drifting.
The sooner the right person reviews the file, the better chance the agent and seller have to protect the deal before a preventable delay becomes a failed closing.
Social Pack
LinkedIn:
Searching "short sales near me" usually means the seller or agent is already under pressure.
But the closest name is not always the right help. A short sale needs someone who can manage the lender side: documents, servicer review, timelines, payoff issues, approval-letter conditions, and closing risk.
New Crisp Short Sales guide: [Squarespace URL]
#ShortSales #ShortSaleHelp #RealEstateAgents #ShortSaleProcessing #CrispShortSales
X:
Searching "short sales near me"?
Do not choose help based on location alone. A short sale specialist should know lender review, documents, deadlines, title issues, and approval-letter risks.
New Crisp guide: [Squarespace URL]
#ShortSales #ShortSaleHelp
Facebook:
Searching "short sales near me" usually means there is already pressure: missed payments, a foreclosure notice, a buyer waiting, or an agent trying to keep the file moving.
This new Crisp Short Sales guide explains when to call a short sale specialist and what to check before choosing help.
[Squarespace URL]
#ShortSales #ShortSaleHelp #RealEstateAgents #ShortSaleSpecialist
Reddit title:
Short sales near me: when to call a short sale specialist
Reddit:
New guide for agents and homeowners dealing with a possible short sale.
The post explains why "near me" is only part of the search. A short sale often needs someone who can manage lender review, missing documents, title/payoff issues, buyer expectations, foreclosure timing, and approval-letter conditions.
Reference guide: [Squarespace URL]
ActiveRain title:
Short Sales Near Me? When to Call a Short Sale Specialist
ActiveRain:
Searching "short sales near me" usually means the seller or agent is already under pressure.
The closest name is not always the right help. A short sale needs someone who can manage the lender side of the file, including document requests, servicer review, timelines, payoff issues, approval-letter conditions, and closing risk.
I wrote a new Crisp Short Sales guide on when to call a short sale specialist before the file starts drifting.
Original Crisp Short Sales article: <a href="[Squarespace URL]">Short Sales Near Me? When to Call a Short Sale Specialist</a>
Flipboard:
Searching "short sales near me" is often really a question about who can handle lender review, documents, deadlines, payoff issues, and approval-letter risk before a short sale stalls.
FHA Short Sale With a Partial Claim: What Agents Must Check Before Closing
Why FHA Partial Claims Matter in Short Sales
A partial claim can help an FHA borrower avoid foreclosure by moving past-due amounts into a separate, interest-free subordinate lien. HUD explains that a standalone partial claim places past-due amounts into a subordinate lien against the property, and repayment is generally deferred until a later trigger such as sale, transfer, assumption, payoff, or certain refinances.
That sounds simple until the property is being sold short.
In a normal sale with enough equity, the closing team can usually pay the first mortgage and any subordinate liens from the sale proceeds. In an FHA short sale, the proceeds are already short. The lender is being asked to approve a sale for less than the full amount owed. If a partial claim is also recorded, the short sale team has to understand how that separate balance affects the transaction.
This is where files can drift.
The seller may think the partial claim was "part of the mortgage." The agent may think the first mortgage payoff includes everything. The title company may find the lien later than expected. The buyer may already be waiting on approval. The servicer may need the numbers shown correctly before it can approve or clear the file.
None of that means the short sale cannot close. It means the partial claim has to be handled deliberately.
An FHA Short Sale Is a Pre-Foreclosure Sale
HUD uses the term Pre-Foreclosure Sale, often called PFS, for an FHA short sale. In plain English, it is a sale where the property sells for less than the amount owed and the lienholders agree to release their liens and forgive the deficiency balance under the applicable program requirements.
That definition matters because this is not just a private negotiation between an agent and a bank employee. FHA rules, servicer requirements, valuation, net proceeds, allowable costs, closing deadlines, title issues, and approval conditions can all affect the file.
When a partial claim is involved, the short sale has one more item that must be solved before closing.
The file is not just asking:
- Will the first mortgage investor accept the sale?
- Will the buyer stay in the deal?
- Will the seller sign?
- Can the closing happen before the deadline?
It also has to ask:
- Is there an outstanding partial claim or payment supplement balance?
- Is that balance shown correctly?
- Will the net sale proceeds still meet the required threshold after that payoff?
- If not, does the servicer need additional HUD approval before closing?
Those questions are easier to answer before the approval letter is issued than they are during the final week of closing.
The Partial Claim Is Often a Separate Payoff Problem
One common mistake is assuming the first mortgage payoff automatically includes the partial claim.
It may not.
The partial claim can appear as a separate subordinate mortgage or Secretary-held lien. It may have its own payoff process. It may require separate instructions. It may show up in title as a second lien even though it came from FHA loss mitigation.
That is why title work matters early in an FHA short sale.
The short sale processor, negotiator, listing agent, and title company should not wait until final approval to ask whether there is a partial claim. The better approach is to ask upfront and then verify through title and servicer communication.
Look for clues such as:
- The seller completed a prior FHA partial claim.
- The seller received a COVID-era or post-hardship loss-mitigation option.
- The seller signed a subordinate mortgage or note.
- Title shows a HUD, Secretary-held, partial claim, or subordinate lien.
- The payoff demand does not match the seller's memory of what is owed.
- The servicer mentions payment supplement, partial claim, or subordinate mortgage balance.
If any of those clues appear, pause and clarify the payoff treatment before relying on the net sheet.
Why This Can Break the Closing Statement
The settlement statement is where the partial-claim problem becomes visible.
If the partial claim has to be paid, the closing statement must show the payoff correctly. If the payoff reduces the net proceeds too much, the FHA short sale may no longer meet the required net proceeds threshold without additional approval.
HUD's PFS guidance says the mortgagee must ensure outstanding partial claims and payment supplements are paid in full, deduct those balances from net sale proceeds, and make sure the proceeds satisfy those balances. It also says that if the net proceeds fail to meet the applicable requirement after satisfying the partial claim or payment supplement, the mortgagee must obtain HUD approval through the required channel before closing.
For agents, the takeaway is practical:
A deal can look approved at the purchase-price level and still have a closing problem if the partial claim was not handled in the numbers.
That can lead to last-minute settlement statement corrections, revised approval terms, closing delays, buyer frustration, title clearance problems, or a file that has to go back for review.
What Agents Should Ask Before the FHA Short Sale Package Goes In
Before the short sale package is submitted, ask the seller and servicer direct questions:
- Has the borrower ever completed an FHA partial claim, payment supplement, or loan-modification package?
- Is there a recorded subordinate mortgage or HUD-held lien?
- Does the title search show a separate payoff item?
- Who provides the payoff for the partial claim?
- Does the servicer's estimated net account for the partial claim?
- Will the partial claim be paid from sale proceeds?
- If the partial claim reduces net proceeds below the target, what approval path is needed?
The point is not to turn the listing agent into a HUD claims expert. The point is to make sure the issue is flagged early enough that the short sale negotiator and title company can control it.
What Sellers Should Understand
For FHA borrowers, the biggest misunderstanding is that a partial claim "went away" because the monthly payment problem was solved at the time.
That is usually not how it works.
A partial claim may have helped cure the default or make the loan current, but the balance can remain attached to the property as a subordinate lien. When the property is sold, the payoff question comes back.
That can surprise sellers who are already stressed by foreclosure pressure, moving plans, buyer deadlines, and hardship documentation.
Sellers should ask:
- Did I sign a partial claim or subordinate mortgage?
- Is there a separate HUD payoff?
- Will the partial claim affect whether my FHA short sale can close?
- Will the approval letter or closing statement show how it is handled?
- Should I speak with an attorney, tax adviser, housing counselor, or other professional before closing?
Agents should be careful not to give legal, tax, credit, or HUD-benefit advice. But they can help the seller ask better questions and avoid discovering the lien too late.
What the Approval Letter Should Not Leave Unclear
Once the FHA short sale approval letter arrives, the file should be checked against the closing statement before anyone assumes it is ready.
Review:
- Approved sale price.
- Closing deadline.
- Approved costs.
- Required net proceeds.
- Seller contribution, if any.
- Deficiency or release language.
- Treatment of junior liens.
- Treatment of partial claim or payment supplement balances.
- Any condition requiring updated settlement statement approval.
If the approval letter is silent but title shows a partial claim, do not assume silence means the issue is solved. Ask the servicer or short sale contact to clarify before closing.
If the closing statement shows a payoff that was not included in the approval review, the file may need correction.
This is where experienced short sale processing matters. The issue is not just uploading documents. It is matching the approval terms, payoff demands, title requirements, and settlement statement before the closing window runs out.
How to Keep the File From Stalling
The safest workflow is straightforward:
- Confirm the loan is FHA-insured.
- Ask about prior loss mitigation, partial claim, payment supplement, or modification history.
- Order title early.
- Identify any HUD-held or subordinate lien.
- Request payoff treatment before final approval.
- Make sure the estimated settlement statement shows the numbers correctly.
- Recheck the approval letter against the final settlement statement before closing.
This does not make every FHA short sale easy. It does reduce preventable surprises.
Most FHA short sale problems are easier to solve when they are found while the package is being built. They become much harder when the buyer is ready to close, the foreclosure clock is still moving, and the title company suddenly needs a payoff that was never built into the approval.
Final Takeaway
An FHA partial claim can be the hidden issue that turns a routine short sale approval into a closing problem.
If the borrower has a partial claim, payment supplement, or HUD-held subordinate lien, the short sale team needs to know early. The payoff has to be accounted for. The settlement statement has to match the approval path. Title has to clear. And if the numbers fall outside the required FHA short sale threshold, the servicer may need additional approval before closing.
The best move is simple: do not wait for the partial claim to appear at the closing table.
Find it early, price the file correctly, document the payoff, and get short sale help before a fixable lien issue turns into a failed closing.
Why Do Short Sales Take So Long? 7 Bottlenecks Agents Can Fix
Why Short Sales Take Longer Than Regular Sales
A regular sale is mostly a contract between buyer and seller.
A short sale adds another decision-maker: the lender or servicer. The lender must decide whether to accept less than the full mortgage payoff. That means the file has to prove hardship, value, buyer strength, settlement numbers, title status, and closing feasibility.
That extra review is why short sales often move slowly.
But "the bank is slow" is not the whole answer. Many short sale delays start before the lender ever makes a decision.
Here are seven bottlenecks agents can often fix.
1. The File Is Submitted Before It Is Complete
A short sale file can look submitted and still not be ready for review.
The servicer may need a hardship letter, financial forms, tax documents, pay stubs, bank statements, authorization forms, listing agreement, purchase contract, buyer proof of funds or pre-approval, estimated settlement statement, and other investor-specific forms.
If one item is missing, expired, unsigned, or inconsistent, the file can sit.
Agents should not assume "submitted" means "in review." A short sale processor or coordinator should confirm exactly what the servicer has accepted and what is still open.
The fix is simple: build a complete document checklist before submission and track every missing item until the lender confirms the package is complete.
2. Seller Documents Expire During Review
Short sale documents often have a shelf life.
Bank statements, pay stubs, financial forms, payoff statements, and hardship documents may need updates if the review takes too long. That can restart parts of the process or create new lender requests.
This is frustrating because nobody thinks a file is stuck. Everyone thinks they are waiting.
Then the servicer asks for updated documents, and the clock resets.
Agents can reduce this delay by tracking document age. If the file has been sitting for several weeks, the short sale coordinator should know which documents are likely to expire next and request updates before the lender asks.
3. The Value Review Does Not Match the Offer
The lender usually needs a value review before approving the short sale. That may be a BPO, appraisal, desktop review, or investor valuation process.
If the bank's value comes in higher than the offer, the short sale can slow down quickly.
The lender may counter. The buyer may refuse. The seller may not have room to close. The file may need repair photos, comparable sales, condition notes, access details, or a value dispute.
Agents can help by preparing value evidence early, especially when the property has condition issues or the offer is below nearby sales.
A short sale negotiator should not wait until a bad value arrives to start gathering proof. If value is likely to be an issue, prepare the file before review.
4. Title, Liens, or HOA Issues Surface Too Late
Short sales can also stall because the first mortgage is not the only closing problem.
Title may show a second mortgage, judgment, tax lien, HOA balance, code lien, probate issue, divorce issue, missing signature, or old payoff problem.
If those issues are discovered after lender approval, the closing window can become very tight.
Agents should order title work early when possible and ask about HOA balances, unpaid dues, collection fees, and other liens before the approval letter arrives.
This is where short sale coordination matters. The lender review and title review should move in parallel. If title waits until the end, a workable short sale can still miss closing.
5. Buyer Changes Force a New Review
Short sale approvals are often tied to a specific buyer, price, net amount, and settlement statement.
If the buyer changes financing, asks for repairs, requests a credit, delays closing, or tries to renegotiate after inspection, the lender may need to review the file again.
That does not always kill the deal, but it can add time.
Agents should explain this early to the buyer's side. A short sale buyer needs to understand that normal contract changes may not be normal in a short sale.
Before agreeing to any change, confirm whether the lender needs updated approval.
6. Nobody Owns the Follow-Up Cadence
Short sale files often sit because everyone assumes someone else is following up.
The listing agent thinks the processor is handling it. The processor thinks the servicer will update the portal. The buyer's agent keeps asking for news. The seller gets nervous. Meanwhile, a lender task or missing note may be sitting unresolved.
A good short sale negotiator should have a follow-up cadence.
That means tracking:
- When the file was submitted.
- When the servicer confirmed receipt.
- What documents are still pending.
- When valuation was ordered.
- When investor review started.
- When the next follow-up is due.
- Whether escalation is needed.
- Whether a foreclosure or closing deadline is approaching.
Patience is not the same as file control.
7. The Approval Letter Creates New Closing Conditions
Even when the short sale is approved, the file may not be clear to close.
The approval letter may include a closing deadline, required net proceeds, approved costs, commission limits, junior lien instructions, seller contribution terms, relocation language, deficiency language, or settlement statement requirements.
If the final closing documents do not match those terms, title may not be able to close.
That is why the approval letter needs to be reviewed carefully before everyone relaxes. Approval is progress, but it is still conditional.
A strong short sale processor should compare the approval letter against the contract, title report, payoff demands, settlement statement, and closing date.
What Agents Can Do to Speed Up a Short Sale
Agents cannot force a lender to approve a short sale overnight.
But they can reduce avoidable delays.
The best approach is to control the file early:
- Collect a complete document package before submission.
- Track document expiration dates.
- Prepare value evidence if the offer may be challenged.
- Order title and check HOA issues early.
- Set buyer expectations before inspection or financing changes.
- Keep a clear follow-up schedule with the servicer.
- Review the approval letter before closing pressure builds.
That is the difference between waiting passively and managing the file.
When to Bring in Short Sale Help
Bring in short sale help when the seller may not have enough equity to close normally, the lender needs a complete hardship package, title is complicated, foreclosure pressure is building, or the agent does not have time to chase the servicer consistently.
A short sale specialist can help organize the package, communicate with the servicer, track review stages, respond to document requests, coordinate with title, and flag approval-letter risks before closing.
The earlier that help starts, the less likely the file is to become an emergency.
Bottom Line
Short sales take longer because more parties, documents, approvals, and deadlines are involved.
But not every delay is unavoidable.
Agents can prevent many problems by submitting a complete file, tracking expiring documents, preparing for value review, clearing title and HOA issues early, managing buyer changes carefully, following up consistently, and reviewing the approval letter before closing.
If the file is already slowing down, do not just wait for the bank. Find the bottleneck and fix the part that can be fixed.
FAQ
Why do short sales take longer than regular sales?
Short sales take longer because the lender must approve the sale for less than the full mortgage payoff. That adds document review, value review, investor approval, title review, and approval-letter conditions.
What slows down short sale approval?
Common delays include missing seller documents, expired financials, valuation disputes, title or HOA issues, buyer changes, poor follow-up, and approval-letter conditions that do not match the closing documents.
Can an agent speed up a short sale?
An agent cannot force lender approval, but they can reduce delays by submitting a complete file, tracking deadlines, preparing value evidence, checking title early, and using a short sale negotiator or processor.
When should a short sale file be escalated?
Escalation may be needed when the servicer goes quiet, a foreclosure deadline is approaching, documents have been repeatedly requested, value review is stuck, or the file has passed normal review timelines.
VA Short Sale Timeline: What Agents Should Check After the Offer Comes In
Offer in on a VA short sale? See what agents should check next: value review, title, foreclosure timing, approval terms, and closing deadlines.
A VA short sale does not become easier just because an offer is finally in hand. In many files, the offer is when the real review begins.
For agents, this is the point where the timeline needs to get tighter. The seller may already be behind on payments. The buyer wants answers. The servicer needs a complete file. Title may still have open issues. If there is a foreclosure date, every missing document can cost time the seller may not have.
This guide focuses on what agents should check after the offer comes in on a VA-backed short sale.
Confirm the offer matches the short sale reality
Before sending the offer to the servicer, make sure the contract fits the file. Review the price, financing type, closing date, seller-paid costs, inspection terms, repair requests, buyer credits, and any unusual conditions.
A VA short sale can stall when the offer looks acceptable on the surface but creates a net proceeds problem for the lender. The contract should be reviewed together with the estimated settlement statement so everyone understands what the servicer is actually being asked to approve.
Check whether the seller package is complete
An offer without a complete seller package is not enough. The servicer may need a hardship letter, financial worksheet, pay stubs, bank statements, tax documents, listing agreement, purchase contract, buyer proof of funds or pre-approval, authorization forms, and other file-specific items.
Do not assume the servicer will start full review while basic documents are missing. If the seller package is incomplete, the file can sit, expire, or be pushed back into document collection.
For agents, the safest next step is to confirm exactly what the short sale processor, short sale negotiator, or servicer still needs before promising a timeline.
Prepare for the value review
Once the offer is in, the lender will usually review the property value. That may involve a broker price opinion, appraisal, condition review, comparable sales review, or an internal valuation process.
Agents should prepare the value story before the bank pushes back. Gather repair photos, condition notes, market feedback, price reduction history, nearby comparable sales, and anything that explains why the offer reflects the real market.
If the property needs repairs, has access problems, has deferred maintenance, or has buyer objections, document it clearly. A weak value package can lead to a high valuation, a counteroffer, or a rejected short sale.
Review foreclosure timing immediately
If there is a foreclosure sale date, the offer does not automatically stop it. The servicer may require a complete short sale package before considering a postponement.
That means timing should be reviewed as soon as the offer comes in. Agents should know the foreclosure date, the servicer’s document deadline, whether a postponement request has been submitted, and what is still missing from the file.
A VA-backed loan may still need servicer and investor review. Waiting until the last few days to organize the file is risky.
Order title review early
Title issues can stop a short sale even after the first lender is ready to approve. Junior liens, HOA balances, tax liens, judgments, code liens, probate issues, missing signatures, or old payoff problems can all delay closing.
After the offer comes in, title should be reviewed quickly. The goal is to identify anything that needs payoff approval, lienholder negotiation, seller documentation, or legal clarification before the approval letter is issued.
The approval letter usually has a deadline. If title problems are discovered too late, the buyer and seller may not have enough time to fix them before the approval expires.
Do not overpromise relocation money or deficiency language
Veteran homeowners may ask whether they can receive relocation assistance, whether they will owe money after closing, or whether the short sale affects future VA loan eligibility.
Those questions matter, but the answer must come from the actual approval terms and file review. Agents should not promise relocation money, debt forgiveness, or future loan treatment based on a prior file or a general article.
The safe answer is that those items need to be confirmed in writing through the servicer approval process.
Watch the approval letter closely
When the approval letter arrives, read it line by line. Confirm the approved buyer, approved net proceeds, closing deadline, commission treatment, seller contribution language, relocation language, deficiency language, junior lien limits, and any restrictions on repairs or credits.
A short sale approval letter is not just a permission slip. It is the closing instruction sheet. If the letter does not match the contract or settlement statement, the issue should be addressed before closing.
Keep buyer expectations under control
Buyers can get impatient during short sale review. That is normal. But the buyer should understand that the servicer’s approval controls the closing timeline.
Agents should keep buyer-side communication clear. Explain what has been submitted, what is pending, what cannot be promised, and what deadlines matter. A buyer who understands the process is less likely to walk away during review.
Use one clear file coordinator
A VA short sale can involve the seller, listing agent, buyer’s agent, servicer, title company, junior lienholders, HOA, and sometimes foreclosure counsel. If everyone communicates separately, important details can get lost.
One person should coordinate the file status, document requests, servicer follow-up, approval terms, and closing conditions. That may be the agent, a short sale processor, a short sale negotiator, or a short sale specialist.
The goal is not more activity. The goal is cleaner communication and fewer preventable delays.
Post-offer checklist for agents
After the offer comes in, confirm:
- The contract terms match the short sale file.
- The estimated net proceeds are realistic.
- The seller package is complete.
- The hardship documents are current.
- The buyer proof of funds or pre-approval is included.
- The property value story is documented.
- The foreclosure date and postponement status are known.
- Title has been reviewed.
- HOA and junior lien balances are identified.
- No one has promised relocation money or deficiency treatment too early.
- The approval letter will be reviewed before closing.
Final takeaway
A VA short sale offer is an important step, but it is not the finish line. Once the offer comes in, the agent needs to tighten the file, confirm the timeline, prepare for value review, check title, and manage expectations until the approval letter and closing are complete.
The files that move best are usually the files where the agent does not wait for the servicer to find the problems first.
Crisp Short Sales helps agents with VA short sale processing, short sale negotiation, and file coordination so the offer can move through review with fewer preventable delays.
Are Short Sales Rising? 7 Market Signals for Agents
Short sales do not rise everywhere at once. These seven local market signals can help agents decide when more sellers may need short sale help before foreclosure pressure becomes urgent.
Fast Answer
Short sales do not rise everywhere at the same time, and one hard listing does not prove a trend. Agents get a clearer answer by watching several local signals together: longer time on market, repeated price reductions, thinner equity, growing repair pressure, payment stress, more foreclosure activity, and more sellers who need to move before the numbers work.
When several of those signals appear in the same market, a short sale specialist can help agents prepare for more seller conversations before those files become urgent.
Are Short Sales Rising? Start With the Local Market, Not a Headline
National headlines can be useful background. They cannot tell an agent exactly what is happening in a neighborhood, price band, or lender mix.
Short sales usually become more relevant when a seller cannot sell for enough to pay the mortgage and close normally. That situation can develop because values soften, costs rise, a seller's payment changes, a move becomes unavoidable, repairs reduce the buyer pool, or a foreclosure deadline starts to control the timeline.
The practical question is not whether every market is seeing more short sales. It is whether conditions in your local market are likely to create more short sale referrals.
Here are seven signals worth tracking.
1. Listings Are Taking Longer to Sell in the Same Price Band
Days on market are not a short sale statistic by themselves. They are a pressure signal.
When homes take longer to sell, sellers carry mortgage payments, taxes, insurance, HOA dues, and repair costs for more time. A seller with plenty of equity can adjust. A seller with thin equity can run out of room quickly.
Watch the price range and property type where listings are lingering. If a seller must reduce the price after several extra months of carrying costs, the sale may no longer cover the payoff and normal closing expenses.
That is a market-level reason to become more proactive about short sale help, even before any particular seller says they are in trouble.
2. Price Reductions Are Clustering, Not Just Appearing Occasionally
Every market has some price reductions. The useful signal is a pattern.
When multiple comparable homes are cutting price, sellers can lose their original equity cushion. An agent should look at whether reductions are shallow adjustments or whether similar properties are repeatedly chasing the market down.
This matters because a seller may still quote an older value while buyers are responding to the newer one. If the likely sale price falls below the mortgage payoff after costs, a lender-approved short sale may become part of the conversation.
For the individual-file checklist, see the guide on early warning signs on an individual listing. The market signal here is different: reductions are happening across comparable listings, not just one difficult home.
3. Equity Is Thinner Than It Looked at the Start of the Year
Thin equity is the bridge between a challenging market and a potential short sale.
Agents do not need to know every seller's private mortgage balance to recognize a market where equity may be fragile. Look for recent high-balance purchases, refinance-heavy price bands, homes with deferred maintenance, and areas where sale prices are no longer supporting last year's expectations.
Then run a realistic net sheet when a seller asks for help. Account for the mortgage payoff, taxes, HOA amounts, liens, commissions, concessions, repairs, and closing costs. The question is not whether the seller wants a certain price. The question is whether the likely net can close the deal.
When it cannot, early short sale processing can prevent a buyer contract from becoming an unpleasant surprise.
4. Property Condition Is Creating a Bigger Discount Than Sellers Expect
In a hot market, some condition issues are easier to work around. In a slower or more selective market, repair needs can shrink the buyer pool and reduce the price a buyer will support.
Watch for roof age, water damage, outdated systems, insurance issues, deferred maintenance, tenant wear, and properties that need cash buyers. Those problems can force a seller to accept a lower offer while still carrying a high payoff.
Condition also affects the bank's value review. A short sale BPO or appraisal may not tell the full story unless the file has useful photos, repair information, local comparable sales, and a clear explanation of marketability. That is why the bank's value review deserves attention before the lender sees only a number.
5. More Sellers Are Facing a Payment or Life-Change Deadline
Market data tells only part of the story. Seller circumstances turn pressure into a timeline.
Listen for payment changes, job moves, reduced income, divorce, medical events, inherited-property costs, military relocation, or a need to move before the home is ready to sell. An agent may hear these reasons one at a time. A rise in similar conversations is a meaningful local signal.
The short sale conversation should begin while the seller still has room to gather documents, list strategically, and evaluate options. A seller should not have to wait for missed payments or a foreclosure date before asking what is possible.
6. Foreclosure Notices and Distress Questions Are Showing Up More Often
An agent should not offer legal advice about a notice or deadline. An agent should take it seriously.
When sellers increasingly ask about default letters, foreclosure filings, servicer calls, auction dates, or whether a sale can happen before foreclosure, the market may be developing a real short sale pipeline. It is especially important if those questions are appearing alongside thin equity and lower sale prices.
The right response is to get the relevant date, confirm the payoff and property facts, and connect the seller to qualified short sale assistance early. The short sale versus foreclosure decision should be made with enough time to act, not after the file has become a deadline emergency.
7. Your Agent Network Is Seeing the Same Friction
Often the earliest useful signal is not a public data set. It is a repeated conversation.
Pay attention when multiple agents report the same themes: sellers who cannot net enough, buyers asking for larger concessions, houses sitting longer after price cuts, loan payments that no longer fit, repair-heavy homes, or title and payoff issues surfacing late.
That does not prove short sales are rising across an entire state. It does suggest that your market may benefit from a cleaner referral path to a short sale negotiator or coordinator.
The goal is not to label every distressed listing as a short sale. The goal is to recognize when a normal sale may no longer solve the seller's problem.
A Simple Monthly Market Check for Agents
Once a month, review the same seven areas in your core market:
1. Days on market for your usual price range.
2. The share and size of recent price reductions.
3. Likely seller equity after a realistic net sheet.
4. Repair and condition issues limiting buyer demand.
5. Seller timeline or payment-change conversations.
6. Distress notices and foreclosure-related questions.
7. Repeated concerns coming from agents, title, and local buyers.
You are not trying to forecast the entire housing market. You are building an early-warning system for when more sellers may need a conversation about their actual options.
When to Bring in a Short Sale Specialist
Bring in short sale help when the likely sales proceeds may not cover the payoff and costs, the seller has a hardship or deadline, or a normal sale is becoming less realistic with each week that passes.
A good short sale specialist can help the agent assess the file, organize documents, communicate with the servicer, review lender terms, and protect the closing timeline. The agent remains central to the listing and seller relationship while the short sale negotiator handles the bank side of the process.
For a seller already feeling pressure, the useful next step is to start the short sale process before foreclosure timing makes every option harder.
Bottom Line
Are short sales rising? The answer may be yes in some local pockets and no in others. The better question for agents is whether several market-pressure signals are starting to overlap where they work.
Longer marketing times, clustered price cuts, thin equity, condition discounts, seller life changes, distress notices, and repeated agent conversations can all point toward more short sale referrals ahead.
When those signals line up, act early. A short sale specialist can help turn a vague concern into a clear file strategy before the seller runs out of time.
FAQ
Are short sales increasing right now?
Short sale activity varies by local market, seller equity, lender requirements, and homeowner circumstances. Agents should watch local market pressure and seller situations rather than relying only on national headlines.
What market conditions can lead to more short sale referrals?
Longer marketing times, repeated price reductions, softer values, thin equity, repair-heavy homes, payment stress, and more foreclosure-related questions can all create more short sale opportunities.
How can agents tell market stress from one difficult listing?
One listing may have unique problems. A market trend appears when similar price, condition, timing, and seller-pressure issues show up repeatedly across comparable properties and agent conversations.
When should an agent bring in a short sale specialist?
Bring in a specialist when the likely sales proceeds may not cover the mortgage payoff and costs, or when the seller has hardship, a deadline, title/payoff problems, or foreclosure pressure.
If the Buyer Delays Closing, Can You Lose Short Sale Relocation Assistance?
Why Buyer Delays Matter in a Short Sale
In a regular sale, a buyer delay is frustrating. In a short sale, it can be more than frustrating.
That is because the lender or servicer has approved a specific deal under specific written terms. The approval letter may include the buyer, purchase price, lender net, closing deadline, allowed costs, seller contribution, junior lien payments, and relocation assistance.
If the buyer cannot close on time, the short sale may need an extension. That extension is not just a calendar change. It may require the servicer to review the file again, confirm the buyer is still viable, check updated payoffs, and approve the settlement statement again.
For a seller relying on relocation assistance, that matters. Move-out money is often tied to closing, written approval terms, occupancy, property condition, and deadlines. A buyer delay can put one or more of those pieces under pressure.
The Approval Deadline Is the First Risk
The first question is simple: when does the short sale approval expire?
Many approval letters are only valid through a specific closing date. If the buyer's lender, title company, or buyer documents are not ready, the file may need an extension before closing can happen.
Agents should not assume the extension is automatic.
The short sale negotiator should confirm:
- Whether the approval letter can be extended.
- How the extension request must be submitted.
- Whether updated buyer documents are required.
- Whether a revised settlement statement is needed.
- Whether the relocation assistance remains approved after the extension.
If the extension is approved in writing and the relocation terms stay the same, the seller may still be fine. If the approval expires without a confirmed extension, the relocation money can become uncertain.
This is why the timing matters. A short sale processor should ask for the extension before the file runs out of room.
Relocation Assistance May Have Conditions
Short sale relocation assistance is usually not just a gift handed over because the seller is moving.
It may depend on specific conditions. Those conditions can include occupancy, cooperation, property condition, closing by the approved date, no prohibited side payments, and correct disclosure on the settlement statement.
A buyer delay can create problems if:
- The seller moves out too early and the program required occupancy.
- The property condition changes before closing.
- The approval deadline passes.
- The buyer asks for credits that reduce the lender's net.
- The settlement statement changes and no longer matches the approval.
- The servicer requires updated documents and the seller does not respond.
That does not mean every buyer delay cancels the payment. It means the file needs to be checked before anyone promises the seller that the money is still protected.
The Settlement Statement Still Has to Match
Even if the approval letter says relocation assistance is allowed, the final settlement statement still has to show the payment correctly.
This is where buyer delays can create quiet problems. Extra interest, updated taxes, HOA balances, buyer credits, extension fees, title changes, or revised payoffs can change the numbers.
If the lender approved a minimum net, the settlement statement needs to preserve that net. If the relocation payment is shown incorrectly, missing, or moved around to solve another closing problem, the servicer may reject the file or require changes.
Agents should look for one clean answer:
Does the final settlement statement match the written approval, including the relocation assistance?
If the answer is no, fix it before closing.
What Agents Should Ask When the Buyer Is Delayed
When a buyer delay appears, the agent should avoid vague updates like "we just need a few more days."
The better questions are specific:
- Is the buyer still fully committed and able to close?
- What exact issue caused the delay?
- Is the short sale approval still valid through the new closing date?
- Does the servicer require a written extension?
- Is the relocation assistance still approved after the extension?
- Does the seller still meet the occupancy or move-out conditions?
- Does the updated settlement statement still match the approval?
These questions help the short sale negotiator protect the file instead of reacting after the deadline has already been missed.
What Sellers Should Not Do
Sellers should not assume relocation money is safe just because it was mentioned earlier in the process.
They should also be careful about moving too early, damaging the property, refusing updated documents, ignoring extension requests, or scheduling a move around money that has not been confirmed in writing.
The seller may be frustrated, and that is understandable. A buyer delay can create real costs. The seller may have already planned a move, arranged storage, or counted on funds at closing.
But in a short sale, the written approval controls the money. If the approval letter or extension does not protect the relocation assistance, the seller should not rely on assumptions.
When the Money Is Probably Still Safe
Relocation assistance is more likely to survive a buyer delay when the approval is still active, the extension is requested before expiration, the seller still meets all conditions, and the settlement statement still matches the approved terms.
It also helps when the delay is short, the buyer is still strong, title is ready, and the servicer gives written confirmation.
In that situation, the short sale specialist may only need to document the extension and keep the closing package aligned.
When the Money Is at Higher Risk
The risk rises when the approval has already expired, the buyer is uncertain, the seller has moved out too early, the property condition has changed, the net proceeds have dropped, or the servicer requires a full re-review.
The risk also rises if the relocation assistance was never clearly listed in the approval letter.
If the seller is depending on the funds, the file should be escalated before closing. Waiting until the day of signing is the wrong time to discover that the move-out money was not protected.
Bottom Line
A buyer delay does not automatically cancel short sale relocation assistance, but it can put the payment at risk.
The approval letter, extension approval, seller eligibility, and settlement statement all need to line up. If one of those pieces changes, the short sale negotiator should confirm the relocation payment in writing before the seller counts on it.
The practical rule is simple: do not treat relocation money as safe unless it is still approved after the delay and still matches the final closing documents.
If a short sale is close to approval or already approved and the buyer is starting to slip, start the short sale process review before the deadline turns a solvable extension into a lost payment.
FAQ
Can a buyer delay cancel short sale relocation assistance?
It can, depending on the approval terms. The payment may be at risk if the delay causes the approval to expire, changes the lender's net, requires re-review, or causes the seller to miss occupancy or move-out conditions.
Does relocation money need to be reapproved after a closing extension?
Often, the safest answer is yes. If the closing date changes, the negotiator should confirm in writing that the relocation assistance is still approved and still allowed on the settlement statement.
Should a seller move out before the buyer is clear to close?
Not without checking the approval terms. Some relocation assistance depends on occupancy or move-out timing. Moving too early can create avoidable risk if the program requires the seller to meet certain conditions through closing.
What should agents check first when a buyer delay happens?
Check the approval deadline, extension requirements, relocation-assistance language, buyer readiness, and settlement statement. Those items determine whether the file is still safe to close.
Can You Ask for Short Sale Move-Out Money After Approval?
Why This Question Comes Up Late
A short sale approval can feel like the hard part is over. The lender reviewed the file, accepted the offer, and gave everyone a path to closing.
Then someone asks the question that should have come up earlier:
Can the seller still get move-out money?
That question matters because short sale move-out money is not just a nice extra. For some sellers, it affects whether they can afford a deposit, truck rental, temporary housing, storage, or a clean handoff of the property. For agents, it can also affect expectations right before closing.
The problem is timing.
By the time a short sale is approved, the lender or servicer has usually approved a specific deal. The approval may name the buyer, purchase price, closing deadline, allowed costs, lender net, junior lien payments, seller contribution, and whether the seller can receive any funds at closing.
If move-out money is missing from those terms, it may not be something the closing team can casually add later.
The Approval Letter Controls the Answer
The first document to review is the short sale approval letter.
Look for any language about relocation assistance, seller incentive funds, transition assistance, cash for keys, occupancy, seller proceeds, seller contribution, or disallowed payments.
The approval letter may answer the question directly. It might say the seller is approved for a specific relocation amount. It might say the seller may not receive any funds from closing. It might require the seller to occupy the property through a certain date. It might require the payment to appear on the final settlement statement.
If the approval letter says the seller is eligible and the amount is clear, the next step is making sure the closing documents match.
If the approval letter is silent, vague, or says no seller proceeds are allowed, do not assume the payment can be added. A short sale processor or negotiator should review the terms before closing and decide whether the file can be escalated, corrected, or whether the window has already closed.
Why Move-Out Money Is Not Automatic
Short sale incentive programs vary by lender, investor, servicer, loan type, and file status. A seller may have qualified in one file and be denied in another. A payment that was available under one old program may not apply to the current approval.
Some payments depend on occupancy. Some depend on the seller leaving the property in acceptable condition. Some require no rent-back arrangement. Some require the final settlement statement to show the payment exactly as approved. Some are blocked if the lender's net proceeds fall below the approved amount.
That is why an agent should be careful with phrases like "the seller should get relocation money" or "the bank usually pays sellers to move."
The better question is narrower:
Is this seller eligible for a written, approved move-out or relocation payment on this specific short sale file?
Until the answer is written into the file, the money is not secure.
When a Late Request May Still Work
A late request may still have a chance if the file has not closed, the approval was just issued, and the servicer still has authority to review the payment.
It may be worth asking if the seller still occupies the property, the closing deadline has not passed, the lender's required net is protected, and the settlement statement can still be corrected before closing.
The request should be specific and documented:
Is the seller eligible for relocation or move-out assistance on this approved short sale, and if so, can the approval letter and settlement statement be updated before closing?
That answer needs to come from the lender, servicer, or authorized short sale contact. A verbal guess from an agent, buyer, closer, or previous file is not enough.
If the servicer agrees, the file may need an updated approval letter, written addendum, or clear closing instruction. The settlement statement should then reflect the payment exactly as allowed.
When It Is Probably Too Late
It may be too late if the file already closed, the approval letter prohibits seller funds, the seller has already moved out too early, the final settlement statement is locked, or the lender already confirmed no incentive is available.
It may also be too late if adding the payment would reduce the lender's approved net proceeds or conflict with investor guidelines.
One common mistake is assuming the seller can receive money outside closing. That can create serious problems. If the lender requires the payment to be disclosed, the payment should be shown correctly in the approved closing documents.
Another mistake is assuming a buyer, agent, or third party can simply pay the seller separately to solve the problem. That may violate approval terms, settlement rules, or lender requirements. If money is connected to the transaction, it should be reviewed before closing.
What Agents Should Check Before Closing
Before telling a seller they can count on move-out money, check these items:
- Does the lender or servicer offer relocation or incentive money on this file?
- Is the seller still eligible based on occupancy and program rules?
- Is the amount written into the approval letter?
- Is the payment shown correctly on the settlement statement?
- Does the approval letter prohibit seller proceeds or side payments?
- Will the payment reduce the lender's required net?
- Is there written confirmation before closing?
If any of those answers are unclear, pause before making promises.
The seller may still be able to ask, but the request should be handled before everyone is sitting at the closing table.
What Sellers Should Not Assume
Sellers should not assume they qualify for move-out money just because they are in hardship, leaving the home, or cooperating with the short sale.
They should also not assume a payment is guaranteed because they read about short sale incentive programs online. Many older programs changed, ended, or depend on very specific file rules.
The approval letter, settlement statement, and current lender instructions matter more than general advice.
If a seller needs the funds to move, that issue should be raised early. Waiting until after approval can still be possible in some files, but it gives the negotiator less room to solve the problem.
The Practical Rule
Move-out money is not real until it is approved in writing and matches the closing documents.
A seller can ask after approval, but the better strategy is to raise the issue before the lender issues final terms. That gives the short sale negotiator time to document eligibility, request the incentive, and make sure the approval letter does not create a closing-day surprise.
If the approval letter is already in hand, review it carefully before closing. The answer may still be yes, but it needs to be confirmed before the seller builds a moving plan around money that may not arrive.
If you are already close to closing and the approval terms are unclear, start the short sale process review before the deadline gets tighter.
FAQ
Can you ask for short sale relocation money after approval?
Sometimes, but it is harder after final approval terms are issued. The lender or servicer must confirm eligibility, and any approved payment should be reflected in the approval letter and settlement statement.
Who decides whether short sale move-out money is allowed?
The lender, servicer, investor, or program guidelines control the answer. The agent or seller cannot assume the payment is allowed unless it is confirmed in writing.
Does move-out money have to appear on the approval letter?
In most practical closing situations, yes. If the seller will receive funds connected to the short sale, the payment should be approved and disclosed correctly before closing.
Short Sale Approval Letter: 7 Clauses That Can Delay Closing
Why Approval Does Not Always Mean Clear to Close
Short sale approval is a major step, but it is not the finish line.
The lender or servicer may approve the short sale only under specific conditions. The letter may approve a certain buyer, price, net amount to the investor, closing date, seller contribution, junior lien payoff, commission, closing costs, and document package.
If the closing team misses one condition, the deal can stall even after everyone celebrates the approval.
That is why the approval letter should be reviewed like a closing checklist, not like a congratulatory email.
The CFPB explains that a short sale requires servicer approval and a complete loss-mitigation application. Fannie Mae and Freddie Mac also describe short sales as foreclosure alternatives that depend on lender approval. In practical terms, that approval arrives with rules. The rules are what can delay closing.
1. The Closing Deadline
The first clause to check is the expiration date.
Many short sale approval letters approve the sale only if it closes by a specific date. That date may be tighter than the buyer, lender, title company, or seller expected.
Agents should confirm:
- What is the exact closing deadline?
- Does the letter require funding and recording by that date, or only signing?
- Does the buyer's lender have enough time?
- Does title have all payoffs?
- Are there HOA, tax, lien, probate, divorce, or estate issues that could slow closing?
- Is an extension possible, and how must it be requested?
If the closing date is already unrealistic, the file needs immediate attention. Waiting until the day before expiration is how approvals turn into emergency extension requests.
This is also why the short sale approval letter closing window matters. The approval can be real and still expire before the deal is ready.
2. The Approved Buyer and Sale Price
Some approval letters are tied to the exact buyer and exact sale price in the submitted contract.
That sounds obvious, but problems start when something changes.
The buyer may request a price reduction after inspection. The buyer may switch financing. The buyer may ask for a credit. The contract may need an amendment. The seller or agent may think a small change is harmless.
The lender may not see it that way.
Before changing anything, check whether the approval letter says the sale is approved only for:
- A named buyer.
- A specific purchase price.
- A specific net amount to the lender or investor.
- A specific contract date or addendum package.
- A specific closing structure.
If the buyer, price, or terms change, the short sale negotiator may need to resubmit the change for approval. Do not assume title can fix it at closing.
3. Net Proceeds to the Lender
The approval letter may care less about the gross sale price and more about the net proceeds.
Net proceeds are what the lender expects to receive after approved costs are deducted. If the final settlement statement reduces the net below the approved amount, closing can stop.
This can happen when:
- Property taxes are higher than expected.
- HOA dues or collection fees appear late.
- Title fees change.
- A buyer credit is added.
- Repair credits are negotiated.
- Commission or transaction fees do not match the approval.
- A junior lien payoff is higher than expected.
The closing team should compare the approval letter to the settlement statement line by line. If the letter approves a minimum net, the final numbers need to match.
A short sale processor should catch this early, not after documents are out for signing.
4. Allowed Closing Costs and Credits
Short sale lenders do not automatically approve every closing cost.
The approval letter may limit which costs can be paid from sale proceeds. It may restrict buyer credits, home warranties, repair credits, seller concessions, unpaid utilities, HOA fees, transfer costs, recording fees, or extra transaction charges.
That matters because regular real estate habits can create short sale problems.
In a normal sale, the parties may negotiate credits and small changes near closing. In a short sale, those changes may affect the lender's approved net or violate the approval terms.
Agents should ask:
- Are buyer closing-cost credits allowed?
- Are repairs or repair credits allowed?
- Are HOA and title fees approved?
- Are commissions and processing fees listed correctly?
- Are any costs capped?
- Does the approval require a revised settlement statement before closing?
If the letter does not clearly allow a cost, do not assume it will pass.
5. Seller Contribution or Cash-at-Closing Terms
Some short sale approvals require a seller contribution.
That contribution might be a cash payment at closing, a promissory note, or another investor-required condition. It may also say the seller cannot receive proceeds from the sale except for specifically approved relocation assistance.
This is one of the most important sections for the seller to understand.
Agents should never gloss over seller contribution language. The seller needs to know:
- Whether money is due at closing.
- Whether a promissory note is required.
- Whether the amount is final.
- Whether relocation assistance is allowed.
- Whether any seller credit, reimbursement, or side payment is prohibited.
If the seller does not understand this section, closing can turn into a trust problem. Everyone thought the short sale was approved, but the seller discovers a cash requirement too late.
6. Deficiency, Release, and Debt Language
The approval letter may address what happens to the remaining unpaid mortgage balance after closing.
This is where sellers need careful guidance.
Some letters say the debt is satisfied or the lien is released. Some reserve rights. Some include deficiency language. Some are unclear. The exact meaning can depend on the loan, investor, state law, bankruptcy status, settlement terms, and other facts.
Agents should not give legal advice about deficiency exposure.
What agents can do is make sure the seller reads the language and gets help if needed. If the approval letter does not clearly answer the seller's question, the seller should speak with an attorney or qualified advisor before closing.
This section is too important to treat casually.
7. Junior Liens, HOA, Taxes, and Title Conditions
The first mortgage approval letter does not automatically solve every other problem on title.
A short sale can still be delayed by:
- Second mortgages.
- HELOCs.
- HOA liens.
- HOA collection fees.
- Property taxes.
- IRS or state tax liens.
- Judgments.
- Code liens.
- Probate or estate issues.
- Divorce or missing-signature problems.
The approval letter may allow a specific payment to a junior lienholder or HOA. If the actual payoff is higher, the deal may need new approval. If a lien is missing from the settlement statement, title may not insure or close.
This is why approval-letter review should happen with title, not separately from title.
The short sale approval letter, title commitment, payoff demands, and settlement statement all need to tell the same story.
The Settlement Statement Must Match the Letter
The safest approval-letter review is simple: compare the final settlement statement against every material approval term.
Look for mismatches in:
- Buyer name.
- Sale price.
- Closing deadline.
- Net proceeds.
- Seller contribution.
- Commission.
- Short sale processing fee.
- Buyer credits.
- HOA payoff.
- Junior lien payoff.
- Tax payoff.
- Relocation assistance.
- Closing costs.
If something does not match, resolve it before closing. Do not hope the lender misses it.
In a short sale, a mismatch can trigger a delay, denial, re-review, or funding problem.
When to Ask for Help
Agents do not need to handle every approval-letter issue alone.
If the letter is confusing, the closing date is tight, the lender has gone quiet, title finds a new lien, or the buyer needs changed terms, get short sale help quickly.
An experienced short sale specialist can help compare the approval letter to the contract and settlement statement, identify what needs lender review, and keep the file moving before the deadline expires.
The key is timing.
Approval-letter problems are easier to fix before everyone is sitting at the closing table.
Bottom Line
A short sale approval letter is progress, but it is not permission to ignore the details.
Before closing, check the deadline, buyer, price, net proceeds, costs, seller contribution, deficiency language, junior liens, HOA issues, tax payoffs, relocation terms, and settlement statement.
If the letter and closing documents do not match, fix the mismatch before the file loses time.
That is how agents protect the seller, keep the buyer informed, and avoid turning an approved short sale into a delayed closing.
VA Loan Short Sale: What Sellers Should Check First
Why VA Loan Short Sales Need a Different First Check
A VA-backed loan short sale is not just a regular short sale with a different label.
The homeowner may be a veteran, service member, surviving spouse, or other eligible borrower who used a VA home loan benefit. The servicer may be reviewing foreclosure-avoidance options. VA rules and servicer requirements may affect how the file is handled. And if a short sale or foreclosure creates a loss on the VA-backed loan, there may be questions about future home loan benefit use.
That is why the first step should not be panic-listing the home or waiting for the servicer to ask for documents one at a time.
The first step is control.
The seller needs to know what options are still open, what the servicer needs, what deadlines are active, and whether a short sale is realistic before the foreclosure process gets tighter.
Step 1: Call the Servicer Before the File Drifts
VA tells borrowers who are having trouble making mortgage payments to contact the loan servicer right away. That matters because the servicer is usually the first place where repayment options, forbearance, modification, partial claim, short sale, deed in lieu, or other foreclosure-avoidance options are discussed.
Do not wait until the file is already at the edge of foreclosure.
Ask the servicer:
- Is the loan in active foreclosure?
- Is there a sale date, referral date, or review deadline?
- Are home-retention options still available?
- Is a short sale review available if keeping the home is not realistic?
- What documents are required?
- Where should documents be submitted?
- Who can the seller authorize to speak with the servicer?
- How does the servicer handle VA-backed short sale or compromise sale review?
The point is not to choose the short sale path blindly. The point is to find out whether the seller can still keep the home, and if not, whether the short sale path can be reviewed in time.
Step 2: Contact VA if the Seller Needs Help Understanding Options
VA says borrowers can contact a VA loan technician at 877-827-3702 for help with VA-backed home loan questions and foreclosure-avoidance options.
That phone call can matter when the seller is confused, nervous about dealing with the servicer, or unsure what the servicer is telling them.
This does not replace legal advice, tax advice, or the servicer's actual approval process. It simply gives the veteran homeowner another official contact point before the file loses time.
For sellers, that can reduce guesswork.
For agents, it can also help keep the conversation grounded. The agent should not promise that a VA short sale will be approved. The agent can help the seller gather facts, document the file, and get the right parties involved early.
Step 3: Decide Whether Keeping the Home Is Still Realistic
A short sale means the seller is leaving the home.
That is why this decision has to be honest.
If the seller may still be able to keep the property through a repayment plan, modification, forbearance, partial claim, or another approved option, that conversation should happen quickly with the servicer and appropriate advisers.
If keeping the home is not realistic, then the question changes.
Now the seller needs to compare a controlled sale against a foreclosure path that may keep moving on its own.
That is where a VA loan short sale can become the better conversation. But only if the file is complete, the timeline works, and the servicer has enough information to review the request.
Step 4: Gather the Seller Documents Before the Servicer Asks Twice
Many short sale files stall because the first submission is incomplete.
For a VA-backed loan, the servicer may still have its own package requirements, but sellers and agents should expect to gather the basics early:
- Signed third-party authorization.
- Current mortgage statement.
- Hardship explanation.
- Income documentation.
- Bank statements.
- Tax or benefit documentation when requested.
- Listing agreement.
- Purchase contract if there is an offer.
- Buyer proof of funds or loan pre-approval.
- Estimated settlement statement.
- Payoff information.
- HOA, tax, judgment, or junior lien details.
- Property condition notes, repair issues, or comparable sales support.
The servicer may ask for more, but this gives the short sale processor or negotiator a cleaner starting point.
Missing documents create delay. Delay creates buyer fatigue. Buyer fatigue creates fallout. And when foreclosure pressure is active, the file may not have room for preventable mistakes.
Step 5: Check Title, Liens, HOA, and Signatures Early
The first lender is not always the only problem.
A VA loan short sale can still run into issues with title, HOA balances, second mortgages, judgments, tax liens, municipal liens, probate, divorce, estate authority, or missing signatures.
Those issues should be checked before everyone assumes the short sale can close.
Ask early:
- Who is on title?
- Who must sign?
- Are there junior liens?
- Is there an HOA balance or collection account?
- Are taxes current?
- Are there judgments or old unreleased mortgages?
- Is there a probate, divorce, estate, or bankruptcy issue?
- Can the buyer close if approval arrives with a short deadline?
This is where short sale processing is more than paperwork upload. Someone has to coordinate lender review, title issues, buyer timing, approval terms, and closing conditions at the same time.
Step 6: Understand the Future VA Loan Benefit Question
VA's public foreclosure-avoidance guidance says a short sale may result in a loss or reduction in the borrower's future home loan benefit.
That does not mean every seller will have the same outcome. It does mean the seller should ask before making assumptions.
The homeowner should ask the servicer and VA:
- Could this short sale affect future VA loan benefit use?
- Would VA pay a claim because of the short sale?
- What would restoration of entitlement require?
- Should the seller speak with a housing counselor, attorney, CPA, or other adviser before closing?
This is not a reason to avoid a short sale automatically. It is a reason to understand the tradeoff.
Foreclosure can also create serious consequences. The point is to compare the options with facts, not fear.
Step 7: Get Short Sale Help Before the Timeline Gets Tight
Veteran homeowners often wait too long because they are trying to do the right thing. They call the servicer, look for options, and hope the situation improves.
That is understandable.
But a short sale file needs time. The seller documents have to be gathered. The buyer offer has to be reviewed. The estimated settlement statement has to be accurate. Title and lien problems have to be found. The servicer has to review the package. The buyer has to stay committed. Closing has to happen inside the approval window.
If the file is already close to foreclosure, the short sale team may also need to ask for extra review time or support a postponement request.
That is much harder when the file is incomplete.
A short sale specialist or short sale negotiator can help organize the package, communicate with the servicer, track document requests, review approval terms, and keep the file moving.
The goal is simple: avoid losing a viable option because no one controlled the file early enough.
Final Takeaway
If you have a VA-backed loan and are considering a short sale, do not start with assumptions.
Start with facts.
Call the servicer. Contact VA if you need help understanding options. Confirm the deadline. Decide whether keeping the home is still realistic. Gather a complete short sale package. Check title, liens, HOA, and signatures. Ask about future VA loan benefit impact before closing.
Then get the file moving.
A VA loan short sale can be a useful alternative to foreclosure, but only when the seller, agent, and short sale team understand what must be checked first.
Short Sale or Foreclosure? 7-Day Checklist
Foreclosure deadline close? Use this 7-day checklist to compare short sale vs foreclosure risks before options narrow.
Why This Decision Feels So Urgent
Most homeowners do not calmly compare short sale vs foreclosure at a kitchen table with unlimited time.
They compare it when letters are arriving, calls are awkward, payments are behind, an auction date may be approaching, and everyone is using phrases that sound final.
That pressure makes it easy to freeze.
But freezing is still a choice. If no one calls the servicer, no one checks the deadline, no one prepares documents, and no one tests whether a short sale is still possible, the foreclosure path keeps moving.
The goal of this checklist is not to tell every homeowner that a short sale is always better. It is not. The right answer depends on the loan, the hardship, the timeline, the property value, the state process, tax questions, credit concerns, and whether the lender will approve the sale.
The goal is simpler: help you find out whether you still have a controllable option before the clock decides for you.
Day 1: Confirm the Real Foreclosure Deadline
The first question is not "Which option sounds better?"
The first question is "How much time is actually left?"
Find the latest notice, servicer letter, attorney letter, court filing, auction notice, sheriff sale notice, trustee sale notice, or online foreclosure status. The wording can vary by state, but the practical question is the same: is there a sale date, hearing date, deadline to respond, or date when the file moves to the next stage?
Do not rely only on memory. Do not rely only on an old notice. Do not rely only on what someone said over the phone two months ago.
Foreclosure timelines are state-specific, and missed dates can change the options fast. If you are unsure what a notice means, speak with a local attorney or HUD-approved housing counselor. HUD points homeowners toward housing counselors who can help explain options, organize finances, and communicate with lenders.
For short sale purposes, the deadline matters because the file needs enough time for pricing, an offer, seller documents, lender review, valuation, approval, title, and closing.
If the sale date is very close, the short sale team may also need an escalation or postponement request. That is where the foreclosure auction postponement evidence package can matter.
Day 2: Call the Servicer and Ask What Is Still Open
Once you know the deadline, call the mortgage servicer.
Ask direct questions:
- Is the loan in active foreclosure?
- Is there a sale date or referral date?
- Are loss-mitigation options still open?
- Has a short sale review been opened?
- What documents are required for short sale review?
- Is there a specific portal, fax, email, or department?
- Will the servicer review a complete short sale package if there is an accepted offer?
- What would be needed to request a postponement if a buyer is under contract?
The CFPB describes a short sale as an alternative to foreclosure, but it also notes that because it is a sale, the homeowner will leave the home. That is the practical fork in the road: are you trying to keep the home, or are you trying to leave with more control than foreclosure usually gives?
That difference matters.
If the servicer says you may still qualify for a workout that keeps the home, that is one path. If keeping the home is not realistic, then the short sale question becomes more urgent.
Day 3: Decide Whether Keeping the Home Is Realistic
This is the hardest part because it is personal.
A short sale means selling the property for less than the full mortgage balance, with the lender or servicer agreeing to accept the transaction. It is not a way to keep the home.
Foreclosure is also not a plan to keep the home. It is what happens when the file continues through the legal or trustee process and no other resolution stops it.
So before comparing the two, ask whether keeping the home is actually possible.
Can the missed payments be cured? Is a repayment plan realistic? Would a loan modification solve the problem long term, or only delay it for a few months? Is there income to support the payment? Are taxes, insurance, HOA dues, repairs, or other debts still growing?
If the answer is "we can keep it if the servicer approves the right option," then focus on that loss-mitigation path quickly.
If the honest answer is "we cannot keep it," then the question changes. Now you are comparing a controlled sale against letting the foreclosure process finish.
That is when short sale assistance can become the better conversation.
Day 4: Test Whether a Short Sale Can Actually Work
A short sale is not approved just because the homeowner wants one.
The lender usually needs to see the hardship, the market value, the buyer offer, the estimated closing numbers, the payoff, and the reason the sale makes more sense than foreclosure.
That means a short sale file needs a real package. It may include:
- Authorization to speak with the servicer.
- Hardship explanation.
- Financial documents.
- Listing agreement.
- Purchase contract.
- Buyer proof of funds or pre-approval.
- Estimated settlement statement.
- Payoff information.
- HOA, tax, judgment, or junior lien information.
- Market support showing why the offer makes sense.
Fannie Mae's public short sale fact sheet describes a short sale as selling the home for less than the mortgage balance, with the borrower selling at market value and the investor accepting the proceeds to satisfy the debt, depending on the situation. That basic structure is why the numbers matter so much.
If the price is unsupported, the buyer is weak, the documents are missing, or the net sheet is wrong, the file may not move fast enough.
This is where an experienced short sale negotiator or short sale specialist can help. The job is not just uploading documents. The job is building a file the lender can actually review before time runs out.
Day 5: Check Title, Liens, HOA, and Signatures
Many homeowners think the lender is the only obstacle.
That is not always true.
A short sale can be delayed by title issues, HOA balances, second mortgages, judgments, tax liens, probate questions, divorce signatures, unreleased old mortgages, code liens, or missing owner authority.
Those problems matter more when foreclosure is close because they can stop closing even after the first lender says yes.
This is why foreclosure pressure makes short sale files harder. The file is not only racing the lender review. It is also racing every hidden issue that regular sales sometimes solve slowly.
Before choosing a short sale path, ask:
- Who is on title?
- Who must sign?
- Are there junior liens?
- Is there an HOA payoff or collection account?
- Are taxes current?
- Has title been checked?
- Is there a bankruptcy, probate, divorce, or estate issue?
- Can the buyer close inside the approval window?
If those questions are ignored, the short sale may look possible on paper but fail at the closing table.
Day 6: Protect the Buyer and Closing Window
Short sales often fail because the buyer runs out of patience.
That is especially true when the homeowner is comparing short sale vs foreclosure late in the process. The buyer may be interested, but they need confidence that someone is driving the file.
Before relying on a buyer, confirm:
- The buyer understands this is a short sale.
- The buyer can wait for lender review.
- The buyer's financing or cash proof is current.
- The contract gives enough time for approval.
- The buyer will not demand repairs or credits that break the lender's numbers.
- The closing date is realistic if approval arrives.
If a foreclosure date is already scheduled, the buyer package may also become part of the evidence used to request more time. A servicer is more likely to take a short sale seriously when the file looks real, organized, and closeable.
That does not guarantee a postponement. But a clean package is stronger than a vague promise that "we have a buyer."
Day 7: Choose the Path and Stop Drifting
By the seventh day, the goal is to know where you stand.
You should know the deadline. You should know whether the servicer will review a short sale. You should know whether keeping the home is realistic. You should know whether there is a buyer path, document path, and title path.
If the answer is yes, move fast.
Start the short sale process, gather the file, and make sure the servicer gets a clean package. If the foreclosure date is close, the short sale team should also know what evidence is needed for escalation.
If the answer is no, do not drift silently into foreclosure without understanding the consequences. Talk to a housing counselor, attorney, tax professional, or other qualified advisor as needed.
Some situations need legal guidance. Some need credit or tax guidance. Some need immediate servicer communication. Some need all of the above.
The worst option is pretending there is still plenty of time when the notices say otherwise.
When a Short Sale May Be the Better Path
A short sale may be worth pursuing when the homeowner cannot keep the home, the property is worth less than the payoff, there is enough time to submit a real package, a buyer can be found or is already under contract, and the lender is willing to review the file.
It may also be useful when the homeowner wants a more controlled exit than foreclosure, especially if there are relocation, deficiency, timing, or future housing concerns to discuss.
But short sale approval is not automatic. The file needs lender acceptance, investor approval where applicable, and closing terms that everyone can meet.
That is why short sale help matters most before the file becomes chaotic.
When Foreclosure May Still Be on the Table
Foreclosure may still happen if the deadline is too close, the servicer will not pause review, the homeowner cannot provide documents, the title issues cannot be solved, the buyer cannot close, or the numbers do not support approval.
That does not mean the homeowner should give up without asking questions.
It means the decision has to be based on reality, not hope.
If the file is already deep in foreclosure, ask for qualified help immediately. A short sale specialist can help determine whether a short sale package is still realistic. A local attorney can explain state-specific rights and deadlines. A HUD-approved housing counselor can help review options and communicate with the servicer.
Different roles solve different parts of the problem.
What Agents Should Not Promise
Agents should be careful with this topic.
Do not promise that a short sale will stop foreclosure automatically.
Do not promise that the lender will approve the sale.
Do not promise that credit impact, deficiency treatment, tax consequences, or future loan eligibility will be the same for every seller.
Do not tell the seller to ignore notices because a buyer is interested.
The safer message is: "We need to check the deadline, the servicer's process, the file requirements, the title issues, and whether this can still close in time."
That is honest. It also gives the seller a path.
The Bottom Line
Short sale vs foreclosure is not just a comparison. When time is short, it is a sequence of checks.
What is the deadline?
Will the servicer review?
Can the homeowner keep the home?
Can a short sale package be submitted fast enough?
Can title close?
Can the buyer wait?
Who is actually coordinating the file?
If those answers point toward a short sale, act quickly. If they do not, get the right advice before the foreclosure process finishes without a plan.
A short sale can give a homeowner more control than foreclosure, but only when someone moves the file before the deadline takes over.
If you are already comparing short sale vs foreclosure, the clock is part of the decision. Do not wait for it to make the decision for you.
Short Sale Processing Companies: What Agents Should Check First
A Processor Should Do More Than Collect Documents
A short sale processing company can make an agent's life easier.
Or it can make the agent look unresponsive, disorganized, and completely out of control.
That is the part many listing agents do not see soon enough. By the time a short sale is already delayed, the buyer is frustrated, the seller is nervous, and the lender is asking for the same documents again, it is hard to tell whether the problem is the bank, the file, or the person managing the process.
That is why agents should vet short sale processing help before the file is handed off.
At the simplest level, a short sale processor helps gather forms, financials, hardship documents, authorizations, payoff information, and lender requirements.
But that is only the starting point.
A strong short sale processor should understand how the whole file moves: seller documents, buyer offer, estimated settlement statement, title issues, servicer review, investor review, valuation, counters, approval terms, and closing conditions.
If the processor only asks for documents but does not know how those documents affect approval, the agent may still be exposed.
The real value is not paperwork collection. The real value is file control.
Ask Who Talks to the Lender
This is the first question agents should ask.
Who actually communicates with the lender or servicer?
Some processing companies collect documents and leave the agent to chase updates. Others handle lender calls, portal uploads, follow-up notes, escalation requests, and review timelines.
That difference matters.
A short sale can stall because nobody noticed the lender requested an updated bank statement. It can stall because the valuation was ordered but never followed up on. It can stall because the file was in review for two weeks with no real movement.
A good short sale negotiator or processor should know when to wait, when to follow up, and when the file needs escalation.
Check Their Deadline System
Short sales are deadline-heavy. Documents expire. Payoff statements change. Buyer timelines move. Foreclosure dates can tighten. Approval letters may require closing by a specific date.
If the processing company does not have a clear deadline system, the agent is taking a risk.
Ask how they track:
- Missing seller documents.
- Lender review dates.
- Valuation orders.
- Buyer financing deadlines.
- Foreclosure or auction dates.
- Approval-letter expiration dates.
- Title and HOA payoff issues.
This is where a true short sale coordinator can protect the file. Coordination is not glamorous, but it keeps small issues from becoming closing-killers.
Ask What Happens When the Bank Goes Quiet
Every experienced short sale agent knows the moment: the file is submitted, the lender confirms receipt, and then everything goes silent.
That silence is not always harmless.
Sometimes the file is sitting in a queue. Sometimes a document is missing. Sometimes a task is open in the servicer portal. Sometimes the assigned negotiator changed. Sometimes the lender is waiting for an internal review nobody explained.
This is why agents should ask a processing company how they handle stalled files.
Do they have a follow-up cadence? Do they document calls? Do they know how to escalate? Do they know why banks delay short sale approval, or do they simply tell everyone to be patient?
Patience is not a strategy. It is what you do while a strategy is working.
Review Approval Letters Carefully
A short sale approval letter is not just a green light. It is a set of conditions.
It may control the approved payoff, closing deadline, commission, seller contribution, buyer contribution, relocation assistance, deficiency language, junior lien treatment, and fees allowed on the settlement statement.
A processor who does not review approval terms carefully can miss problems that show up at closing.
That is where deals get painful. Everyone thinks the short sale is approved, but title cannot close under the terms. Or the buyer needs more time. Or the settlement statement includes something the approval letter does not allow.
A good processing company should flag those issues early and help the agent understand what needs to be corrected before the closing window gets tight.
Watch for Red Flags
Agents should be careful if a short sale processing company:
- Promises approval before reviewing the file.
- Cannot explain who communicates with the servicer.
- Has no clear update process.
- Does not review title, HOA, or payoff issues.
- Treats every lender the same.
- Gives vague answers about escalations.
- Does not understand approval-letter conditions.
- Disappears after submission.
The wrong processor does not just slow the file. The wrong processor can damage the agent's relationship with the seller, buyer's agent, title company, and lender.
What a Good Processing Partner Looks Like
A good partner gives the agent visibility.
They explain what has been submitted, what is still missing, what the lender is reviewing, what the next deadline is, and where the file may get stuck.
They do not leave the agent guessing.
They also understand that every short sale has a human side. The seller is usually under financial pressure. The buyer may be losing patience. The agent's reputation is on the line. The lender wants a complete, defensible file.
That is why professional short sale help is not just administrative support. It is risk management.
Final Takeaway
Short sale processing companies are not all the same.
Some help agents keep control. Some only move documents from one place to another.
Before choosing a processor, ask how they communicate, how they track deadlines, how they handle lender silence, how they review approval terms, and how they protect the closing.
Because in a short sale, the question is not just who can upload the file.
The question is who can keep the file alive until it closes.
Texas Short Sale Title Problems Before Auction: What Can Still Stop Closing?
Why Title Problems Matter More in a Texas Short Sale
Texas foreclosure timelines can move fast. Texas Property Code Section 51.002 requires foreclosure sale notice at least 21 days before the sale, and Texas foreclosure sales are generally tied to the first Tuesday sale process. That means a short sale file near auction does not have much room for late surprises.
In a normal sale, a title issue may be annoying.
In a Texas short sale near foreclosure, it can be fatal.
The seller does not just need a buyer. The seller needs a clean path to closing before the auction clock runs out. If title is not clear, the lender may not approve, the buyer may not wait, the title company may not insure, or the sale date may arrive before the file is ready.
The Title Issues That Usually Slow Things Down
The title commitment can reveal problems that must be cleared before closing. The Texas Department of Insurance explains that title agents review public records for issues such as deeds, mortgages, judgments, tax records, liens, and encumbrances.
For short sales, the trouble often shows up in a few places:
- A second mortgage or home equity lien.
- HOA dues, assessments, or collection fees.
- Property tax balances.
- Judgment liens.
- Mechanic's liens or contractor claims.
- Old paid-off mortgages that were never properly released.
- Divorce, probate, or heirship questions.
- A seller who is not the only person with authority to sign.
- A legal description or name mismatch.
- Closing costs or payoff numbers that do not match the short sale approval.
None of these automatically means the short sale is dead. But each one needs time, documents, and the right party to solve it.
Why We Have Approval Is Not Enough
A short sale approval letter is important, but it is not the same thing as a cleared closing.
The approval letter may say the lender accepts a certain payoff by a certain deadline. The title company still has to confirm whether the transaction can close cleanly. If the title company finds a lien, missing signature, or payoff problem, the approval letter does not magically fix it.
That is where agents get caught.
They celebrate approval, then discover the HOA payoff is wrong. Or the second lien has not approved. Or the seller's ex-spouse must sign. Or the title company needs a release that no one requested early enough.
By then, the foreclosure sale date may be too close.
What Agents Should Ask the Title Company Early
Agents do not need to solve every title issue themselves. But they should know what to ask.
Before the file gets close to auction, ask:
- Has title been opened?
- Are all liens and payoffs identified?
- Are there any Schedule C requirements that must be cleared?
- Are there HOA, tax, judgment, mechanic's lien, or child support lien issues?
- Does anyone besides the seller need to sign?
- Is there a probate, heirship, divorce, trust, or power-of-attorney concern?
- Does the title company need anything from the short sale lender before closing?
- Do the approval letter numbers match the settlement statement?
- Can the file realistically close before the foreclosure date?
The answer you do not want is: We will find out after approval.
How a Short Sale Processor Helps
A good short sale processor or short sale negotiator should keep title and lender approval moving together.
That means the processor should not only upload the contract and hardship package. They should also watch for title problems that can affect approval, net proceeds, payoff timing, and closing deadlines.
For example, if the title company finds an HOA balance, the negotiator may need to get that amount approved on the net sheet. If there is a junior lien, that lienholder may need a separate short payoff. If the seller's authority is unclear, the file may need updated documents before the servicer will speak with the right person.
The processor's job is to keep the file from reaching the finish line with a problem that should have been caught at the starting line.
The Bottom Line
A Texas short sale can still work before auction, but the file has to be clean enough to close.
Title problems do not always kill the deal. Waiting too long to find them often does.
If the foreclosure date is already posted, agents should treat title review, lien payoff, approval-letter terms, and seller authority as urgent closing issues, not back-office paperwork. The faster those problems are identified, the better chance the short sale has of closing before the auction date.
If a Texas foreclosure sale date is close and title problems are already showing up, Crisp Short Sales can help agents organize the file, coordinate the short sale processor work, and keep lender review moving before the auction clock takes over.
Start the short sale process here: https://www.crispshortsales.com/start-short-sale
Reverse Mortgage Short Sale After Death: Who Can Sign?
Why Reverse Mortgage Short Sales Get Stuck After Death
A reverse mortgage short sale is different from a normal distressed sale.
In a regular short sale, the seller is usually alive, available, and able to sign documents. The agent can speak with the seller, the seller can authorize the short sale processor, and the lender can review the hardship, offer, payoff, and settlement numbers.
After a reverse mortgage borrower dies, the file can be less clear.
Who owns the right to act? Who can speak to the servicer? Who can list the home? Who can accept an offer? Who can sign the closing documents? Who can authorize a short sale negotiator? Who receives servicer notices? Who is dealing with title?
Those questions are not side issues. They are the file.
If the family waits too long to answer them, the home may sit while mail piles up, the servicer sends notices, deadlines pass, and the property quietly moves closer to foreclosure.
The First Question Is Not Price
When heirs call about a reverse mortgage short sale, the first instinct is usually to ask what the home is worth.
That matters, but it is not always the first problem.
The first problem is authority.
The servicer may not be able to discuss loan details with every family member who calls. The title company may not be able to close with someone who does not have legal authority. A buyer may not be able to rely on a contract signed by the wrong person. An agent may not be able to list the property safely without confirming who has the right to sign.
So before the file becomes a pricing conversation, it has to become an authority conversation.
Ask:
- Who was the reverse mortgage borrower?
- Is there a co-borrower or eligible non-borrowing spouse?
- Has the servicer been notified?
- Who is receiving notices?
- Is there an executor, personal representative, trustee, attorney, or court-appointed party?
- What documents does the servicer need before discussing payoff or short sale options?
- What does title need before closing can happen?
This is where a lot of families lose time. Everyone assumes someone else has the authority until the servicer, title company, or buyer asks for proof.
What Heirs May Need To Gather
Every file is different, and estate requirements can vary. But reverse mortgage short sale files after death often need a clean document path.
That may include:
- Death certificate or proof the borrower has passed.
- Servicer contact information and loan number.
- Any due-and-payable notice or servicer correspondence.
- Estate documents, probate documents, trust documents, letters testamentary, letters of administration, or other authority documents if applicable.
- Photo ID and contact information for authorized parties.
- Property address, occupancy status, keys, access details, and condition information.
- Current insurance, tax, HOA, utility, and municipal information.
- Listing agreement, offer, buyer proof of funds or pre-approval, and estimated settlement statement when ready.
- Title search or known lien information.
The goal is not to bury the servicer in paper. The goal is to prove that the right people are involved and that the property can be reviewed, marketed, contracted, and closed.
Why the 95 Percent Rule Matters
Many reverse mortgages are Home Equity Conversion Mortgages, often called HECMs. The Consumer Financial Protection Bureau explains that after a reverse mortgage borrower dies, heirs may be able to keep or sell the home. If the loan balance is more than the home value, heirs may be able to sell or repay based on at least 95 percent of the home's appraised value.
That detail matters in a short sale.
If the reverse mortgage balance is higher than the value of the home, the family may think the home is impossible to sell. But a reverse mortgage short sale may still be possible if the transaction is handled under the servicer's rules and the approval terms support it.
That does not mean every low offer works. It also does not mean the family can ignore servicer procedures.
The value still has to be supported. The buyer still has to be real. The file still has to be submitted correctly. The servicer still has to review the sale. And the person signing still has to have authority.
What Agents Should Not Assume
Agents should be careful with reverse mortgage files after death because the normal listing routine can create problems.
Do not assume:
- The adult child can automatically sign for the estate.
- The person with the keys can authorize the short sale.
- The first family member who calls the agent is the decision-maker.
- The servicer will discuss the loan without acceptable authorization.
- The listing can close before title confirms authority.
- A buyer will wait while probate or title issues are sorted out.
- A reverse mortgage short sale works exactly like a conventional short sale.
These assumptions can waste weeks.
The better approach is to slow down for one clean setup, then move quickly once authority is clear.
Why Servicer Communication Has To Start Early
The servicer needs to know what is happening with the property.
Has the borrower died? Is anyone living there? Is there an eligible non-borrowing spouse? Is the family selling the home? Is there an estate representative? Is the property secure? Is there insurance? Is the home listed? Is there an offer coming?
If nobody communicates, the servicer may treat the file as unresolved and continue the default or foreclosure process.
That does not mean one phone call fixes everything. It means the family or authorized representative should open a clear line of communication as early as possible.
CFPB guidance says that, for HECM reverse mortgages, heirs who receive a due-and-payable notice generally have 30 days to buy, sell, or turn over the home to satisfy the debt. That is not much time if the family is still trying to figure out who can sign documents or speak with the servicer.
For agents and short sale processors, this is where organized follow-up matters. The file should show that the property is being handled, the right people are involved, and a realistic sale path is being created.
What If Probate Is Still Open?
Probate can affect timing, signing authority, and title clearance.
If probate is open or has not started, the agent should not guess. The family may need local legal advice, estate guidance, or title-company input before listing or closing. A short sale processor can help with lender and servicer coordination, but legal authority to sell the property has to be handled correctly.
This is why the file should not wait until a buyer is ready to close.
If authority is unclear on day one, it may still be unclear on closing day unless someone fixes it.
And in a reverse mortgage file, closing day may not be flexible.
What Happens If the File Moves Toward Foreclosure?
A reverse mortgage file can move toward foreclosure if the loan becomes due and payable and the situation is not resolved. Death, move-out, non-occupancy, unpaid property charges, or other default events can all create urgency depending on the loan and facts.
The family may still have options, but time matters.
A short sale may need:
- A complete listing and sale plan.
- Proof of authority.
- A supported purchase offer.
- Servicer communication.
- Appraisal or valuation handling.
- Title review.
- Closing timeline coordination.
- Foreclosure postponement communication when appropriate.
If those pieces are missing, the servicer may not have enough reason to pause or review the short sale path.
This is why the broader reverse mortgage short sale deadline guide is still important. The deadline problem is real. This article simply answers the earlier question: who can move the file before the deadline becomes the whole story?
How a Short Sale Processor Helps
A good short sale processor or short sale negotiator does not replace the estate attorney, title company, or legal authority. But they can help keep the lender side organized.
That means:
- Identifying the servicer.
- Confirming what authorization the servicer needs.
- Organizing the short sale package.
- Tracking due-and-payable or foreclosure communication.
- Coordinating valuation, offer, settlement statement, payoff, and title issues.
- Helping the agent avoid submitting a file that is incomplete from the start.
The value of the processor is focus.
Reverse mortgage short sales can feel emotional and scattered because family, grief, property access, title, estate documents, and foreclosure pressure are all mixed together. A clean short sale process keeps the lender-review pieces from getting lost.
What To Send Before the File Stalls
Before the short sale is submitted, agents and heirs should try to build a file that answers the servicer's next questions.
A strong early package may include:
- A clear note explaining the borrower status and sale goal.
- Authorized contact information.
- Estate or authority documents requested by the servicer.
- Property occupancy status.
- Listing information and access details.
- Condition photos and repair concerns.
- Offer and buyer proof when available.
- Estimated settlement statement.
- Title issues, taxes, HOA balances, or known liens.
- Expected closing timeline.
The file should make it easy for the servicer to understand who is acting, why the sale is needed, and whether the transaction has a realistic path to close.
The Bottom Line
A reverse mortgage short sale after death is not just a pricing problem. It is an authority problem, a timing problem, and a communication problem.
The family may still have options. The home may still be sellable. A short sale may still work if the reverse mortgage balance is higher than the property value.
But the file cannot move cleanly until the right person can speak, sign, and submit.
If you are helping heirs with a reverse mortgage property, do not wait until a buyer is ready or a foreclosure deadline is close. Confirm authority, contact the servicer, gather estate and title documents, and get the short sale path organized early.
If a reverse mortgage short sale is already creating deadline pressure, Crisp Short Sales can help agents and families organize the lender side before the file stalls. Start the short sale process here: https://www.crispshortsales.com/start-short-sale
BPO vs Appraisal in a Short Sale
Bank value too high? Compare BPO vs appraisal issues and see what evidence can support a cleaner short sale value challenge.
Why BPO vs Appraisal Matters in a Short Sale
In a normal sale, price is mostly a negotiation between buyer and seller.
In a short sale, the bank has a separate question: does this offer make more sense than foreclosure, resale risk, holding costs, investor rules, and the unpaid mortgage balance?
That is why the lender's value review matters so much. The buyer may offer market value. The seller may accept. The agents may agree the number is reasonable. But if the bank's BPO or appraisal comes back higher, the lender may counter, delay, or reject the short sale.
This is where agents get stuck. They hear "BPO" from one department, "appraisal" from another, and then a counteroffer that does not match the actual condition of the home.
The practical question is not just what a BPO or appraisal is. The real question is: why did the bank's value change, and what can be done before the file falls apart?
What a BPO Is Usually Trying to Do
A BPO, or broker price opinion, is usually prepared by a real estate broker or agent. In a short sale, it helps the lender estimate what the property may be worth in the current market.
The BPO may include comparable sales, active listings, property condition, photos, neighborhood notes, and an estimated value range. Some BPOs are interior. Some are exterior only. Some are rushed. Some are thorough.
That difference matters.
An exterior-only BPO may miss interior damage. A quick review may over-rely on renovated comps. A local market shift may not be fully reflected. A vacant or distressed property may look closer to normal on paper than it does in person.
That does not mean every BPO is bad. It means the BPO is only as useful as the data and condition context behind it.
What an Appraisal Adds
An appraisal is generally a more formal valuation performed by an appraiser. Appraisals are typically built around professional standards, market data, property characteristics, condition, comparable sales, and an appraiser's opinion of value.
In a short sale, an appraisal can carry a lot of weight because it may look more formal than a BPO. But that does not make it immune from problems.
The appraiser may still rely on comps that do not match the property. Repairs may be underestimated. Access may be limited. Market movement may change after the report. The report may not capture buyer risk, foreclosure pressure, title problems, or the practical cost of closing a distressed file.
So an appraisal can be stronger than a BPO in process, but it can still produce a number that does not match the short sale reality.
Why the Bank's Value Can Change
The bank's value can change for reasons that are reasonable, frustrating, or both.
Common reasons include:
- The first BPO was exterior only and a later review saw the interior.
- Property-condition photos revealed damage, deferred maintenance, or access issues.
- Repair estimates showed that the buyer's offer was not as low as it first looked.
- Newer comparable sales became available.
- The original comps were too renovated, too large, too new, or in a better location.
- The lender refreshed an older value before approval.
- A mortgage insurer, investor, or second-level review asked for another valuation.
- The buyer reduced the offer after inspection.
- The foreclosure timeline or listing history changed the risk profile.
Fannie Mae's short sale servicing guidance, for example, requires a property valuation for a short sale and says the valuation must be dated or refreshed within 90 calendar days of approval. That is a good reminder that value is not always a one-time event. In a live short sale, the lender may need the value to stay current before approval.
Why the Bank's Number May Be Too High
A high bank value does not always mean the lender is being unreasonable. Sometimes it means the lender did not get the full story.
The most common problem is bad comparison.
A renovated sale down the street may not compare well to a short sale property with old systems, moisture concerns, roof issues, damaged flooring, tenant wear, deferred maintenance, or a buyer who has to absorb risk. A larger home, better lot, finished basement, newer kitchen, or cleaner occupancy situation can all distort value if the reviewer does not adjust for those differences.
The second problem is missing condition evidence.
If the file only shows a contract and a payoff shortage, the lender may see a low offer. If the file also shows photos, inspection notes, repair estimates, and buyer feedback, the lender can see why the offer may be the best real recovery.
This is why the recent Crisp post on short sale BPO photos is such an important supporting piece. Photos do not replace valuation work, but they can explain the value story before the bank locks onto the wrong number.
What Agents Should Send When Value Is Wrong
Do not send a messy emotional argument that says the bank is wrong.
Send a clean value-dispute package.
A strong package usually includes:
- A short cover note explaining the issue and requested value review.
- Clear property-condition photos with labels or brief explanations.
- Repair estimates, inspection summary items, or contractor notes when available.
- Better comparable sales with a simple reason each comp fits.
- Reasons the bank's likely comps are weaker, renovated, larger, newer, or superior.
- Listing history, showing feedback, days on market, and price-reduction context.
- Buyer inspection objections or lender repair concerns.
- Any local market details that explain why buyers are not paying the higher value.
The goal is not to overwhelm the short sale negotiator. The goal is to make the file easy to understand and easy to escalate.
For a deeper supporting example, agents can also review what to do when the BPO comes in too high and the lender's counter is no longer aligned with the property.
What Not To Send
Agents should avoid sending a pile of random screenshots, unsupported opinions, or angry emails.
The lender needs evidence, not frustration.
Weak value disputes usually fail because they say:
- "The value is too high."
- "The buyer will walk."
- "The market is bad."
- "The house needs work."
Those points may all be true, but they are not enough by themselves.
A better dispute says:
"The lender's value appears to rely on renovated comps between $X and $Y. The subject property has roof damage, original systems, interior repair needs, and buyer inspection concerns. Attached are dated photos, repair estimates, and three more comparable sales that match the subject's condition more closely. Based on this evidence, the accepted offer is consistent with the real market."
That is a much stronger short sale value argument.
How a Short Sale Processor Helps
A good short sale processor or short sale negotiator does more than upload documents.
They help control the file.
That means asking what type of valuation was ordered, watching for stale values, tracking whether the review was interior or exterior, collecting condition evidence early, and escalating when a bad value threatens approval.
They also help keep the agent from fighting the wrong fight. Sometimes the issue is not the BPO or appraisal itself. Sometimes the issue is missing investor approval, a net-proceeds requirement, a junior lien, an HOA payoff, or a closing deadline that is about to expire.
When the lender's value changes, the processor should help answer the next question:
Is this a value problem, a documentation problem, or a timing problem?
That distinction can save the file.
When a Second Review Makes Sense
A second value review may make sense when the first number clearly misses property condition, relies on bad comps, ignores major repairs, or was completed without interior access.
It may also make sense when the buyer has inspection findings that materially affect value or when the bank's counter is so far above market that the buyer is likely to walk.
But agents should be careful. Asking for a new review without new evidence can waste time. In some files, especially near foreclosure, time is the most valuable thing the agent has left.
If timing is becoming the bigger problem, agents should also review the separate guide on short sale BPO and appraisal delays before the file loses buyer patience or foreclosure time.
Before requesting another review, ask:
- What exactly was wrong with the first value?
- What evidence do we have now that the lender did not have then?
- Will the buyer stay in the deal long enough for the review?
- Is there a foreclosure date, auction date, or approval deadline creating pressure?
- Can the file close quickly if the value is corrected?
The best value dispute is not just accurate. It is timely.
What Sellers Should Understand
Sellers often assume the bank will accept any offer because the property is already upside down.
That is not how short sale review works.
The lender is not only looking at the seller's hardship. It is also looking at the expected recovery from the sale. If the bank believes the property is worth more than the offer, the lender may counter or ask for more support.
That can feel unfair, especially when the seller knows the home needs work. But the bank may not know that unless the file shows it clearly.
Sellers should help by giving access, allowing condition documentation, sharing known repair issues, and responding quickly when the short sale team needs updated documents.
The Bottom Line
BPO vs appraisal matters in a short sale because the lender's value can decide whether the buyer's offer gets approved, countered, delayed, or rejected.
But the label is not the whole story.
The more important issue is whether the bank's value reflects the real property, real condition, real comps, and real buyer risk. If it does not, agents need to respond with organized evidence, not panic.
A changed bank value does not automatically kill the short sale. But it does mean the file needs quick, focused handling.
If a BPO, appraisal, or bank value is putting your short sale at risk, Crisp Short Sales can help agents organize the value dispute, manage lender communication, and keep the approval path moving. Start the short sale process here: https://www.crispshortsales.com/start-short-sale
Can a Tenant Get Short Sale Relocation Assistance?
Why Tenant-Occupied Short Sales Get Confusing
Short sale relocation assistance sounds simple until the person living in the property is not the owner.
The seller may own the home. The tenant may occupy it. The buyer may want possession at closing. The lender may be reviewing the file under investor rules that talk about the borrower, the property, occupancy, or approved relocation expenses. The title company may need clean possession. The agent may be trying to keep everyone calm while foreclosure pressure builds.
That is a lot of moving parts.
The mistake is assuming the tenant automatically gets the relocation money because the tenant is the one who has to move.
Sometimes that may be possible. Sometimes the program is only for the borrower or seller. Sometimes the loan type, investor, or approval terms make tenant payments difficult. Sometimes a separate tenant agreement, local tenant-protection rule, or negotiated closing arrangement has to be handled outside the relocation-assistance line item.
The safest answer is this:
Do not guess. Confirm it in writing before anyone plans a move around the money.
Who Usually Gets Short Sale Relocation Assistance?
Short sale relocation assistance is usually tied to a specific program, investor guideline, or servicer approval. In many cases, the payment is meant to help an eligible borrower or seller transition out of the property after completing the short sale.
For example, Fannie Mae's borrower-facing foreclosure-avoidance fact sheet says a borrower may qualify for relocation assistance depending on the situation. Freddie Mac's short sale guidance and FAQ also frame relocation assistance around eligible borrowers, and Freddie Mac specifically says it will not issue relocation assistance to an eligible borrower who completes a short sale on an investment property.
That matters because a tenant-occupied property may be treated differently than an owner-occupied property.
If the seller does not live in the home, the agent should not assume the normal owner-occupant relocation expectation applies. If the tenant is the only person who has to move, the file needs a direct answer about whether any relocation payment can go to that tenant or whether the payment is unavailable under that program.
The Tenant Question Agents Should Ask Early
The most useful question is not, "Can the tenant get money?"
The better question is:
"Who does the short sale approval allow to receive relocation assistance, and under what conditions?"
That question forces the file into specifics. It also prevents a lot of closing-day stress.
Agents should confirm:
- Is the property owner-occupied, tenant-occupied, vacant, or partly occupied?
- Is there a written lease?
- Does the buyer need the tenant out before closing or after closing?
- Has the tenant been promised anything by the seller, buyer, or agent?
- Does the investor or servicer allow tenant relocation assistance?
- Does the approval letter name the payee?
- Does the settlement statement show the payment correctly?
- Are there state or local tenant rules that affect notice, possession, or move-out timing?
That last point is important. Short sale negotiators can help with the lender process, but legal rights under a lease or local tenant law should be handled by the proper local professional. The short sale approval does not erase tenant rights by itself.
Why the Approval Letter Controls the Answer
A tenant may hear that relocation help is available. A seller may repeat something a servicer said. An agent may see an old forum post about move-out money. None of that is enough.
The approval letter and closing instructions control the short sale.
If relocation assistance is approved, the written approval should make the payment structure clear. It should show the amount, the payee, the closing deadline, the required conditions, and how the funds will appear on the settlement statement.
If the letter only says the seller may qualify, that is not the same as approval.
If the letter names the borrower but everyone intends to pay the tenant, that needs clarification.
If the settlement statement does not match the approval terms, the closing can stall or the payment can be removed.
This is why Crisp's related post on what can cancel short sale relocation money is an important supporting article. Relocation help is usually conditional. The tenant situation adds one more layer of risk.
What If the Tenant Is the Reason the Sale Might Fail?
Tenant cooperation can affect the entire short sale.
If the tenant will not allow showings, the BPO or appraisal may be delayed. If the property cannot be accessed, the lender may not get the value review it needs. If the buyer cannot confirm possession timing, the buyer may walk. If the tenant moves out too early and the property is left vacant or damaged, the file may create new condition problems.
That does not mean the tenant is doing anything wrong. It means the file needs a clear plan.
For tenant-occupied short sales, agents should coordinate early with the seller, tenant, buyer side, title company, and short sale processor. Everyone should understand the move-out expectation before approval arrives.
The worst version is when the tenant hears about relocation money at the last minute and assumes a payment is guaranteed.
The better version is when the tenant question is handled as part of the short sale processing plan from the beginning.
What If the Seller Wants to Pay the Tenant?
Sometimes the relocation issue is not one of the usual short sale incentive programs. Sometimes the seller, buyer, or another party wants to solve a practical possession problem by offering the tenant money to move.
That may be possible in some transactions, but it has to be handled carefully.
In a short sale, side payments, undisclosed agreements, or hidden terms can create serious approval problems. The lender is approving the transaction based on the contract, settlement statement, net proceeds, liens, closing costs, and written representations from the parties.
If money is being paid to a tenant as part of the transaction, the safer path is to disclose it properly, confirm it with the right parties, and make sure it does not violate the approval terms or local law.
No one should quietly promise the tenant money and hope it works out later.
Why This Topic Matters for Agents
Agents do not need to know every investor guideline by memory. But they do need to know when a tenant-occupied short sale needs extra attention.
This is especially true when:
- The seller is an investor or absentee owner.
- The property is rented month to month.
- The lease runs past the expected closing date.
- The buyer wants vacant possession.
- The tenant is cooperative but needs help moving.
- The foreclosure date is close.
- The approval letter mentions relocation assistance but does not identify the payee.
- The tenant believes they were promised money.
Those are not small details. They affect closing.
A short sale processor or negotiator should help get the right questions in front of the servicer before the file reaches the finish line. The goal is not to create a fight over who gets paid. The goal is to make sure the file is honest, documented, and able to close.
What Tenants Should Understand
If you are a tenant in a short sale property, the owner selling the home short does not automatically mean you receive relocation money from the lender.
You may have rights under your lease or local law. You may need notice. You may have a move-out agreement. You may be asked to cooperate with showings, inspections, appraisals, or closing timelines.
But lender relocation assistance is a separate question.
Before relying on any promised payment, ask for the written terms. Who is paying it? Is it coming from the short sale lender, seller, buyer, or another party? Is it shown on the settlement statement? Is it tied to a move-out date? Does accepting it affect any agreement you already have?
Do not build your moving budget around a verbal promise.
The Bottom Line
A tenant can make a short sale more complicated, but not impossible.
The key is to separate three different questions:
- What rights does the tenant have?
- What does the short sale approval allow?
- What payment, if any, is properly documented for move-out?
When those questions are answered early, the file has a much better chance of closing smoothly.
When they are ignored, relocation money can become another last-minute problem.
If a tenant-occupied property is headed toward a short sale, get the occupancy facts, lease details, move-out timing, and relocation-assistance question into the file early. That is how agents protect the seller, keep the buyer informed, and avoid making promises the approval letter will not support.
If you are handling a tenant-occupied short sale and need help sorting out the lender process, you can start the short sale process with Crisp Short Sales before the move-out question becomes the reason the deal stalls.
HOA Dues in a Short Sale: Who Pays Before Closing?
Why HOA Dues Become a Closing Problem
HOA dues seem small compared with the mortgage payoff.
That is why they get ignored.
But in a short sale, a small ignored balance can become the reason the closing stops. The mortgage lender is already accepting less than the full payoff. The final settlement statement has to show where every dollar is going. If the HOA balance appears late, the lender may need to review the numbers again.
That can create a problem at the worst possible time.
The buyer is ready. The seller is trying to move. The closing date is close. Then title asks for an HOA payoff, the association sends a larger-than-expected balance, and everyone starts asking the same question:
Who pays this?
That question should be answered before the file reaches the closing table.
The HOA Usually Has to Be Resolved Before Closing
If the property is in a homeowners association, condo association, master association, or townhome community, the association may need to be paid before title can close cleanly.
The balance might include:
- Regular monthly or quarterly dues.
- Special assessments.
- Late fees.
- Attorney collection fees.
- Management company charges.
- Estoppel or resale certificate fees.
- Transfer fees.
- Lien recording or release fees.
The issue is not only whether the HOA wants money. The issue is whether the unpaid amount affects title, closing instructions, lender approval, or the final settlement statement.
If the HOA has recorded a lien or sent the account to collections, the short sale can get more complicated quickly.
So Who Pays HOA Dues in a Short Sale?
There is no one automatic answer. The payment structure depends on the short sale approval, local practice, the purchase contract, the HOA demand, and whether the lender/investor allows the charge.
Usually, the answer falls into one of five buckets.
1. The Seller Pays
The seller may be asked to pay the HOA balance if the lender will not allow it from sale proceeds or if the approval letter requires a seller contribution.
This sounds simple, but many short sale sellers are already in hardship. They may not have cash available for dues, late fees, or collection costs. If the seller cannot pay, the file needs another solution before closing.
The key is not to surprise the seller late. Ask early whether the HOA is current, behind, or in collections.
2. The Buyer Pays
In some short sale transactions, the buyer may agree to pay certain delinquent HOA assessments or other charges to make the closing work.
That cannot be handled casually.
Fannie Mae's public selling guidance recognizes that buyers in preforeclosure or short sale purchases may pay certain additional fees, assessments, or payments, including delinquent HOA assessments, but the details need to be documented and agreed to by the parties and shown on the settlement statement.
In plain English: if the buyer is paying a seller-side HOA problem, everyone needs to know, agree, and document it.
The buyer should not be surprised at closing. The servicer should not discover it after approval. The title company should not be forced to guess whether the payment is allowed.
3. The Short Sale Lender Allows It From Sale Proceeds
Sometimes the mortgage lender or investor may allow certain HOA amounts to be paid from the sale proceeds as part of the approved closing costs.
That is often the cleanest path when it is available.
But the lender may cap the amount, reject certain fees, or require a revised settlement statement. Regular dues may be treated differently from attorney fees, transfer fees, late charges, lien costs, or management company charges.
This is why the HOA balance should be on the estimated net sheet early. If the lender sees the number before approval, the file has a better chance of avoiding a last-minute re-review.
4. The HOA Reduces or Settles Part of the Balance
Sometimes the association, management company, or collection attorney may agree to reduce certain fees, waive part of the balance, or accept a settlement amount to clear the title issue.
This is not guaranteed.
It may depend on the community documents, state law, collection status, board approval, attorney involvement, and the amount owed. But if the balance is large and the short sale lender will not approve the full payoff, asking for a reduction may be better than letting the deal die.
A short sale negotiator may need to coordinate the HOA, title company, lender, buyer side, and seller so the settlement statement still works.
5. More Than One Party Contributes
Many short sale files are solved with a combination.
The lender may allow part of the HOA payoff. The buyer may agree to cover a transfer-related charge. The seller may contribute a small amount. The HOA may reduce attorney fees. The title company may need final written instructions before disbursement.
That is not unusual. The danger is trying to figure it out after approval expires or the buyer is already threatening to walk.
What Agents Should Collect Early
Agents do not need to become HOA attorneys. But they do need to spot the risk early.
At the beginning of the file, ask the seller:
- Is the property in an HOA, condo association, or master association?
- Are dues current?
- Have you received collection letters?
- Has the HOA recorded a lien?
- Is there a management company or collection attorney?
- Are there special assessments?
- Is a resale certificate, estoppel, or payoff required before closing?
Then get the current account balance or payoff information into the short sale package early.
If the file already has an offer, the estimated settlement statement should account for the HOA issue before the lender approval is issued. That is the safest way to prevent a surprise closing delay.
For a related checklist, see Crisp's guide on HOA dues in a short sale net sheet.
Why the Settlement Statement Matters
In a short sale, the settlement statement is not just closing paperwork. It is part of the approval structure.
The short sale lender is reviewing how much money comes in, what costs are paid, and how much the lender receives. If an HOA payoff, lien release, or buyer-paid assessment changes the numbers, the lender may need to approve that structure.
That is why verbal answers are risky.
"The buyer will just pay it" is not enough.
"The seller will handle it at closing" is not enough.
"The HOA said it is fine" is not enough.
The safer question is:
Does the final settlement statement match the short sale approval and the written agreement between the parties?
If the answer is no, stop and clarify before closing.
What If the HOA Sends the File to Collections?
Collection status changes the tone of the file.
Once an HOA account goes to a collection attorney, the balance may include legal fees, lien costs, interest, administrative charges, and release fees. The person answering the association's front desk may no longer control the payoff.
That is one reason Crisp previously covered HOA collection fees blocking your short sale.
If collections are involved, the agent should coordinate with title and the short sale processor quickly. The file may need:
- A formal payoff demand.
- A payoff good-through date.
- A lien release requirement.
- Confirmation of who can accept settlement.
- A revised net sheet.
- Written lender approval for the payment.
Waiting until the week of closing is how a small HOA issue becomes a short sale extension problem.
When to Order the Final HOA Payoff
There is a timing balance.
If the agent orders the final payoff too early, it may expire before the short sale is approved. If the agent waits too long, title may not have the final number needed to close.
The better process is:
First, identify the HOA and get an account balance early.
Second, include the estimated HOA amount on the net sheet so the lender sees the issue.
Third, once lender approval is realistic, order the final HOA payoff, estoppel, or resale statement so title has the exact number.
That is the same risk covered in Crisp's guide to the short sale HOA payoff letter.
Red Flags That Need Attention
Some HOA issues are routine. Others need immediate attention.
Watch for these warning signs:
- The seller is not sure whether dues are current.
- There are two associations.
- The HOA has a collection attorney.
- Title shows an HOA lien.
- The payoff includes large late fees or attorney fees.
- The buyer is being asked to pay a seller-side balance.
- The short sale approval letter does not match the settlement statement.
- The closing date is close and the HOA payoff is still missing.
If any of those show up, the file needs a clear written plan.
Why Short Sale Processing Helps
HOA dues are not the biggest number in a short sale, but they can be one of the easiest problems to miss.
A short sale processor or negotiator should be watching the full closing picture, not only the mortgage approval. That means tracking title issues, HOA balances, payoff demands, buyer expectations, seller contributions, and lender approval conditions.
Good short sale processing support makes the file cleaner before the closing deadline starts putting pressure on everyone.
The goal is simple: no mystery line items at the finish line.
The Bottom Line
HOA dues in a short sale can be paid by the seller, buyer, short sale lender through approved proceeds, the HOA through a reduction, or some combination of parties.
But nobody should guess.
The HOA balance needs to be identified early, included on the estimated net sheet when appropriate, approved in writing, and shown correctly on the final settlement statement. If there is a lien, collection attorney, special assessment, or large payoff demand, the issue needs attention before the approval clock is almost out.
If your short sale has HOA dues, collection fees, or a payoff problem, start the short sale process with Crisp Short Sales before a small balance turns into the reason the closing needs another extension.
Compliance / Accuracy Note
This article is practical short sale guidance, not legal advice. HOA rights, lien priority, buyer/seller payment obligations, collection rules, and deficiency issues can vary by state, association documents, loan type, investor, and closing instructions. Sellers and agents should involve the title company, attorney, servicer, and qualified local professionals when legal rights or title issues are involved.
Short Sale Relocation Assistance: What the Approval Letter Must Say
Why the Approval Letter Matters More Than the Verbal Answer
Relocation money is one of the most emotional parts of a short sale.
The seller is already leaving the home. Moving costs are real. Deposits, trucks, storage, utility transfers, and first-month rent do not wait politely while the lender reviews one more document.
So when a seller hears they may receive short sale relocation assistance, it is easy for everyone to treat that money as guaranteed.
That is where deals get dangerous.
In a short sale, the approval letter controls the transaction. A phone call, portal note, email comment, or casual "it should be fine" is not enough. The relocation assistance needs to match the written approval terms and the final closing documents.
If the written approval does not support the payment, the seller may be disappointed at the closing table. Worse, the agent may have helped the seller plan a move around money that was never properly confirmed.
What the Approval Letter Should Make Clear
Every investor, insurer, and servicer can handle short sale relocation assistance differently. Some programs may allow relocation expenses when certain conditions are met. Others may reduce or deny them based on contribution requirements, occupancy, government relocation help, investor rules, or the structure of the deal.
That is why the approval letter should be checked line by line.
At minimum, agents and sellers should look for six things.
1. The Relocation Assistance Amount
The letter should clearly state the approved relocation assistance amount or point to closing instructions that do.
Do not rely on an old estimate. Do not rely on a number from a prior negotiator. Do not assume the amount stayed the same after a counteroffer, seller contribution, junior lien negotiation, or closing extension.
If the amount is missing, ask before closing.
2. Who Gets Paid
The letter should make clear whether the payment goes to the borrower, seller, tenant, or another approved party.
That matters because some files involve divorce, estates, tenants, non-occupant owners, multiple borrowers, or government relocation support. If the payee is unclear, the settlement agent may not be able to disburse the money confidently.
The seller should know who receives the funds before they count on them.
3. When the Money Is Paid
Short sale relocation assistance is usually tied to closing. That means the seller may not receive the money before they move, before signing, or before the transaction funds.
This is a practical problem, not just a paperwork detail.
If the seller needs cash to move before closing, the approval letter may not solve that timing problem. The agent should make sure the seller understands when the funds are expected and whether any condition has to happen first.
4. Occupancy or Move-Out Conditions
Some relocation assistance is tied to occupancy, property condition, move-out timing, or cooperation through closing.
The approval should be checked for conditions such as:
- The property must be the seller's principal residence.
- The seller must vacate by a certain date.
- The property must be left in acceptable condition.
- The seller must not receive other prohibited funds.
- The seller must sign required closing documents.
- The sale must close by the approval deadline.
If a condition is there, treat it seriously. If the seller violates it, the money may be delayed, reduced, or lost.
This is why the earlier post on what can cancel short sale relocation money should be part of the internal link path from this article.
5. Seller Contributions and Other Assistance
Relocation assistance can be affected by seller contributions, borrower cash reserves, employer relocation help, government relocation benefits, or other money connected to the move.
Fannie Mae's servicing guidance, for example, has specific relocation-assistance rules and says servicers must account for certain other relocation assistance sources. HUD also notes that FHA Pre-Foreclosure Sale borrowers may be eligible for relocation expenses if conditions are met.
The practical point for agents is simple: do not assume the seller can receive every possible payment in addition to every other concession.
If the file includes a seller contribution, junior lien settlement, employer relocation benefit, military move support, tenant payment, or other unusual payment, the approval letter needs careful review.
6. The Settlement Statement Line Item
Even if the approval letter is clear, the final settlement statement still has to match it.
The relocation assistance should appear correctly on the settlement statement if the program requires it to be paid through closing. The settlement agent, short sale negotiator, and servicer should all be aligned before signing.
This is one of those small details that can become a closing-day crisis.
If the approval says the seller gets relocation assistance but the settlement statement does not show it, pause and fix the mismatch before closing.
The Most Dangerous Approval Letter Mistakes
Agents should watch for approval letters that create false confidence.
Common problems include:
- The relocation amount is not listed.
- The letter says the seller "may" receive assistance but does not approve it.
- The approved amount changed after a revised net sheet.
- The closing date is too close and no extension is approved.
- The letter requires the property to be vacant, but the seller has not planned move-out.
- The seller contribution changed and may affect assistance.
- A junior lien, HOA balance, or judgment still needs funds.
- The settlement statement does not show the relocation payment.
- The approval letter and portal notes do not match.
None of those issues should be ignored.
Short sale approval is not just permission to sell. It is a set of closing instructions. The relocation-money piece has to fit inside those instructions.
Why This Matters for Homeowners
For a homeowner, relocation assistance can be the difference between a controlled move and a desperate one.
But it is not the same as sale proceeds. In a short sale, the seller is not walking away with equity. The lender or investor is allowing a sale for less than the full payoff, and any relocation assistance is subject to the rules of that approval.
That means sellers should avoid making promises to landlords, movers, family members, or creditors until the written approval and closing statement are clear.
The safest question is not, "Did they say I get relocation money?"
The safest question is, "Where does the written approval say I get it, how much is it, and what has to happen before it is paid?"
Why This Matters for Agents
Agents do not need to become attorneys or servicer policy experts. But they do need to protect the file from avoidable misunderstandings.
If the seller is relying on relocation assistance, the agent should make sure the short sale processor or negotiator checks the approval letter before closing momentum takes over.
This is especially important when:
- The seller is still occupying the home.
- The seller needs the funds to move.
- There is a foreclosure deadline.
- The approval letter has a short closing window.
- The file has HOA, lien, tax, or title issues.
- A second mortgage is involved.
- The servicer has issued revised approval terms.
Experienced short sale processing support helps because someone has to track the details that do not show up in the MLS remarks. The buyer, seller, title company, servicer, and negotiator all need the same understanding before the file reaches the closing table.
Relocation Assistance vs Incentive Programs
The phrase "relocation assistance" often gets mixed together with short sale incentive programs, cash for keys, tenant relocation payments, government move benefits, and investor-specific seller incentives.
Those are not always the same thing.
That is why the approval letter matters. It should identify the payment being approved, the source of that payment, and the conditions attached to it.
If the seller is not sure whether the money is relocation assistance, an incentive, tenant payment, or another type of approved disbursement, get the answer in writing.
The label matters because the rules can be different.
Do Not Use Relocation Money to Patch Other Problems Without Approval
One closing mistake is treating the seller's relocation money as a backup fund for everything else.
An unpaid HOA balance appears. A title issue needs a payoff. A junior lien wants more money. Someone suggests using the relocation assistance to cover the gap.
Do not assume that is allowed.
Some investor rules restrict how relocation assistance can be handled. Some approvals may prohibit using seller funds for other liens or closing problems unless the investor or servicer specifically permits it.
If the deal has a lien or payoff problem, solve that problem directly. Do not quietly move relocation money around and hope nobody notices.
Short sale closing files are reviewed. The settlement statement matters.
Bottom Line
Short sale relocation assistance is only as useful as the written approval behind it.
Before the seller counts on the money, the approval letter should answer the key questions: Is the assistance approved? How much is approved? Who receives it? When is it paid? What conditions apply? Does the settlement statement show it correctly?
If any answer is missing, get clarification before closing.
That may feel tedious, but it is far better than discovering the problem after the seller has already packed boxes, scheduled movers, and told themselves the move-out money is handled.
If the short sale is already moving toward approval and relocation assistance matters to the seller, get short sale help before the closing deadline turns a paperwork question into a moving-day problem.