

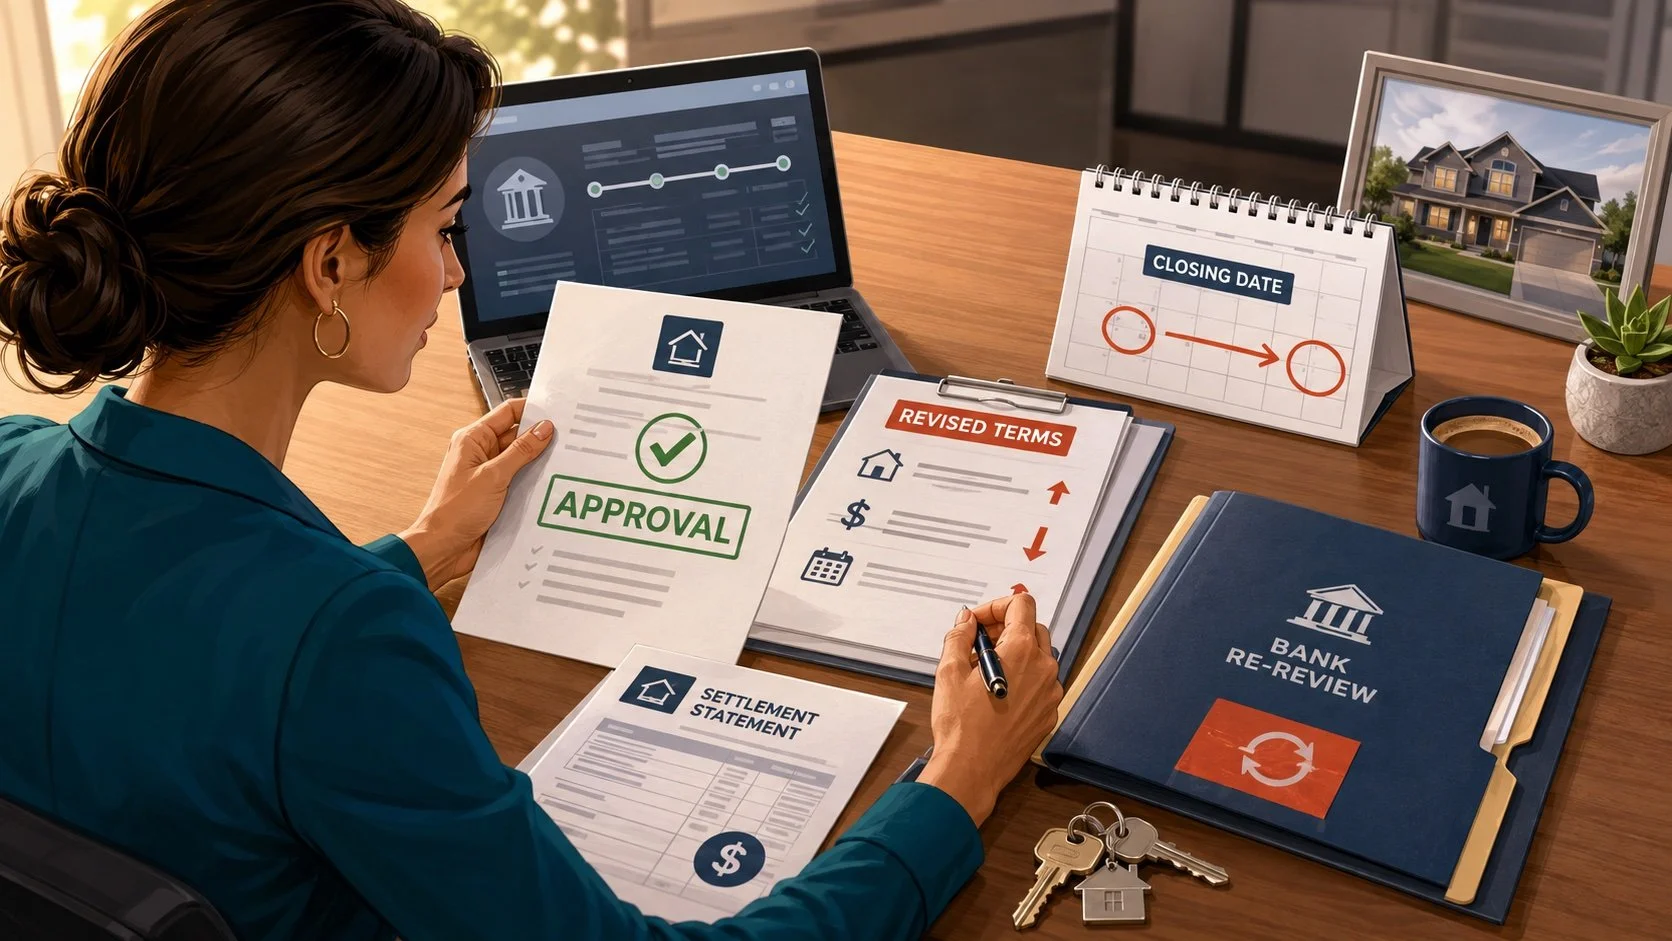
Changed Terms After Short Sale Approval: What Must Go Back to the Bank
Short sale terms changed after approval? See which buyer, price, date, credit, lien, or settlement changes need bank re-review.
Why Changed Terms Matter After Approval
A short sale approval letter can feel like the hard part is over.
The seller finally has an answer. The buyer is ready. The agents want to close. Title is pushing for final numbers. Everyone has waited long enough.
But short sale approval is not a blank approval for any version of the deal.
It is approval of a specific transaction under specific terms. The approval letter may name the buyer, sale price, required net proceeds, closing deadline, allowed closing costs, commission, relocation assistance, seller contribution, junior lien payments, and final settlement-statement conditions.
If those terms change, the bank may need to review the file again before closing.
That does not always mean the short sale is in trouble. Many changes can be handled. The problem is when the team treats a changed deal like it is still the same approved deal.
For a deeper look at approval-letter conditions, see Crisp's guide to short sale approval letter clauses that can delay closing.
Changes That Usually Need Bank Review
Some changes are too important to handle casually.
The short sale team should assume the bank may need to review the file again when any of these items change:
- Purchase price.
- Buyer name or buyer entity.
- Closing date or approval expiration date.
- Seller credit, buyer credit, repair credit, or concession.
- Commission or transaction fee.
- First-lien payoff figures.
- Junior lien payoff or settlement terms.
- HOA, tax, municipal, judgment, or title payoff numbers.
- Relocation assistance or incentive payment.
- Seller contribution or promissory-note requirement.
- Occupancy or move-out condition.
- Final settlement statement or closing disclosure.
- Arm's-length affidavit, resale restriction, or investor-specific condition.
The practical question is not whether the change seems small.
The practical question is whether the change affects the terms the bank approved.
Buyer Changes Are Not Just Paperwork
A buyer change can be a major short sale issue.
The bank may have approved a specific buyer, proof of funds, financing type, closing timeline, and contract structure. If the original buyer assigns the contract, changes entities, adds or removes a buyer, switches financing, or is replaced by a new buyer, the servicer may need to approve the changed buyer before closing.
Agents should be especially careful when the buyer is an investor, trust, LLC, related party, employer-relocation program, or any structure that could raise arm's-length or resale concerns.
The file may still be approvable. But the buyer change should be disclosed and handled in writing.
Price Changes Can Restart the Math
If the purchase price changes after approval, the short sale math changes.
A higher price may improve the bank's net, but the file still needs to match the written approval and settlement statement. A lower price is more sensitive because it can reduce the bank's expected recovery and may require investor, mortgage insurer, or servicer approval.
Price changes should be supported by the correct addendum and a revised settlement statement. If the price changed because of inspection issues, repair conditions, appraisal problems, or buyer financing, the short sale negotiator should explain the reason clearly instead of sending a vague update.
For related closing-number issues, review Crisp's article on what happens when a short sale net sheet changed and the bank may re-review.
Closing Date Changes Can Create Approval Problems
Short sale approval letters usually include a closing deadline.
If the buyer's loan is delayed, title is not clear, payoff figures are stale, HOA documents are late, or signatures are not ready, the team may need an extension before the approval expires.
Do not wait until the final day.
The approval letter may require closing, funding, recording, or settlement by a specific date. Moving the closing date can also change payoff interest, taxes, HOA dues, prorations, and final net proceeds.
That means a date change can become a number change.
If the closing date moves, the short sale coordinator should check both the approval deadline and the updated settlement statement before telling everyone the file is still clear to close.
Credits and Concessions Need Careful Review
Buyer credits, seller credits, inspection credits, repair credits, and closing-cost concessions can be normal in regular real estate transactions.
In a short sale, they can be approval issues.
The seller usually cannot agree to give away money that changes the lender's recovery unless the short sale lender accepts that structure. A credit that looks harmless to the buyer and seller may reduce the bank's net or violate the approval terms.
Before adding or changing a credit, ask:
- Is the credit allowed in the approval letter?
- Does it reduce the lender's net?
- Is it shown correctly on the settlement statement?
- Does it require a revised addendum?
- Does the buyer's lender also approve it?
- Does the servicer need written approval before closing?
If the answer is unclear, slow down and get written direction.
Lien and Title Changes Can Stop the Closing
Title issues often appear late because short sales take time.
A second mortgage payoff can change. A judgment can appear. HOA fees can grow. Taxes can update. Municipal balances can surface. A prior mortgage release can be missing. Probate, divorce, bankruptcy, or ownership issues can complicate signing authority.
Those items can affect whether the approval still works.
If a junior lienholder demands more money than the approval allows, the first lender may need to approve the revised allocation. If an HOA or municipal lien must be paid from closing proceeds, the settlement statement may need to change. If the title company cannot insure the transaction under the approved terms, the file is not truly ready.
This is why title review should happen early and then again before closing. Crisp has a related guide on what title must confirm before short sale closing.
How to Send the Change Back Correctly
When changed terms need bank review, the update should be specific.
Do not send a bundle of revised documents with no explanation.
A clean update should include:
- What changed.
- Why it changed.
- Whether the purchase price changed.
- Whether the buyer changed.
- Whether the closing date changed.
- Whether the bank's expected net changed.
- Which settlement-statement lines changed.
- Which approval-letter condition is affected.
- What written approval, extension, or clarification is being requested.
The goal is to make the reviewer answer the right question quickly.
If the bank only needs to approve an extension, ask for the extension. If the bank needs to approve a lower net, explain the lower net. If a lien payoff changed, show the prior number, new number, and reason.
Specific changes get cleaner answers.
What Agents Should Not Do
The biggest mistake is assuming the bank will accept the final closing package because the short sale was already approved.
Agents should avoid:
- Letting title close with numbers that do not match the approval letter.
- Promising a buyer credit before lender approval.
- Changing the buyer entity without disclosure.
- Waiting until the approval expires to ask for an extension.
- Treating a new lien payoff as a title-only issue.
- Assuming relocation assistance is safe if the approval language changed.
- Sending revised terms without explaining the impact on the bank's net.
Short sales need momentum, but momentum without written approval can create a closing failure.
The Bottom Line
After short sale approval, every meaningful change should be checked against the approval letter.
If the changed term affects the buyer, price, closing date, settlement statement, payoff, lien release, credit, seller money, relocation assistance, or approval condition, get the short sale processor or negotiator involved before closing.
The file may not need a full restart. It may only need a corrected approval, extension, revised settlement statement, or written clarification.
But that answer needs to come from the right place.
If the transaction changed after approval, the safest question is:
Does the written short sale approval still match the deal we are about to close?
If not, Crisp can help agents organize the changed terms, explain the issue to the servicer, and keep the file moving toward a closing that actually matches the approval.
Frequently Asked Questions
What changes after short sale approval need bank review?
Buyer, price, closing date, seller credit, lien payoff, relocation, seller contribution, and settlement-statement changes may need written bank review before closing.
Can a short sale close if the terms changed after approval?
It can sometimes close, but the team should confirm in writing that the lender accepts the changed terms before signing or funding.
Does a changed closing date need a new short sale approval letter?
It may require a written extension or revised approval if the original approval letter has a deadline that the new closing date will miss.
This article is general information, not legal advice. Short sale approval terms, foreclosure timelines, deficiency language, and closing requirements can vary by loan, investor, servicer, and state. Sellers should speak with a qualified attorney or housing counselor when legal rights or foreclosure deadlines are involved.

Short Sale Net Sheet Changed? Why the Bank May Re-Review
Short sale net sheet changed before closing? See why taxes, HOA, liens, credits, or payoff updates can trigger bank re-review.
In a normal sale, a changed closing number may be a quick update between the agents, lender, and title company.
In a short sale, it can be a bigger deal.
The short sale lender is not only reviewing the sales price. The lender is reviewing what it expects to receive after approved closing costs, taxes, HOA balances, junior liens, commissions, concessions, payoff changes, and title expenses. If those numbers change, the lender may need to re-check the file before issuing approval or allowing closing to move forward.
That is why a short sale can feel ready and then suddenly get quiet again.
This guide is practical short sale process guidance for agents and sellers. It is not legal advice. If foreclosure notices, deficiency language, seller liability, or legal deadlines are involved, the seller should speak with a qualified attorney or housing counselor.
Why The Net Sheet Matters In A Short Sale
The net sheet, sometimes called an estimated settlement statement, shows how the sale money is expected to move at closing.
For the short sale lender, the key question is simple:
After allowed costs and payoffs, how much money does the lender receive?
That expected amount can affect whether the servicer, investor, mortgage insurer, or junior lienholder accepts the short payoff. A buyer can offer the same purchase price, but the lender's expected recovery can still change if the settlement statement changes.
That is why agents should treat the net sheet as part of the short sale approval package, not as a harmless closing worksheet.
For a broader view of file delays, see Crisp's guide on why short sale approval can take longer.
What Changes Can Trigger A Bank Re-Review
A short sale can go back to review when the new numbers change what the lender expected to receive or what the lender previously approved.
Common triggers include:
- Property taxes updating before closing.
- HOA dues, estoppel fees, collection costs, or transfer fees changing.
- A junior lien payoff coming in higher than expected.
- A municipal lien, utility balance, judgment, or title issue appearing late.
- Buyer credits or repair credits reducing the lender's net.
- Closing costs increasing.
- Commission, transaction, or administrative fees changing.
- Payoff interest increasing because the closing date moved.
- The buyer, loan type, closing date, or purchase price changing.
- The final settlement statement not matching the approval letter.
Not every change kills a short sale. But the team should not assume the lender will accept a lower net without written confirmation.
Taxes, HOA Balances, And Municipal Charges Can Move Late
Property taxes and HOA amounts often change because the file takes time.
A tax prorate may update. An HOA estoppel may show new dues, late fees, legal fees, transfer fees, or collection costs. A city or utility balance may appear after title review. Even if each item seems small by itself, together they can reduce the lender's net proceeds.
That matters because the lender may have approved one version of the math and then receive a different version before closing.
If HOA numbers are involved, agents should also review Crisp's guide on the HOA estoppel letter in a short sale. HOA balances can be especially sensitive because the association, title company, buyer, seller, and lender may all be looking at the same charge from different angles.
Junior Liens And Payoff Changes Can Break The Math
Junior liens create another common net-sheet problem.
A second mortgage, judgment lien, tax lien, HOA lien, or other payoff may demand more than the first lender expected to allow. If the first lender approved only a limited payment to a junior lienholder, a higher demand can create a gap.
The agent should not try to smooth over that gap verbally.
The short sale processor or negotiator should confirm:
- What each lienholder is demanding.
- What the first lender previously approved.
- Whether the junior lienholder will accept the approved amount.
- Whether the settlement statement matches the written approval terms.
- Whether the first lender must approve a revised payoff allocation.
This is where short sale assistance can prevent late-stage confusion. The issue is not only whether the lien exists. The issue is whether every payoff can close inside the lender's approved numbers.
Buyer Credits And Repair Credits Can Lower The Lender's Net
Buyer credits can be normal in real estate, but they are not automatically harmless in a short sale.
If the buyer asks for a closing cost credit, repair credit, inspection credit, seller concession, or price adjustment, the lender may treat that as a change to the deal. Even if the seller agrees, the seller may not have authority to give away money that affects the lender's recovery.
The right question is not only:
Will the buyer accept this?
The better short sale question is:
Will the lender approve this and still receive the required net?
If a credit appears after short sale approval, title and the agents should compare the new settlement statement against the approval letter before closing. Crisp has a related guide on what title must confirm before short sale closing.
Closing Date Changes Can Create Payoff Problems
Short sale files often run close to deadlines.
When the closing date moves, several numbers can change at once. Payoff interest may increase. Tax prorations may shift. HOA dues may roll into a new month. Buyer financing costs may change. The approval letter may also have a closing deadline that cannot be ignored.
A small extension can therefore become more than a calendar issue.
Before assuming the short sale is still approved, the team should check:
- Does the approval letter allow the new closing date?
- Do payoff figures remain valid?
- Did taxes, HOA, or other prorations change?
- Does the lender need an updated settlement statement?
- Does the buyer still qualify and remain ready to close?
If the answer is unclear, the short sale coordinator should ask for written confirmation before the file reaches signing.
How To Explain The Change To The Lender
When a net sheet changes, the update should be organized and specific.
Do not send a vague note that says, "See revised settlement statement."
A better note explains what changed and why it matters:
- The prior estimated net.
- The revised estimated net.
- The exact line items that changed.
- The reason for each change.
- Whether the purchase price changed.
- Whether buyer credits or seller concessions changed.
- Whether any lien, tax, HOA, payoff, or title item caused the change.
- Whether the file still meets the lender's required net.
- Whether closing is inside the approval deadline.
This helps the negotiator, servicer, investor, or mortgage insurer review the actual issue instead of reopening the entire file blindly.
What A Short Sale Processor Should Check Before Resubmitting
Before resubmitting a changed net sheet, a short sale processor should make sure the file is clean.
The checklist should include:
- Current purchase contract and addenda.
- Updated estimated settlement statement.
- Current first-lien payoff.
- Junior lien payoff demands.
- HOA estoppel or payoff.
- Tax, utility, municipal, or title charges.
- Buyer proof or loan approval if the buyer timeline changed.
- Approval-letter conditions if approval was already issued.
- Foreclosure, auction, or sale-date deadline if one exists.
The goal is not to send more documents than necessary. The goal is to send the right documents so the lender can approve the changed math without creating another delay.
When The Change Is Probably Small
Some changes are easier to handle.
A minor tax prorate update, a small recording-fee adjustment, or a closing-cost correction may be acceptable if the lender's net remains the same or improves. Even then, title should document the change and confirm whether lender approval is needed.
If the lender receives more than expected, the issue may be simple.
If the lender receives less than expected, the issue deserves more caution.
When The Change Is A Bigger Risk
A changed net sheet becomes more serious when it reduces the lender's net, changes the buyer's credit, adds an unapproved payoff, alters commission or fees, changes the buyer or price, or moves closing beyond the approval deadline.
Those are the moments where the file can go back to:
- Servicer review.
- Investor review.
- Mortgage insurance review.
- Junior lien review.
- Title or closing review.
That re-review can be frustrating, but ignoring it is worse. If the final settlement statement does not match the written approval, the closing package may be rejected or the closing may need to be paused.
Where Crisp Short Sales Helps
Crisp Short Sales helps agents organize short sale processing, lender follow-up, settlement-statement review, approval-letter conditions, payoff issues, HOA balances, lien questions, and closing deadlines.
The changed-net-sheet stage is where details matter.
The buyer may still be ready. The seller may still want the sale. The contract may still be intact. But if the bank's expected net proceeds changed, the file needs a clear explanation and written lender direction before closing.
If the short sale net sheet changed, start with one practical question:
Did the lender's expected net go down, and if so, has that change been approved in writing?
Crisp can help agents get that answer, organize the revised numbers, and keep the file moving toward a clean approval.
Frequently Asked Questions
Why would a bank re-review a short sale net sheet?
A bank may re-review the net sheet if taxes, HOA balances, junior liens, buyer credits, closing costs, payoffs, or closing dates change the lender's expected net proceeds.
Does the short sale price matter more than the net sheet?
No. The price matters, but the lender also reviews the net amount it expects to receive after approved costs, liens, and payoffs.
Can a buyer credit delay short sale approval?
Yes. A buyer credit can reduce the lender's net and may need written lender approval before closing.
What should an agent do when the settlement statement changes?
Compare the new statement to the prior net sheet and approval terms, identify the exact changes, and ask the short sale lender whether written re-approval is required.

HOA Estoppel Letter in a Short Sale: What Must Match Before Closing
HOA estoppel mismatch can stop a short sale late. See what agents should verify before lender approval and closing numbers fall apart.
An HOA estoppel letter can look like a routine closing document.
In a short sale, it can become the document that stops everything.
The lender may have reviewed the seller's hardship. The buyer may be ready. The approval letter may be close. Title may be working toward closing. Then the homeowners association balance arrives, and the numbers do not match the short sale approval, the net sheet, or the closing statement.
That is when a short sale can stall late, even after everyone thought the hard part was over.
If a property is part of a homeowners association, condo association, or community association, the HOA estoppel letter needs to be handled early and checked carefully. It is not just a balance statement. It tells the closing team what the association says is owed as of a certain date, and it can include more than regular monthly dues.
For short sale processing, the key question is simple: does the HOA number match what the lender approved and what closing can actually pay?
Why HOA Estoppel Letters Matter More in a Short Sale
In a regular sale, an HOA balance still matters. The seller, buyer, title company, and closing agent need to know what must be paid so title can transfer cleanly.
In a short sale, there is an extra problem: the mortgage lender is already accepting less than the full loan payoff. That lender usually reviews the estimated closing statement before approval. If the HOA balance changes after approval, the numbers may no longer fit.
That creates pressure on several sides:
- The HOA wants its balance paid.
- The seller may not have cash to cover extra fees.
- The buyer may not want to absorb surprise costs.
- The title company needs clean payoff instructions.
- The lender may not allow new charges that reduce its approved net.
- The approval letter may expire before the issue is resolved.
This is why HOA dues in a short sale cannot be treated as a final-week detail. The estoppel should be ordered, reviewed, and matched to the short sale approval path before closing pressure gets tight.
What Must Match Before Closing
The HOA estoppel letter should be checked against the short sale file, not just placed in the closing folder.
Here are the items that should match before closing.
1. The Property and Association Must Be Correct
Start with the basics.
Confirm the property address, unit number, association name, management company, owner name, and account number. This matters more than it sounds.
Some properties have more than one association. A condo may have a master association and a sub-association. A planned community may have a neighborhood association plus a separate management company handling collections. If only one estoppel is ordered, title can still find another balance later.
For a short sale, that late discovery can create a new lender-approval problem.
Agents should ask early whether the property has:
- A homeowners association
- A condo association
- A master association
- A sub-association
- A special assessment district
- A collection attorney or management company handling delinquent dues
If there are multiple associations, each one may need its own payoff or estoppel.
2. The Balance Must Match the Net Sheet
The short sale lender usually reviews an estimated closing statement or net sheet. That document shows what the lender expects to receive after approved closing costs and payoffs.
If the HOA estoppel balance is higher than the number on the net sheet, the file may no longer match the lender's approval path.
Common mismatch causes include:
- Past-due dues that were not included earlier
- Late fees added after the first payoff estimate
- Collection costs or attorney fees
- Transfer or resale fees
- Special assessments
- Violation fines
- Rush estoppel fees
- Updated monthly dues through the new closing date
The safest move is to compare the estoppel against the short sale net sheet as soon as it arrives. Do not wait until the closing package is being balanced.
If the number changed, the short sale negotiator or processor needs to know whether the lender must approve the revised amount.
3. The Payoff Date Must Match the Closing Date
An HOA estoppel is usually tied to a date.
It may show the amount owed through a specific date, or it may include instructions for adding future monthly dues if closing happens later. That date matters.
If the short sale approval expects closing by one date, but the HOA payoff only runs through another date, the closing statement can become wrong quickly. A small monthly due can turn into a last-minute shortage if nobody updates the number.
Agents should verify:
- The date through which the HOA amount is valid
- Whether another monthly due will post before closing
- Whether late fees or interest continue to accrue
- Whether a new estoppel is required after a certain date
- Whether the HOA requires certified funds, wire instructions, or a specific payment method
Short sale approvals already have closing deadlines. The HOA payoff clock should not be allowed to create a second deadline nobody is tracking.
4. Collection and Attorney Fees Must Be Clear
HOA balances can grow quickly once a delinquent account goes to collections.
The regular dues may be manageable, but the total payoff may include collection fees, attorney costs, lien recording fees, interest, late charges, administrative fees, or violation fines. In some files, those costs are the real problem.
This is where agents get surprised. They may know the seller is behind on HOA dues, but they may not know the account has moved to a collection attorney.
That matters because the short sale lender may not automatically approve every added charge. If the net proceeds are already tight, the file may need a revised approval, a fee reduction, seller contribution, buyer contribution, or a negotiated payoff.
The processor should separate:
- Regular dues
- Past-due assessments
- Late fees
- Collection fees
- Attorney fees
- Transfer fees
- Special assessments
- Violation fines
- Estoppel or rush fees
The more precise the breakdown, the easier it is to decide what needs lender approval and what can be negotiated.
5. The Approval Letter Must Allow the Payment
A short sale approval letter does not always allow every closing cost automatically.
Some approval letters cap seller-paid costs. Some restrict junior lien payments. Some limit HOA payments. Some require the final closing statement to match the approved net. Some allow certain settlement charges only if they were disclosed before approval.
That is why the HOA estoppel has to be checked against the short sale approval letter, not just against the title file.
The question is not only, "What does the HOA say is owed?"
The question is, "Can this amount be paid under the lender's approval terms?"
If the approval letter does not allow the HOA amount, the file may need lender review before closing. Trying to solve that after documents are signed can create avoidable delay.
6. Title Must Know Whether the HOA Has a Lien
Unpaid HOA dues may create a lien or title issue, depending on the association documents and state law. Rules vary by state, so the closing team should verify the title status instead of assuming.
For practical short sale purposes, the main issue is clear: an unresolved HOA balance can prevent clean title transfer.
If the HOA has recorded a lien, title needs payoff instructions. If the HOA has not recorded a lien but still shows a delinquent balance, the closing team still needs to know whether the association will issue clearance after payment.
The agent does not need to practice law. But the agent does need to make sure the HOA issue is visible to title, the short sale processor, and the lender before closing day.
What Agents Should Do When the Estoppel Number Is Higher Than Expected
If the HOA estoppel comes back higher than expected, do not assume the short sale is dead. Start by identifying the mismatch.
Use this sequence:
- Compare the estoppel to the latest net sheet.
- Identify which charges changed.
- Confirm the payoff-good-through date.
- Ask title whether the HOA balance affects clear title.
- Check whether the short sale approval letter allows the payment.
- Ask the lender or servicer whether the revised HOA amount needs approval.
- If needed, negotiate with the HOA, management company, or collection attorney.
- Update the closing statement before the approval window gets tight.
The worst move is to ignore the number because closing is close. Short sale closing problems usually get harder, not easier, when everyone waits.
What Sellers Should Know
Sellers are often surprised by HOA estoppel numbers.
They may remember the monthly dues, but not the late fees. They may not know the account went to collections. They may not realize a special assessment was added. They may assume the short sale lender will cover everything because the lender approved the sale.
That is not always how it works.
Sellers should tell their agent and short sale processor early if the property has an HOA, condo association, or management company. They should also provide any notices, account statements, collection letters, or lien notices they have received.
The goal is not to blame the seller. The goal is to keep the HOA number from appearing too late to solve.
How a Short Sale Processor Helps
A good short sale processor or short sale coordinator watches the numbers before they become closing emergencies.
For HOA files, that means:
- Asking early whether the property has an HOA or condo association
- Making sure title knows about every association
- Tracking when the estoppel is ordered
- Comparing the estoppel to the short sale net sheet
- Watching payoff-good-through dates
- Confirming whether collection fees are included
- Checking whether lender approval allows the HOA payment
- Escalating mismatches before the approval letter expires
This is not just paperwork. It is closing-risk control.
The lender, title company, buyer, seller, and HOA all have different priorities. Someone needs to make sure the numbers line up before closing day.
The Bottom Line
An HOA estoppel letter can stop a short sale if the amount owed, payoff date, collection fees, approval-letter terms, and closing statement do not match.
The fix is not to wait for title to catch it at the end.
Order the estoppel early. Confirm every association. Compare the balance to the net sheet. Check the approval letter. Watch the payoff date. If the number changed, find out whether the lender must approve the revised closing statement.
Short sales are already deadline-sensitive. HOA surprises should not be allowed to create another delay when the file is almost ready to close.
Crisp Short Sales helps agents and homeowners manage short sale processing, lender approval conditions, title issues, HOA payoffs, and closing deadlines. If an HOA estoppel amount does not match the short sale approval path, it is better to catch it before the closing window starts closing.
Frequently Asked Questions
What is an HOA estoppel letter in a short sale?
It is a statement from the homeowners association or condo association showing the account status, amounts owed, fees, payoff date, and payment instructions needed for closing.
Can HOA dues stop a short sale from closing?
Yes. If HOA dues, collection fees, attorney fees, or payoff amounts are not approved or paid correctly, they can delay closing or create a title problem.
Who orders the HOA estoppel letter?
The title company or closing agent often orders it, but agents and short sale processors should confirm early that every association has been identified.
What should agents compare against the HOA estoppel?
Compare the estoppel amount to the short sale net sheet, lender approval letter, closing statement, payoff-good-through date, and title requirements.
Texas Short Sale Approval vs. Closing Timeline: Two Clocks to Protect
A Texas short sale can have two deadlines: lender approval and final closing. Learn what to verify before a sale date or approval letter expires.
Why Approval Is Only One Clock
A Texas short sale can feel approved before it is actually safe. The lender may issue an approval letter, but the file still has to close before the approval expires and before any foreclosure sale date or Texas-specific deadline creates a second problem.
That is why agents, sellers, and investors should track two separate clocks: the approval clock and the closing clock. When those clocks are treated as the same thing, the file can lose time at the exact moment everyone thinks the hard part is over.
A short sale approval letter usually answers one major question: will the lender accept less than the full loan payoff under the terms submitted? That is a huge milestone, but it is not the finish line.
The approval letter may include a closing deadline, required net proceeds, buyer name, approved purchase price, approved commissions, seller contribution language, deficiency terms, and document conditions. If any of those pieces do not match the contract or closing file, the deal can stall even after approval.
In Texas, the timeline matters even more because foreclosure-sale pressure can keep moving while the short sale is being reviewed. A seller may need short sale help quickly, but the real protection comes from matching the lender approval timeline to the closing timeline.
The Closing Clock Starts After Approval
Once approval arrives, the closing team still needs clear title, final settlement numbers, buyer readiness, lender payoff alignment, and any required signatures. If the approval letter expires before those items are complete, the file may need an extension or updated approval.
That is where a short sale processor, short sale negotiator, or short sale coordinator can prevent avoidable delays. Someone has to compare the approval letter against the contract, closing disclosure or settlement statement, payoff figures, and expected funding date.
The biggest mistake is assuming the lender approval means everyone can relax. In reality, approval should trigger a tighter checklist.
What To Verify Immediately
As soon as the approval letter comes in, confirm the expiration date and closing deadline. Then verify the buyer, price, credits, commissions, net proceeds, seller contribution, occupancy or relocation language, and any deficiency or release terms.
Next, confirm that the title company can close inside the approved window. If title, payoff, HOA, lien, probate, bankruptcy, buyer financing, or investor-signature issues are still open, the short sale team should request an extension before the clock gets too tight.
For Texas files, also confirm whether a foreclosure sale date, posting deadline, or attorney timeline is still active. The short sale approval clock does not automatically erase every foreclosure-process deadline, so experienced short sale assistance can matter most after approval.
How The Two Clocks Should Work Together
The lender approval clock tells you how long the lender's short sale terms remain valid. The closing clock tells you whether the transaction can actually fund and record before those terms expire.
A clean short sale workflow keeps both visible. The short sale negotiator watches lender terms and extensions. The coordinator watches title, signatures, payoff, buyer readiness, and closing logistics. The agent keeps the seller and buyer moving so no one loses days to assumptions.
When those roles are clear, a Texas short sale has a better chance of moving from approval to closing without a last-minute scramble.
Bottom Line
A Texas short sale is not fully protected just because the lender says yes. The safer question is whether the approval deadline, foreclosure pressure, and final closing timeline all line up.
If those clocks do not match, ask for short sale processing support before the approval window gets too close. A focused short sale specialist can help identify the deadline risk, communicate with the lender, and keep the file moving toward a real closing.
This article is general information, not legal advice. Texas foreclosure timelines and deficiency rights can be serious, so sellers should speak with a qualified attorney about legal consequences before relying on any short sale decision.
Frequently Asked Questions
Is a Texas short sale safe once the lender approves it?
Not automatically. The file still has to close before the approval expires and before any foreclosure-sale pressure or closing condition creates a new delay.
What should agents check first after short sale approval?
Check the expiration date, required net, buyer name, approved price, credits, commissions, payoff alignment, title status, and whether closing can happen inside the approval window.
When should a short sale extension be requested?
Request an extension as soon as it is clear title, buyer financing, payoff figures, signatures, or closing logistics may not be ready before the approval deadline.
Does short sale approval stop a Texas foreclosure sale date?
Do not assume it does. Texas files should be checked for active sale dates, posting deadlines, and attorney timelines even after a lender approval letter arrives.